Three core papers plus long and short options.
The initial table of content was limited to the first level because it is larger than 1000 articles. There are 1694 articles in total. Expand a branch to load its children.
Core differential equation paper.
Source: Oxford Part A paper A1, A15294W1, 14 June 2023; parent PDF pages 276–279, paper pages 1–4. These original solutions cover all three questions and every subpart without reproducing the question statements. In Question 2(b), the prescribed data are incompatible at two points; the solutions on the compatible open arcs are given explicitly.
Fix any and compare with . The quotient required in a global Lipschitz condition in the dependent variable isConsequently,It is nevertheless locally Lipschitz in : for ,Thus the Picard-Lindelöf theorem gives local existence and uniqueness for the initial value problem; the remaining work establishes existence on the entire half-line for the specified small data.
Write . Multiplying the ordinary differential equation by the integrating factor and using the product rule givesIntegration from to therefore yields the Volterra integral equationConversely, a continuous function satisfying this integral equation becomes continuously differentiable after multiplication by , by the fundamental theorem of calculus, and satisfies the original initial value problem.
For , the coefficient bound gives . Thus for the positive kernel satisfiesThe starting Picard iterate is continuous and has supremum norm . If the th Picard iterate is bounded and continuous, its integral defines another continuous function, andTaking the supremum norm and applying mathematical induction proves boundedness of every iterate and
Put and . Initially . If , the preceding supremum norm estimate givesHence mathematical induction gives
The difference of two successive Picard iterates factors asThe preceding bound and the kernel estimate therefore giveMoreover . Summing the resulting geometric series, for ,Thus there is a uniform limit on , continuous by the uniform limit theorem, with . The integral passes to this limit becauseTherefore satisfies the Volterra integral equation, and hence the initial value problem. This proves global existence by Global Picard iteration with a decaying kernel. The same estimate gives the useful error boundIf , every iterate is zero and the convergence assertion is immediate.
Let be any continuous function solving the integral equation on , and retain . A first-exit argument avoids assuming in advance that its supremum norm is finite. If ever reached , continuity would give a first such time . On we would have , so the kernel estimate would implya contradiction. Therefore for every finite .
That pointwise strict inequality alone would not give a strict bound on the supremum norm. Apply the integral equation once more, now using globally:
Existence was proved by Picard iteration. If and are any two continuous solutions with the same , the previous part makes both bounded by . Subtracting their Volterra integral equations givesSince , this forces .
For , zero is a solution. On any finite interval , another continuous solution has a finite bound . Since , its integral equation impliesThe Gronwall inequality gives on every such interval. Hence
An equilibrium point of an autonomous planar system is a point where its vector field vanishes:For a locally well-posed ordinary differential equation, Lyapunov stability means that every prescribed neighbourhood can be protected by choosing a sufficiently small initial neighbourhood. More precisely, for every there exists such that every trajectory starting with exists for all and satisfiesThe number may depend on but not on the particular starting point. Asymptotic stability additionally requires convergence to the equilibrium point for all sufficiently close starting points.
At an equilibrium point, and , so . With , the two equilibrium points and their Jacobian matrix areAt , . The trace-determinant stability criterion therefore gives an unstable saddle equilibrium. At the origin, the eigenvalues are : its linearization is a center equilibrium. The linearization stability theorem does not classify this nonhyperbolic equilibrium of the nonlinear system.
Nonlinear classification. In fact the answer depends on :Here is an explicit derivation, rather than an inference from the imaginary eigenvalues. When , set . Near the origin , and the first integralhasIts Hessian matrix at the origin is the identity. Small level curves are closed ovals on which the vector field is nonzero, proving the center equilibrium classification and Lyapunov stability.
For , a higher-order Lyapunov function calculation settles the issue. Put , , , , and . ThenWrite and introduce the differential operatorsSuccessively cancel the terms of degrees three, four and five in the derivative of , using these homogeneous polynomials:Direct differentiation verifies , and . The remaining degree-six term has circular averageFor example, the only nonzero averages of degree-six monomials needed here are and . Since in polar coordinates, the zero-average part can be cancelled by a degree-six homogeneous polynomial satisfyingIndeed its restriction to the unit circle is obtained by integrating a zero-average trigonometric polynomial; its Fourier modes have orders , so multiplication by gives a polynomial. Consequently the positive Lyapunov function satisfiesFor this is strictly negative near the origin, giving asymptotic stability. For it is strictly positive, and in a sufficiently small neighbourhood; every nonzero starting point must eventually leave that neighbourhood. Finally , so the nearby trajectories rotate: these are weak foci, with the stability stated above. Merely calling the nonlinear origin a center for every would miss this distinction.
A characteristic curve in follows the vector field defining the first-order partial differential equation. Along such a curve the chain rule turns the equation intoIts characteristic projection is the curve in the independent-variable plane.
Writing , , , separation of variables givesThese formulas hold on the maximal interval through where the denominators remain nonzero, using the real cube root. They include (a stationary characteristic projection) and (the zero height). For , the last formula follows from . The alternative zero solution must be retained when deriving this by division by .
Parametrize the data by . The determinant testing Noncharacteristic Cauchy data isThus the open upper and lower semicircles are noncharacteristic, but the entire circle is not a valid noncharacteristic data curve: the determinant vanishes at and .
There is a stronger obstruction at those two points. On , the differential equation forces , and hence . This contradicts the prescribed value at both endpoints. ThereforeThe obstruction is already present if the equation is imposed next to the circle and the solution and its first partial derivatives extend continuously to it.
Away from the endpoints, the characteristic projections are radial half-lines:For , increases with ; for , decreases with . Each projection meets its own open semicircle exactly once and never crosses . The endpoint projections themselves are single stationary points, although their lifted characteristic curves have varying height.
Use the compatible open semicircles and set . The characteristic curve through hasThe condition is essential: at there is finite-time blowup, so the opposite branch cannot be reached from the data. From and ,Eliminating yieldsThe ratio inside the cube root is positive precisely on the two data-determined regionsOn each point traces to the upper semicircle, and on to the lower semicircle, with . To check the parameter ranges explicitly, for they are , whereas for they are . At the latter lower endpoint the planar projection escapes to infinity. The inverse function theorem and uniqueness for the characteristic ordinary differential equations give a unique smooth solution on each region. Equivalently, each point has the unique foot and parameter .
A direct check is particularly short. For , let . Then , , andSince , the displayed formula solves the partial differential equation, and gives on both open semicircles. The finite boundary where , away from the axis, is the parabola and corresponds to blowup. Points on cannot be added to a classical continuation of these regions: where they are approached from a data-determined region, the height behaves like a nonzero multiple of , or has incompatible limits at the endpoints. The formula is therefore the complete classical answer for the compatible arcs, while the full-circle problem as printed has no classical solution.
Let on the unit disk over . Smoothness is understood to include continuity on the closed cylinder. If exceeded its nonnegative parabolic boundary maximum , it would attain a positive global maximum at some spatial interior point at time . There,At the last inequality uses the derivative from the past; at an interior time it is equality. These signs imply , contradicting the given differential inequality. ThusIf , equality at any point of gives the same contradiction with , so throughout . If , equality is possible: is an example. More precisely, write the inequality as with . The strong parabolic maximum principle shows that an interior zero at time forces on .
That conclusion need not extend into the future for a subsolution. For , take a spatially constant function which is zero for and equals for . It is smooth, nonincreasing and nonpositive, so , but it becomes negative after .
With zero drift, choose the smooth functionIt equals on the entire parabolic boundary, so . On the closed cylinder, , whileConsequentlyNevertheless the maximum at isThe negative cubic term permits an interior increase while the boundary stays fixed, explaining why the sign condition in the preceding part matters.
The parabolic boundary values are zero. An exact solution satisfies the preceding differential inequality, so its maximum estimate with gives . The function satisfies the same equation because both the linear differential operator and the cubic term change sign. Applying the same maximum principle to gives . Hence the complete solution set isSubstitution verifies existence, and the two inequalities prove uniqueness among the assumed smooth solutions for every continuous choice of the drift coefficients.
Define the squared L2 norm . Multiplication of the semilinear partial differential equation by , followed by integration by parts, givesAt the Dirichlet boundary condition makes the boundary term zero. At the Robin boundary condition is , so subtraction of the lower endpoint gives . In particular the sign is dissipative. Thus the exact energy identity iswhich implies
For every real and integer , givesThis estimate covers both even and odd , without any assumption on the sign of . Since , the energy estimate from part (i) becomesEquivalently, an integrating factor givesThe bracket is nonnegative and starts at zero, so it vanishes identically. This is also the zero-data case of the Gronwall inequality. The vanishing L2 norm and continuity of imply
Source: Oxford Part A paper A1, A15294W1, Differential Equations, 22 June 2021; bundle pages 268–271, paper pages 1–4. All three questions, both proof options in Question 2(a), and every subpart are solved below.
The method of characteristics replaces the first-order partial differential equation by the ordinary differential equationsAn integrating factor for the second equation gives , so their general solution of a differential equation isHere are real constants. For , eliminating gives the characteristic projectionseach restricted to either or . These are arcs of parabolas, with the straight-line exception . Along an oriented characteristic curve, increases with .
For , the characteristic projections lie on : describes either vertical half-line when . For the projection is the single point , although still changes. This last lifted characteristic curve cannot be contained in the function graph of a classical solution: at the original partial differential equation would require .
Parametrize the initial curve by , . Its tangent is , whereas the projected characteristic vector field there is . The determinantproves that these are Noncharacteristic Cauchy data: the initial curve is everywhere transverse to the characteristic curves.
There is a regularity qualification. The prescribed function is continuous and Lipschitz continuous, but is not differentiable at . Thus the data are Cauchy in this geometric sense, with data given by a smooth function on each of and ; the usual theorem giving a global classical solution from continuously differentiable data does not apply across .
Use the initial conditions , , in the characteristic equations for a transport equation. The resulting parametrized solution surface isThe Jacobian determinant of is . In fact the inverse is explicit:Consequently the explicit solution of a differential equation on the region reached from the data isTo verify it away from , set . Direct differentiation gives and . At we have , giving precisely the prescribed boundary condition.
Across the formula remains continuous and locally Lipschitz, is a smooth function on each side, and solves the partial differential equation along every characteristic curve. It is also a weak solution, since its first distributional derivatives agree almost everywhere with its ordinary derivatives. It is not a classical solution throughout the region because of the inherited corner.
Every point with has exactly one backward characteristic curve meeting , at the point . It meets the specified data precisely when . Thus the whole region determined by these data, including the two bounding characteristic curves, isIts interior is the corresponding open domain for the partial differential equation. Uniqueness here means uniqueness in the class of continuous functions satisfying the characteristic equations for a transport equation, including the piecewise smooth function defining the solution of a differential equation above. The endpoints of the initial segment determine the two boundary values by continuity.
This region is maximal for determination by the given data: on , arbitrary extensions of outside give different values on the characteristic curves with . No characteristic curve from reaches .
For ,The lower boundary is a straight line, the upper boundary is a parabola, and the characteristic carrying the corner is . All three approach the excluded origin as .
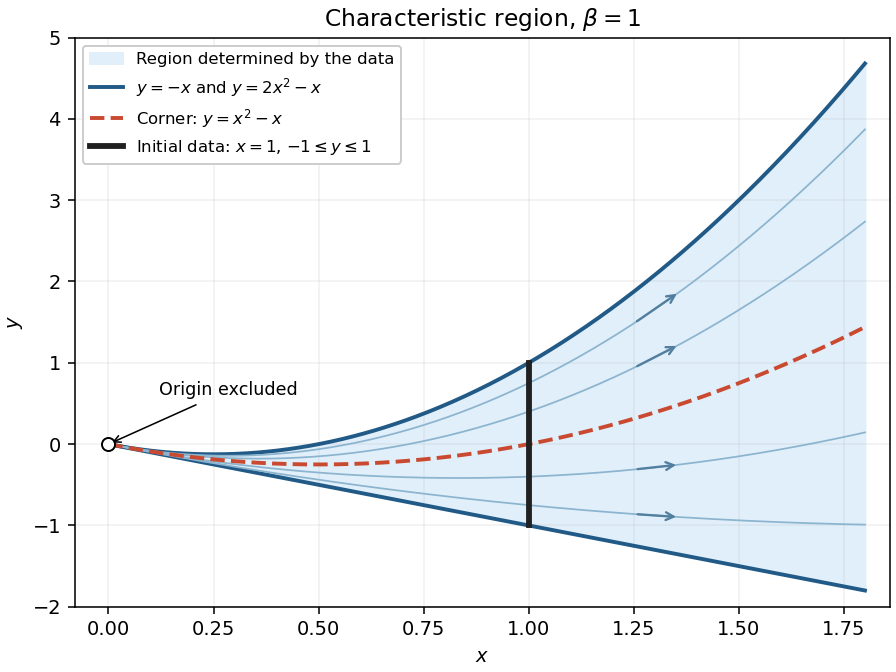

For , . On the two sides of the corner-carrying characteristic curve, the partial derivative isAt every point with , the two one-sided partial derivatives are and . Therefore does not exist on this curve; its piecewise values have a jump discontinuity of magnitude . There are no other interior discontinuities. The values on the outer boundaries are interpreted from within .
This is exactly propagation of a derivative jump along a characteristic. Already on , the data have slopes and on the two sides of . The transport equation transports this corner along the characteristic curve from , which is ; it provides no smoothing. This is consistent with Noncharacteristic Cauchy data and does not contradict the smooth-data theorem, whose differentiability hypothesis fails here.
In the convention , the coefficients of the principal symbol areThus the second-order partial differential equation isThere is no region of elliptic partial differential equation type. The terms hyperbolic, parabolic and elliptic refer to the pointwise classification of a second-order partial differential equation. At every second-order coefficient vanishes, so the principal symbol has rank zero and the equation is degenerate rather than genuinely parabolic there. Moreover the right side is , so no twice continuously differentiable classical solution can satisfy the equation at the origin.
For , the equation for the characteristic curves isThe two families are therefore and the characteristic projections from part (a), , together with the vertical characteristic . On either region or , the hyperbolic partial differential equation admits the characteristic coordinatesIndeed is constant along the first family, while . Their Jacobian determinant isThe coefficients of the two pure second partial derivatives in these coordinates vanish, and the coefficient of the mixed partial derivative is . Hence they give the hyperbolic characteristic normal form. They also remain regular at , provided .
The alternative , is valid on patches with . On , it is a parabolic partial differential equation away from the fully degenerate origin, so two independent hyperbolic characteristic coordinates are unavailable.
The second-order differential operator factors asTherefore setting turns the second-order partial differential equation into exactly the first-order partial differential equation in part (a). Conversely, given a sufficiently smooth solution of a differential equation of that equation on a coordinate rectangle, defineThe fundamental theorem of calculus gives , so this solves the second-order equation, with an arbitrary twice continuously differentiable function . This classical correspondence is local on smooth patches; for the cornered solution of part (b), it can instead be interpreted using distributional derivatives.
For the Weierstrass M-test proof of the Picard-Lindelöf theorem, the required bound isTo see this, use Picard iteration starting with andIf takes its values in , then . Thus every Picard iterate remains in the rectangle where the hypotheses hold. Successive applications of the Lipschitz condition and integration give the factorial estimate for Picard iterationFor example, the estimate is , and integrating the th estimate multiplied by proves the next one. The sum of the uniform bounds isfor every finite , by the exponential series. Hence the telescoping series of Picard iterates converges uniformly by the Weierstrass M-test. The uniform limit stays in the closed rectangle, and the Lipschitz condition permits passage to the limit in the integral equation. The fundamental theorem of calculus then gives the desired solution of a differential equation on .
For the direct contraction mapping theorem proof with the usual supremum norm, take the complete metric spaceand the Picard iteration map . The estimates areThus this proof requiresThe first inequality makes preserve ; the strict second inequality makes it a contraction mapping. Its unique fixed point is the desired solution of a differential equation.
This is more restrictive than the preceding Weierstrass M-test argument: a single application of must shrink every difference in the supremum norm, whereas repeated integration in the other proof produces the factorial and convergence even when . If , the additional condition is automatic. These are conditions for the two stated direct proofs; they are not necessary bounds on the actual existence interval.
With the standard constant starting Picard iterate, , the next two Picard iterates areand, for ,ThusThe restriction for is essential for the integral from to : the preceding iterate vanishes at , where the new integrand is undefined.
The rectangle avoids the singular line exactly when . There , and the largest on is . Since decreases with , the smallest feasible uniform bound isIt is attained at , . For the Lipschitz constant, the mean value theorem givesThe quotients approach this upper bound as and , so the smallest feasible constant isSubstitution into part (a) givesThe contraction mapping restriction is automatic for every M-test-admissible precisely when . Because ,Thereforeis exactly the range where the two proofs guarantee all the same closed symmetric intervals, including the largest M-test interval.
For completeness, set and . The M-test allows ; the contraction mapping theorem allows with . At , these have the same supremum , but contraction excludes the endpoint . For , it gives the strictly shorter range . For a particular , both proofs work exactly when both displayed inequalities hold, even for these larger .
Near the solution of a differential equation has , so the separable differential equation givesEquivalently its trajectory lies on the level setOn , the function is strictly increasing because , and its range is . Thus the positive branch exists exactly whereThe connected component containing isThe implicit function theorem gives a smooth solution of a differential equation at every such . It remains finite at every finite , because increases without bound. As , we have , and the original right side becomes singular. Hence this is the maximal interval through the prescribed initial condition.
In particular, the solution is not defined for all . It cannot pass through as a classical solution, since its required value there is .
Treat both sides of at once: for set , . Nonnegativity givesDefine . By the fundamental theorem of calculus, and . The integrating factor givesSince , this proves the affine Gronwall estimate
Continuous dependence of an ODE solution on parameters here means continuity of the map into with its supremum norm: for every and , all sufficiently close satisfySubtract the two integral equations and use the uniform Lipschitz constant on the rectangle. With we obtainPart (i), with and , therefore proves, for ,The case follows from uniqueness or the same estimate with zero forcing. If , the direct integral estimate gives . In either case the map is even Lipschitz continuous, and hence continuous, throughout in the stated supremum norm.
The equilibrium points satisfy and , so they areThe Jacobian matrix and its eigenvalue equation areAt the eigenvalues are , so both points are saddle equilibria. Their stable and unstable tangent directions have slopes and , respectively.
At the eigenvalues are , giving a centre for the linearized equation. Purely imaginary eigenvalues alone do not classify the nonlinear system. The first integral established in part (ii) proves that is in fact a centre equilibrium. It is clockwise: immediately to its right, with and , the vector field points downwards. Thus the final nonlinear classification is
Where , taking the quotient of the two ordinary differential equations givesChoose the first integralThe chain rule checks conservation even at points excluded in taking that quotient:Thus each trajectory is contained in a connected component of a level set of . At the gradient vanishes and the Hessian matrix is the identity, so has a strict local minimum there. To make the closed-trajectory argument explicit, put and . The bounded component of isThe two arcs join at to form a simple closed curve that is a regular level set. The gradient cannot vanish on it: the only critical point of a dynamical system in is the centre, whose level is .
The vector field is tangent and nowhere zero on this compact set, so its speed has a positive minimum. It therefore traverses the curve in finite time and returns to its initial point, giving a periodic orbit. These ovals shrink to the centre as . This is the planar first integral criterion for a centre and proves the required nonlinear assertion; it also gives Lyapunov stability without asymptotic stability.
The nullclines areOn , away from the equilibrium points, the vector field is vertical. Its crossing direction is downwards for , upwards for , downwards for , and upwards for , because . On each of , the vector field is horizontal: it points right when and left when .
Throughout each complementary region, has the sign of , and has the four signs just listed. These signs orient the level sets from part (ii). In particular, the inner periodic orbits are clockwise. The saddle level is , whose separatrices satisfyFor , the upper arc goes from to ; the lower arc goes back from to . These two heteroclinic orbits form a closed boundary around the family of periodic orbits. The remaining branches of the same saddle level extend outwards. The sketch shows the surrounding nonclosed trajectories as well as the nullclines and equilibrium points.
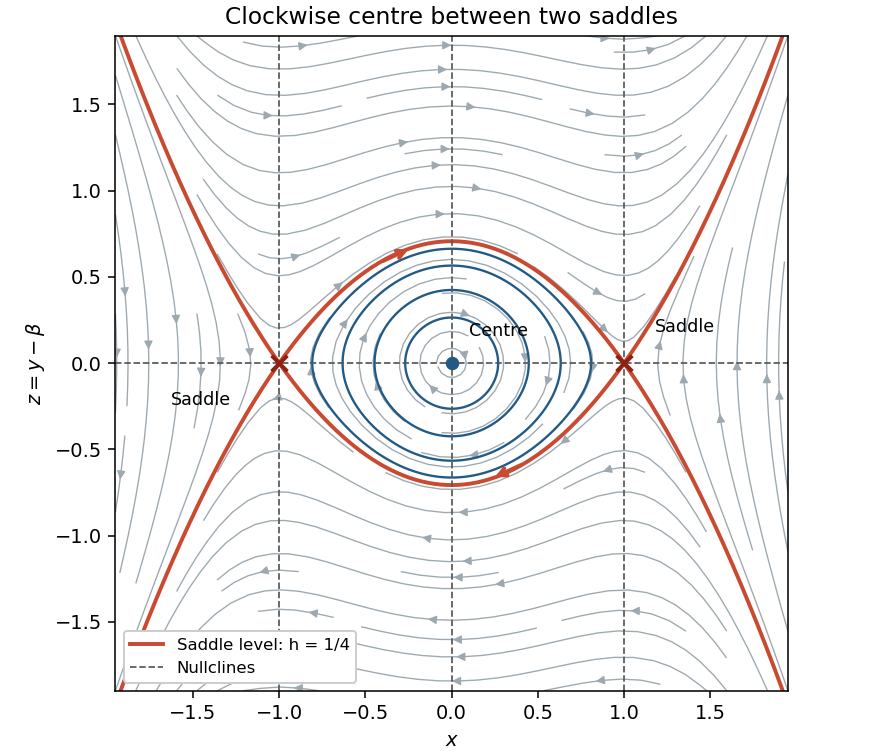
The phase plane in coordinates x and y minus beta, showing clockwise periodic orbits and saddle connections
. Details. 
Set . Then the autonomous planar system becomeswhich has no dependence. ThereforeMore precisely, replacing by sends every trajectory to , with the same time parametrization. The equilibrium points, nullclines, periodic orbits and separatrices all undergo this same translation. Their types and orientations are independent of , so varying produces no bifurcation.
Using , in the original autonomous planar system givesThe map is a rotation by , preserving time and the clockwise or counterclockwise orientation of trajectories. Hence the given centre equilibrium at becomes a clockwise centre at , and the given saddle equilibrium at becomes a saddle at . These are the only equilibrium points, because rotation is invertible.
Applying time reversal of an autonomous differential equation to the system from part (i), and renaming its coordinates , givesThe equilibrium points remain and . Time reversal of an autonomous differential equation preserves a saddle equilibrium, interchanging its stable and unstable directions; it also reverses the direction around a centre equilibrium. Therefore this system has precisely the required counterclockwise centre at and saddle at .
Articles were limited to the first 100 out of 1694 total.
Articles by others on the same topic
Year 2 of the mathematics course of the University of Oxford by  Ciro Santilli 40 Updated 2025-07-16