
Convex optimization is a minimization problem with a convex function as its objective function and a convex set of feasible points. For a finite-valued , the problem is to find with for every . The displayed infimum describes its value even when no minimizing point exists. The two convexity requirements concern different objects: the allowed decisions and the scores assigned to them.
A convex set contains the whole line segment between any two of its points:A convex function lies below the interpolation of its endpoint values:Thus mixing two allowed decisions preserves feasibility, and the mixed score is no worse than the same mixture of endpoint scores. The objective function may have flat regions or corners. For a strictly convex function, the second inequality is strict when and .
A useful constraint representation iswhere are convex functions on a common convex set , and the equalities are affine functions. Each inequality defines a convex sublevel set; their intersection with and the equality set is a convex set. An equality involving a general convex function need not preserve this geometry: allows and but excludes their midpoint . See Boyd and Vandenberghe, Convex Optimization (2004), §4.2.1 for the standard problem form.
Why local information can certify a global answer. Every local minimum of a convex optimization problem is a global minimum, including minima on the boundary. If a feasible point had , points would remain feasible and have value strictly below for every . Taking arbitrarily small contradicts a local minimum at . This argument explains the special power of convexity: a better distant decision would reveal an improving direction immediately nearby.
If a minimizer exists and the objective function is strictly convex on , it is unique. Two distinct minimizers of value would have a feasible midpoint with value strictly below . Existence is a separate question: the exponential function is strictly convex on , but its infimum is approached only as . Even a bounded convex set need not suffice: on also has unattained infimum . A continuous function on a nonempty compact set attains its minimum by the extreme value theorem.
Nor does strict convexity imply differentiability. For , the squared term gives the strict inequality while the triangle inequality gives the weak inequality for the absolute value. At zero the left and right derivatives are and , so no derivative exists there, although zero is the unique minimizer. Such objectives require subgradients or proximal operators rather than an ordinary gradient at every point.
For a differentiable convex function on an open convex set containing , the constrained first-order condition isIndeed, the subgradient inequality makes this sufficient; taking the one-sided derivative along feasible line segments makes it necessary. At an interior minimizer, both directions are feasible and the gradient must vanish. At a boundary minimizer it can be nonzero: it only needs to make every feasible direction nondecreasing. See Boyd and Vandenberghe, §§3.1.3 and 4.2.3.
A fully computed nearest-point problem. Project onto the half-space by minimizing half the squared Euclidean distance:The Hessian matrix is the identity matrix, so the objective function is strictly convex. The unconstrained minimizer violates the inequality. With the convention , the optimization Lagrangian is , where the Lagrange multiplier satisfies . Its Karush-Kuhn-Tucker conditions areThe last two equations give , . The choice is infeasible, so complementary slackness forces . Consequently , giving , and . The Euclidean distance is , rather than the objective function value . The gradient at the answer balances ; the displacement from to is a normal vector to the boundary.
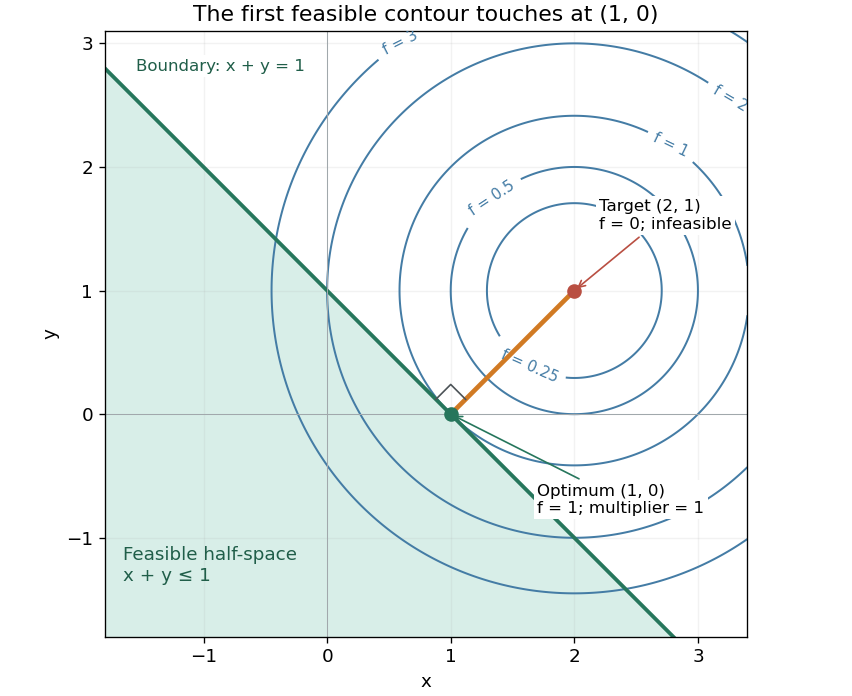

There is an exact certificate independent of numerical search. Completing squares givesFor every feasible point, implies . Thus every feasible objective is at least , and attains this bound. More generally the Lagrangian dual problem has objective for . Its maximum is also , illustrating strong duality through matching computed bounds. This makes the example a model for Euclidean projection onto a convex set and the projection step in projected gradient descent.
What the multiplier conditions require. For differentiable convex functions on an open convex set and equalities defined by affine functions, the KKT conditions combine feasibility, , complementary slackness , and stationaritywith unrestricted equality Lagrange multipliers . They suffice to certify a global minimum without an additional regularity assumption: the optimization Lagrangian is convex, stationarity minimizes it, and feasibility with complementary slackness gives the same certificate as above. To guarantee their necessity at an attained finite optimum, a regularity hypothesis suffices: Slater's condition requires some with and . The projection example has the strictly feasible point . See Boyd and Vandenberghe, §§5.2.3 and 5.5.3. This hypothesis guarantees suitable multipliers, not existence of a primal minimizer.
Without regularity, necessity can fail even for convex functions: minimize subject to . The sole feasible point is optimal, but stationarity would require . No Lagrange multiplier works. There is no strictly feasible point, and the gradient of the constraint vanishes at the answer.
The nonconvex contrast. The polynomial has derivative and second derivative . Numerically solving the cubic gives stationary points , , and . Their objective values are respectively , , and , with second derivatives , , and . Hence both outer points are local minima, and the middle point is a local maximum. Since at both ends, its global minimum exists and must be one of the stationary minima: it is the left one. A method stopping at the right local minimum misses a better value by approximately .
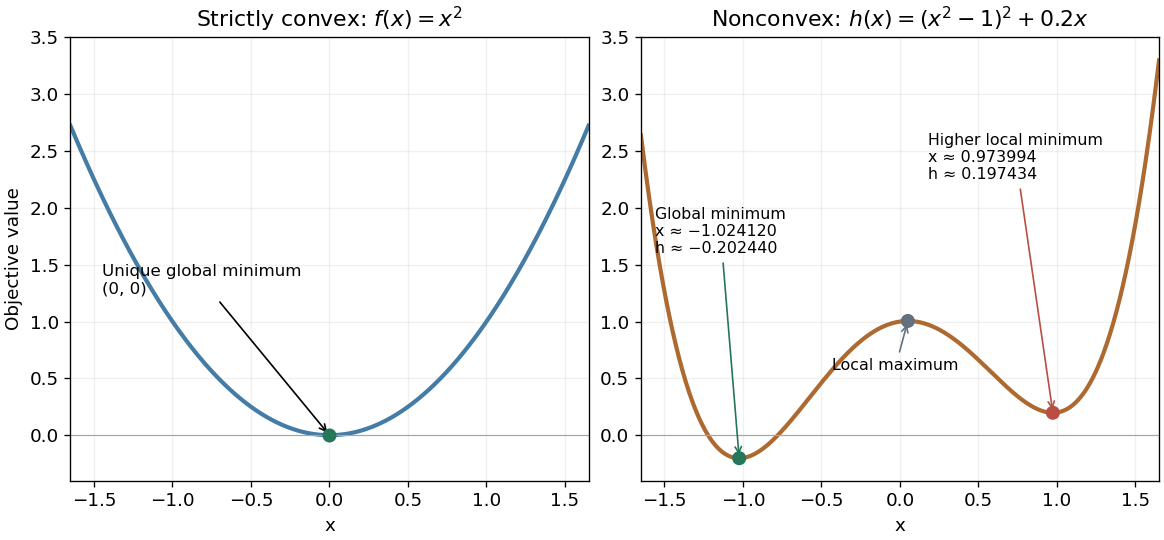
A strictly convex quadratic has one minimum; a tilted quartic has two local minima with different values
. Details. 
The practical appeal of convex optimization is the ability to check an answer globally using geometry and matching Lagrangian duality bounds. The projection certificate certifies every feasible alternative at once; the tilted quartic shows why a zero gradient alone cannot do that for general nonlinear optimization.
Historically, an early landmark is Kuhn and Tucker's [ref]
https://digicoll.lib.berkeley.edu/record/112776/files/math_s2_article-35.pdf. Nonlinear Programming, Second Berkeley Symposium (1951), pp. 481–492
. Its §3 explicitly states a regularity hypothesis for inequality-constrained Lagrange multipliers; its discussion of saddle points explains how concave functions support global conclusions for maximization. This documents an early formulation of the multiplier approach; it does not establish sole discovery of today's KKT conditions or of convex optimization as a whole. New to topics? Read the docs here!