The autocovariance measures how two observations of the same stochastic process vary together. For a real weakly stationary process of mean , it isWeak stationarity removes dependence on the absolute time . Without it, the covariance function generally needs two time arguments. Lag zero is the variance, ; symmetry of real covariance gives . Positive values favor deviations from the mean in the same direction; negative values favor opposite directions. The units are the square of the observation units. See Bartlett, lecture 2: autocovariance examples.
For example, if with centered unit-variance white noise, expanding the product leaves only matching noise times. Thus , , and for . This MA(1) has a positive lag-one autocovariance because adjacent observations share one disturbance. Rescaling every observation by multiplies every autocovariance by , while leaving autocorrelation unchanged.
The autocovariance is useful beyond comparing pairs: it determines the variance of any finite linear combination of observations. For the sample mean ,Each separation occurs in pairs. For the preceding MA(1) and , this is , compared with for four uncorrelated random variables of the same variance. This is the finite-record counterpart of the long-run variance of a stationary process.
For a known zero mean, for . Weakly stationary process assumptions give expectation . Dividing by instead gives an unbiased estimate at each individual lag, although the resulting collection need not form a positive semidefinite covariance sequence.
The autocorrelation function of a real weakly stationary process with positive variance is its normalized autocovariance:It is dimensionless, with , , and by the Cauchy-Schwarz inequality. It is unchanged by replacing with for fixed . This makes autocorrelation useful when comparing records measured on different scales. The ACF is a property of the model; the sample autocorrelation function estimates it and will generally not reproduce theoretical zeros exactly.
An AR(1) with coefficient has autocorrelations at lags one through three. With these become : the same diminishing magnitude, alternating in sign. An MA(1) with instead has lag-one autocorrelation and zero at every higher lag. Equal numerical coefficients in an autoregressive model and a moving-average model do not mean equal dependence. See Bartlett, lecture 3: theoretical ACFs and prediction.
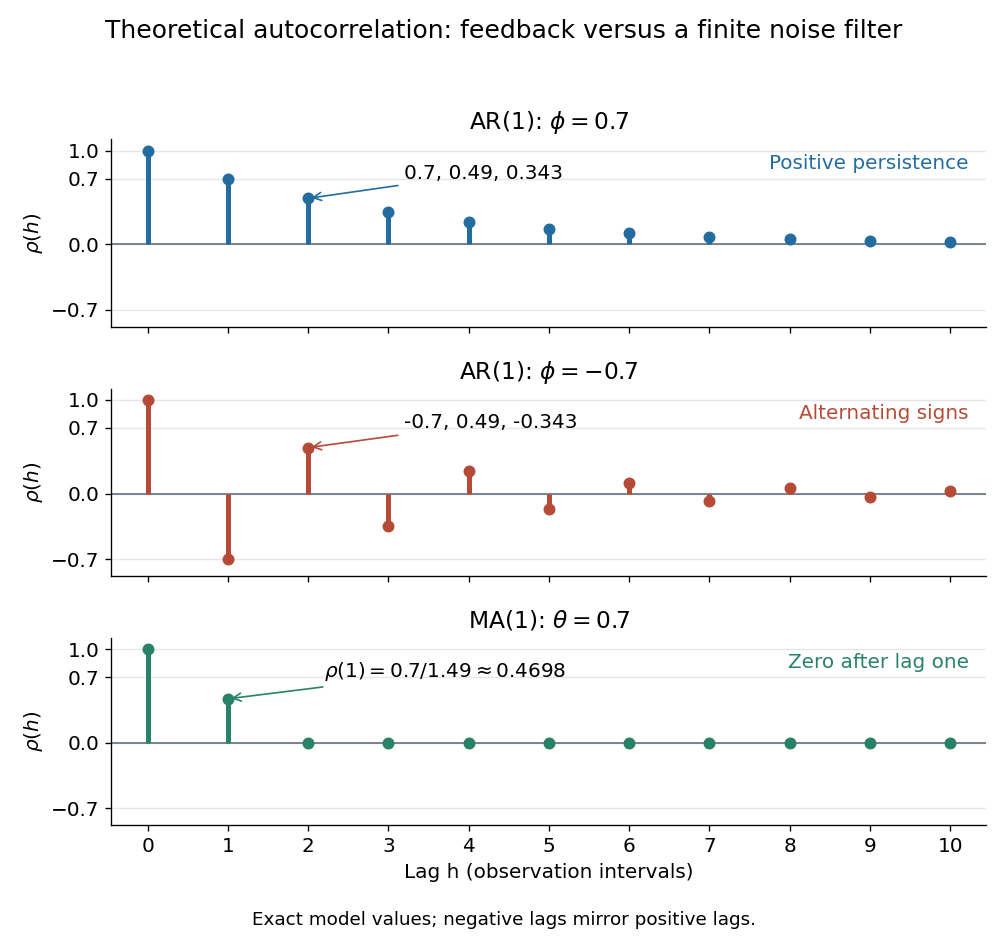
Theoretical autocorrelation: AR(1) with coefficients 0.7 and -0.7, compared with MA(1) with coefficient 0.7
. Details. 
The bars show exact model autocorrelations, not estimates from the illustrated sample paths in time series. The AR(1) retains a diminishing trace of a disturbance at arbitrarily large lags; the MA(1) stops sharing driving noise after lag one. A zero autocorrelation means uncorrelated random variables, and does not generally imply independent random variables. For a Gaussian process it does imply independence of the two coordinates.
There is a direct prediction interpretation. Among affine predictions based on just , the best linear predictor of is , with mean squared prediction error . Thus negative autocorrelation is also useful predictive information. A prediction using the whole observed past can do better; best linear prediction from a finite past describes that problem. Interpreting the affine prediction as a conditional expectation requires additional assumptions, such as a joint normal distribution.
A correlation time measures how rapidly a stationary stochastic process loses temporal dependence. Specify whether it means an exponential decay time, an integral of the normalized autocorrelation, or another width. For , the exponential time and the one-sided integral both equal .
The partial autocorrelation at lag is the correlation of and after their linear projections onto the intervening observations are removed. A causal autoregressive model of order has zero partial correlations after lag . This complements the finite cutoff of the autocorrelation function for a moving-average model.
Replace the autocovariance in the finite-lag linear prediction equations by the sample autocovariance function. The last regression coefficient at order estimates the lag- partial autocorrelation function.
The sample autocorrelation function replaces the mean and lagged covariance in by their empirical counterparts.
A correlogram plots the estimated autocorrelation function against lag. The plot helps distinguish the finite autocorrelation cutoff of a moving-average model from the decaying dependence of a causal autoregressive model. Estimated cutoffs are diagnostics, not exact finite-sample identities.
Articles by others on the same topic
There are currently no matching articles.