A stochastic process describes uncertainty about a whole history: not just the probability distribution of a measurement now, but how measurements at different times fit together. It is a family of random variables on one probability space, with index set . Time is the usual index: for successive observations or for continuous time. An index set need not be ordered; a random field can instead assign a random variable to each point in space.
There are two complementary views. Fix a time and is a random variable; fix a sample space outcome and is one sample path. A model specifies the probability distribution of these histories. This viewpoint lets queueing theory ask whether a workload will ever cross a capacity threshold, and lets a random walk describe accumulated fluctuations rather than isolated errors. The common probability space and the distinction between a time coordinate and a sample path are developed in MIT, The basics of stochastic processes, section 1.
A concrete construction starts with a Bernoulli process of independent fair bits . Keeping records the next trial; adding the signs gives a simple random walk on the integer line, and . Every increment of this random walk is , yet the positions are dependent: contains all the previous increments. Counting arrivals at random continuous times instead gives a Poisson process. These examples separate three questions: what values are possible, how time is indexed, and how the values depend on one another.
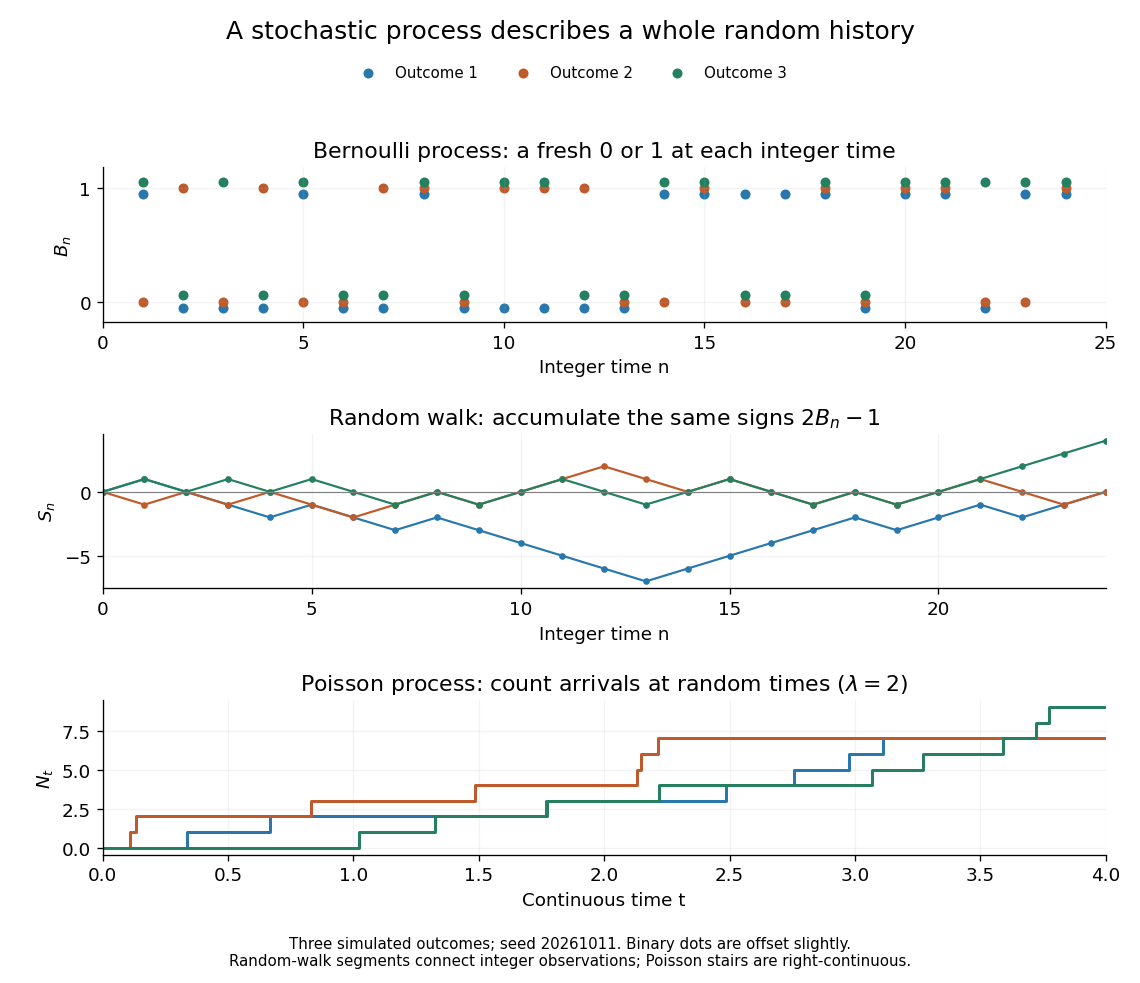
For the fair simple random walk on the integer line, the expected value is and the variance is . At time four, returning to zero requires exactly two positive steps, so . A rate-two Poisson process instead has . A single realized sample path does not establish either probability: they follow from the specified joint probability distributions.
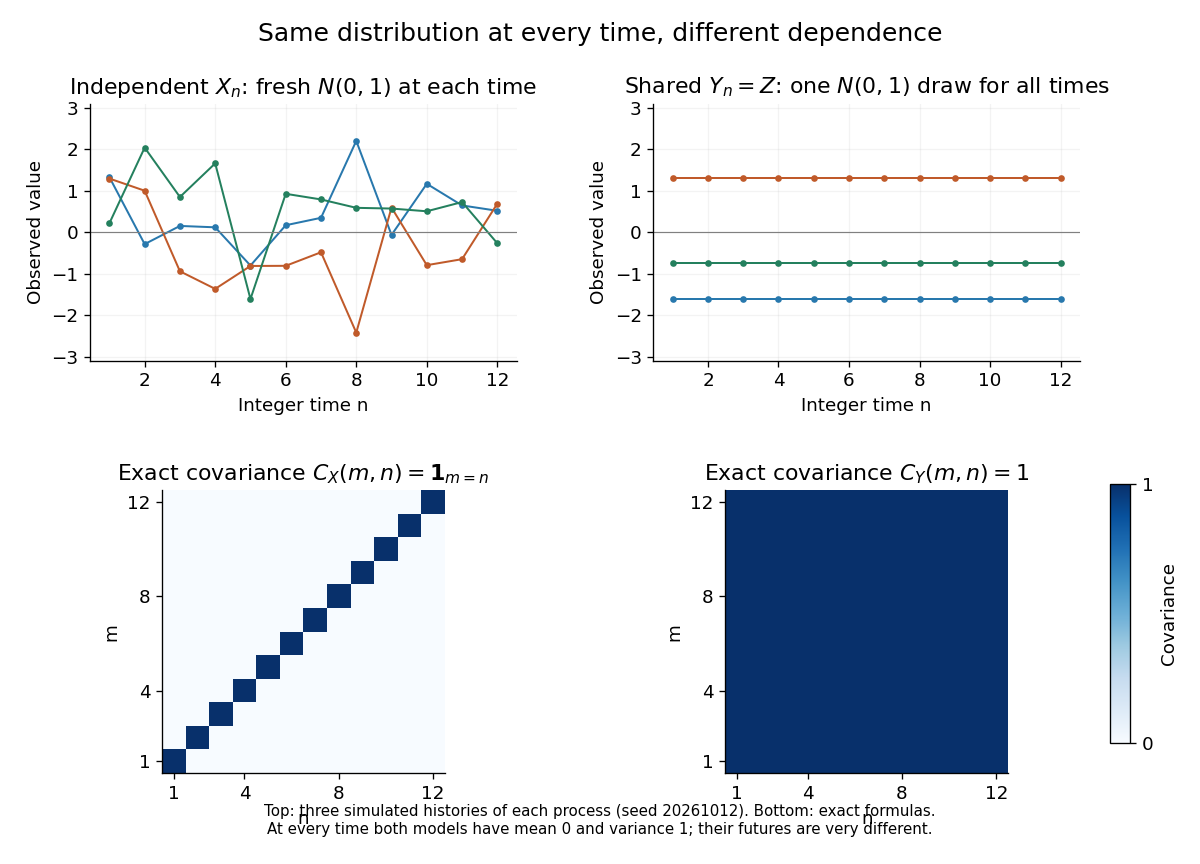
The most revealing feature is often dependence. Two stochastic processes can have identical marginal distributions at every time while one forgets everything at the next step and the other repeats its first value forever. Their finite-dimensional distributions and covariance functions distinguish them. That extra structure is what makes a stochastic process useful for prediction.
Begin with positive counts of two colours. At each step select one ball uniformly and replace it together with one new ball of its colour. If the total initial count is , the blue proportion satisfies , where the next blue indicator has conditional mean . Thus is a bounded martingale and converges almost surely and in to a random proportion. If uniforms generate the draws, the update from time to must use the fresh relative to .
Both colour counts tend to infinity almost surely. For example, , and independent events occur infinitely often by the Borel-Cantelli second lemma, forcing infinitely many blue additions.
The martingale increment formula gives . Conditional orthogonality of later increments and implyOn the squared difference is , so its conditional probability is at most . Dominated convergence proves zero probability of that endpoint. The symmetric argument for red excludes . No explicit beta law is needed for this proof.
A multiscale method for bounding the supremum of a stochastic process. Approximate each index by points in successively finer metric nets, expand its difference from an anchor as a telescoping sum, and bound the largest increment at each scale. For a finite index set the finest net can be the entire set, making this decomposition exact. If is the set of approximation edges, then pointwise . Finite maxima controlled by moment-generating functions turn the sizes of the nets into metric entropy sums and integrals. The Dudley entropy integral and dyadic increment chaining are related instances.
Mean reversion is a tendency for a stochastic process to move back towards a reference level. For an Ornstein-Uhlenbeck process, the conditional expected value of a future deviation is the present deviation multiplied by after time . Individual sample paths can move away from that level: mean reversion describes a conditional tendency, not monotone motion or a guaranteed return by a deadline. It also does not by itself imply a stationary process; the initial probability distribution matters.
A Bernoulli process is a sequence of independent and identically distributed random variables with a Bernoulli distribution: and . It models repeated Bernoulli trials with a fixed success probability and no dependence between trials. The count has a binomial distribution, expected value , and variance ; the first success time has a geometric distribution on . The observations and the accumulated count are different stochastic processes: the observations are independent, while consecutive counts share all earlier observations. [ref]
Find a constrained path and a boundary regulator which together modify a given driving path. In the half-line case, write , require and nondecreasing, and require its increases to occur only where . For multidimensional orthants the regulator acts through a specified reflection matrix. The Skorokhod reflection map on the half-line solves the one-dimensional continuous-path case explicitly.
For a continuous driving path with , the running supremum supplies the minimal nondecreasing regulator keeping the path nonnegative. It increases only at a new negative running minimum, where the reflected path is zero. Any regulator satisfying the Skorokhod problem constraints must coincide with it. On a finite time interval, , so the map is continuous and transfers a functional central limit theorem to reflected workloads.
A process is self-similar with exponent if and have the same finite-dimensional distributions for every , or the same path law when the process is considered as a random path. Fractional Brownian motion has this property with its Hurst exponent. It converts dilation of time to deterministic scaling of amplitude: . Consequently a small-noise large deviation principle with inverse-variance speed produces the large-deviation speed for those rescaled paths.
A random field is a family of random variables indexed by points of a spatial domain, or more generally by a multi-dimensional parameter set. Its componentwise covariance function and spectral tensor describe second-order dependence. A Gaussian random field has jointly Gaussian finite-dimensional distributions; a general random field need not be Gaussian.
A process is locally bounded if there are stopping times and finite deterministic constants bounding it on the stopped intervals. A locally bounded predictable process is integrable against a semimartingale. Continuous adapted processes are locally bounded by stopping their magnitudes and time.
// Target: probability-and-statistics.bigb
A stochastic process in which individuals independently produce offspring according to specified distributions. It models growing populations and gives an approximation to sparse percolation clusters when collisions between branches can be neglected. On a lattice, loops and overlapping branches prevent this approximation from being an exact identity.
A branching process with mean offspring number one. In a continuous-time birth–death example with equal per-cell birth and death rates , one initial individual has survival probability and mean size conditional on survival.
For equal individual birth and death rates and one initial individual, the probability generating function is . It solves with , and its geometric expansion gives the displayed probabilities. The mean remains one and the variance is , although extinction occurs with probability tending to one. The surviving fraction has conditional mean population .
A particle of type has independently a Poisson distribution of type- offspring with mean . Different particles reproduce independently. If is the probability generation is nonempty from one type- ancestor, then and , where . This iteration decreases to the survival probability of a branching process, the greatest nonnegative fixed point of . The expected type-count row vector in generation is .
This criterion holds even for reducible nonnegative matrices. If a fixed point exists, for gives on its support. Some therefore satisfies , forcing the spectral radius above one by the Perron–Frobenius theorem. Conversely take , , with and . For sufficiently small , . Thus is a subsolution; monotone iteration under gives a positive fixed point below . Strictness of excludes survival at the critical value for this Poisson offspring law.
The raw same-observable time correlation . For a stationary process, it equals . Its connected part is the autocovariance; unlike the normalized statistical autocorrelation, no division by the variance is imposed. The distinction matters for fluctuations around a nonzero equilibrium point.
Near the stable Adler phase equation point , linearized noise obeys an Ornstein-Uhlenbeck process with relaxation rate . Its harmonic-model raw correlation is . Nonlinear drift also shifts the local mean at order . This describes times after relaxation but before appreciable phase slips; it is not a stationary infinite-time correlation of the unwrapped phase at fixed nonzero noise.
For a stochastic process and a fixed sample space outcome , its sample path is the function . One row of observed fair bits, one trajectory of a random walk, or one staircase of Poisson process arrival counts is a sample path. Fixing instead gives a random variable ranging across possible histories. The same two-variable object therefore describes both observations across outcomes and evolution within an outcome.
Statements about continuous, càdlàg or Hölder continuous function sample paths concern these functions simultaneously in time. They differ from assertions made at each fixed time separately. For example, take with a uniform distribution on and set . For every fixed , almost surely, but every sample path has a single spike. Thus this process is a modification of a stochastic process that is identically zero, while the two are not indistinguishable stochastic processes. Continuity of both sets of sample paths rules out this discrepancy: equality at a countable dense set then implies equality everywhere. This is why path regularity is an additional part of constructing a continuous-time model.
A discrete-time stochastic process has bounded increments if a single deterministic satisfies almost surely for every . The constant is uniform in time and sample outcome; bounding each increment by a different constant does not suffice. This property applies to differences, so it does not require the process itself to stay bounded.
A discrete-time martingale with a common deterministic bound on all increments either converges finitely or has and , almost surely. Stopping on first crossing below gives a lower bound on the overshoot. Adding produces a nonnegative martingale, so the martingale convergence theorem forces finite convergence on the event of never crossing. Apply the same argument to .
Let , where the increments are nonconstant independent and identically distributed random variables with zero expected value and . Then the random walk oscillates between arbitrarily large positive and negative levels almost surely. For , the stopped martingale is nonnegative. The martingale convergence theorem implies that converges finitely on . However, some has , and the Borel-Cantelli lemmas imply infinitely often. Hence finite convergence is impossible. Apply this to every positive integer and to .
The bounded increments also imply infinitely many visits to : a path cannot cross from above to below without entering this interval. Identical distribution cannot simply be dropped. For independent symmetric signs , the increments satisfy for every , even though they are nonzero, independent, symmetric and uniformly bounded.
A continuous locally defined process is a pair specified on the stochastic interval , with a lifetime stopping time approached by an announcing sequence for a stopping time . Each stopped process is an ordinary continuous adapted process. This is the convention used for continuous local differential equations; no value at is required. Restricting a globally defined process gives examples, but finite lifetimes also allow approach to a domain boundary or explosion.
A local solution is a locally defined stochastic process taking values in a specified open domain and satisfying the stochastic differential equation on every stopped interval before its lifetime. For , the integral equation holds after each announcing stop, with the requisite local drift and noise integrability. A maximal local solution of a stochastic differential equation cannot be extended while remaining in ; a finite lifetime can be a boundary hit rather than divergence to infinity.
For a stopping time , the stochastic interval means the subset of sample-time space. Its endpoint varies with the sample. A locally defined stochastic process on it has no prescribed value at the endpoint. This notation is distinct from an ordinary deterministic interval.
Processes on the same probability space and index set are modifications of each other if for each fixed index . This differs from indistinguishability of stochastic processes, which requires equality at all indices on a single event of probability one. Equality at a countable dense set upgrades to indistinguishability when both processes have continuous paths.
A càdlàg modification of a stochastic process is a modification of a stochastic process whose paths are càdlàg on one event of probability one. Equality almost surely at every separately fixed time does not imply indistinguishability of stochastic processes when the original process lacks path regularity. A stochastic process starting at zero, with independent increments, stationary increments, and stochastic continuity, has a càdlàg modification and is a Lévy process under the intrinsic definition.
A continuous modification of a stochastic process is a modification of a stochastic process whose paths are continuous outside a single null event. For a process originally given only on a countable dense set, the analogous construction gives a continuous extension agreeing simultaneously at all original indices. The Kolmogorov continuity theorem and dyadic increment chaining are standard ways to obtain it.
A linear fluctuating interface smooths height gradients by diffusion and receives additive Gaussian white noise. With periodic or Neumann boundary conditions, its nonzero Fourier modes are independent Ornstein-Uhlenbeck processes if the noise is diagonal in that basis. The unconstrained uniform height is a Brownian zero mode of a fluctuating interface.
For a nonzero Fourier mode satisfying with , the explicit Ornstein-Uhlenbeck solution and Itô isometry give the stationary second moment . The prefactor depends on the normalization of the mode noise, while the inverse-square dependence follows from diffusive relaxation.
An unpinned uniform height driven by Gaussian white noise is Brownian motion. Its variance grows as and it has no stationary distribution on the real height axis for . Indeed, a stationary characteristic function would obey , incompatible with continuity at zero. Quotienting out the uniform height can still leave stationary shape fluctuations.
A path probability is a probability measure, or a density relative to a specified reference measure, on histories of a stochastic process. A formal Onsager--Machlup path probability must be interpreted with its discretization and initial-state conditioning specified; conditioning on both endpoints produces a separately normalized bridge measure.
Langevin dynamics describes a dynamical variable driven by deterministic forces and random noise. Underdamped Langevin dynamics retains inertia, whereas overdamped Langevin dynamics neglects it. At thermal equilibrium, the fluctuation-dissipation relation for a Langevin particle relates Gaussian white noise strength to drag and temperature.
A Langevin equation with a friction memory kernel, rather than only instantaneous friction. The equation couples the velocity to its earlier history through a causal convolution. Equilibrium noise and friction are related by a generalized fluctuation-dissipation relation. The name extends the Langevin equation associated with Paul Langevin.
For the equilibrium generalized Langevin equation with unit mass, the random force has zero mean and the displayed autocorrelation, where is the equilibrium velocity variance. If the deterministic relaxation is stable, and , then the stationary velocity autocorrelation function is , equivalentlyOne proof uses the power spectral density. The even force autocorrelation has spectrum . With transfer function , the velocity spectrum is , the spectrum of the even extension of . Stability removes initial transients with finite second moment. A valid force autocorrelation must have nonnegative power spectral density; an arbitrary proposed memory kernel does not automatically satisfy this condition.
Zero-mean random forces vanish in an ensemble average, while independent finite-bandwidth sample averages have variance proportional to the inverse sample count. Merely increasing detector bandwidth does not suppress physical noise; it can expose more fluctuations. Independence, filtering and averaging are separate assumptions.
For , classical equilibrium white noise satisfies . The normalization produces the equipartition velocity variance .
For a particle of mass with linear drag , the velocity relaxation time is the exponential relaxation time . Under a constant applied force and zero-mean random forcing, the averaged Langevin equation is . Solving givesThus the initial mean-velocity deviation decays by a factor after time . Since the force-per-velocity coefficient has units , has units of time. If the damping parameter is instead defined as a rate , the same time is . For a sphere obeying Stokes's law, . The fluctuation-dissipation relation for a Langevin particle gives the same decay time for its equilibrium velocity covariance.
An interacting particle system is a stochastic process whose local states evolve through random transitions whose rates depend on nearby states.
At each site, a rate-one clock rings and the site copies the state of a randomly chosen neighbor. The model is a Markov process on Ising spin configurations, interpreted through its local update infinitesimal generator. All constant configurations are absorbing state. Tracing copying arrows backwards gives the voter-model duality with coalescing random walks.
Independent Poisson process copying arrows construct the voter model. A backward ancestral line from a site follows a continuous-time random walk; lines that meet then coincide. Thus a finite collection of Ising spins at time equals initial Ising spins at the positions of coalescing random walks. In particular , and the probability of disagreement at two sites is bounded by the probability their ancestral walks have not yet coalesced.
If the initial one-spin set is finite on the square lattice, voter-model duality gives . The transition probabilities tend to zero on this infinite lattice; their Fourier transform also proves the limit of a sequence by dominated convergence. A union bound on any finite set of observation sites then proves weak convergence of probability measures to the all-zero point mass in the product topology.
In a nearest-neighbor voter model on the square lattice, any two ancestral coalescing random walks meet almost surely. For an invariant probability measure of a Markov process, the disagreement probability is constant in time but bounded by the vanishing probability of noncoalescence. Hence every pair of sites agrees almost surely. Countability concentrates the measure on the two constant configurations; both are absorbing state, so every mixture of their Dirac measures is invariant. Translation invariance need not be assumed.
Particles on a countable lattice attempt jumps at the rates , and an attempt into an occupied site is suppressed. Thus each site contains at most one particle and the number of particles is conserved when finite. Here interchanges the occupations at and . Bounded nearest-neighbour rates give a well-defined Markov process. A symmetric jump kernel gives the symmetric simple exclusion process; an unequal left-right kernel gives the asymmetric simple exclusion process.
On , put independent rate- Poisson processes on unoriented nearest-neighbour edges, and exchange their endpoint occupations at each mark. Its generator on cylinder functions is . Equal occupations do not change the state, and a particle next to a vacancy jumps across at rate . The stirring representation of symmetric exclusion constructs it for arbitrary initial configurations. The simple occupation-product product self-duality of symmetric exclusion requires symmetry and is not the ordinary duality of an asymmetric process.
On a finite graph with symmetric edge-swap rates, the stirring representation of symmetric exclusion transports the occupations by a random permutation. An independent identically distributed Bernoulli distribution occupation field is invariant under every deterministic permutation, and hence under this random permutation when it is independent of the initial field. Therefore the displayed product measure is invariant, including densities zero and one. Equivalently, an edge swap preserves the number of particles and has the same reverse rate, giving detailed balance.
Give every site a distinct label and interchange labels at the edge marks defining the symmetric simple exclusion process. Each forward or backward label path makes only finitely many jumps in a bounded time interval, since its total rate is . Occupations are transported along these paths. The backward ancestors of a finite set have the law of the finite-particle symmetric exclusion process, by time reversal of the Poisson marks. This proves the product self-duality of symmetric exclusion.
For finite put , with empty product one. Interchanging occupations gives , where interchanges membership of the two sites. The edge-swap generators therefore agree on . The stirring representation of symmetric exclusion proves the displayed identity at all times by tracing the ancestors of backwards. A general asymmetric jump kernel does not satisfy this product self-duality.
If the probability of occupation at every site in a finite set depends only on its cardinality, the law is exchangeable. The product self-duality of symmetric exclusion and conservation of the finite dual particle count imply that all these occupation-product moments are unchanged by evolution. Inclusion-exclusion principle reconstructs every finite cylinder probability from them, proving invariance. This direct argument does not require a representation theorem for exchangeable laws.
In the contact process, infected vertices recover at rate , while each oriented nearest-neighbour edge transmits infection at rate . The empty configuration is absorbing.
For the contact process with per-edge infection rate and recovery rate one on a degree- regular tree, the infinitesimal generator gives . The edge boundary of a finite forest in a regular tree implies whenever , including the absorbing empty state where the generator is zero. Thus the displayed functional is a bounded supermartingale, and the extinction probability from is at most .
The graphical representation of the contact process preserves coordinatewise order. Its law from the all-infected state decreases in stochastic domination with time, and its limit is invariant by the Feller semigroup property. The all-healthy state is absorbing. Any invariant probability law lies between these two laws. Duality of the contact process gives when the recovery rate is one. Consequently the two extremal laws coincide exactly when the survival probability of the contact process is zero.
With recovery rate one, the number of infected sites in a nearest-neighbour contact process has death rate equal to its size and birth rate at most times its size. It is dominated by a linear birth-death branching process with these per-particle rates. In particular, from one infection its expected size is at most , so its survival probability is zero when . This proves the displayed lower bound on the critical rate.
Place recovery marks at each vertex according to independent rate- Poisson processes and infection arrows on each oriented nearest-neighbour edge according to independent rate- Poisson processes. A vertex is infected at time exactly when a time-directed path from an initially infected vertex reaches it while following arrows and avoiding recovery marks.
For the one-dimensional contact process with recovery rate one and per-neighbour infection rate , use parity sites with even. Call a site good if has no recovery in and sends an arrow to each neighbour during . The goodness indicators are independent: recovery intervals for successive parity sites at the same spatial point only touch at endpoints, and all outgoing-arrow intervals and clocks are disjoint. Their common probability is the displayed . A path of good sites carries infection from each time layer to the next, because both its source and target avoid recovery during the transmitting interval. Taking makes . The incoming-edge coupling of site and bond percolation and imply , so this proves a finite critical infection rate.
Map a site to its height . Maintain one infected representative in height for every infected site of an auxiliary one-dimensional contact process. The representative's death makes that auxiliary site recover. Its outgoing arrows to each neighbouring height, each of rate , make an auxiliary infection at total rate , using the arrow's target as the new representative. Arrows to an already infected auxiliary height do nothing there. Distinct active representatives use distinct death and outgoing-arrow clocks, so their conditional rates are exactly those of the one-dimensional process. Every auxiliary infection has a live representative upstairs, proving the survival comparison.
Reachability in the graphical representation gives
Time reversal of the Poisson graphical representation, together with reversal of every infection arrow, gives
The survival probability is the probability that the contact process begun from one infected vertex never reaches its absorbing empty state. Its critical infection rate is .
Local survival means repeated infection of a fixed vertex at arbitrarily large times in the contact process. It implies global survival, but infection can survive by moving away from every fixed vertex on an infinite graph. On a transitive graph the threshold is independent of the chosen vertex, and , with the global survival threshold of the contact process.
Orient a degree- regular tree towards one end, and let height decrease along the unique parent edge and increase along the child edges. For , suppressing the occupied-target constraint only increases births, so its infinitesimal generator satisfies . For , choose . If , the expected weight and the infection probability at each fixed site decay exponentially. The expected number of recoveries there equals its expected total occupation time, which is finite. Each infection episode ends almost surely at a recovery, so infinitely late infection is impossible. For , take sufficiently close to one for each .
This is the critical infection rate for the contact process started from one infected site to avoid its absorbing empty state forever. It concerns infection somewhere in the graph at all times, rather than repeated infection of a fixed site. On a transitive graph it is independent of the starting site. Infection-arrow inclusion couples different rates monotonically.
Inside a rooted -ary subtree of a degree- regular tree, pair each cell root with one distinguished child. Keep reinfection inside each pair, suppress infection back into its parent cell, and allow each child cell to be activated only once. Offspring counts of different cells are independent and identically distributed, so cell genealogies form a Galton-Watson process. A cell root has outgoing child-cell edges and its paired vertex has . Starting at the root, the probabilities to send an arrow along one specified outgoing edge from these two vertices before internal extinction are respectivelyThey follow by first-step equations on the three nonempty pair states. The offspring mean is , andContinuity makes at some strictly smaller positive rate. The branching-process extinction criterion then gives positive survival probability for the suppressed process, hence for the original contact process.
The telegraph process moves at one of two opposite constant velocities and reverses direction at Poisson event times. Its position has finite propagation speed and persistent increments.
If speed and reversal rate tend to infinity with fixed, the integrated telegraph velocity converges to Brownian motion with diffusivity .
An increment of a real- or vector-valued stochastic process is the difference between its values at two times . A random walk accumulates its one-step increments; a Poisson process has nonnegative integer increments counting arrivals in . A process can have independent increments even though its values at different times are dependent.
A stochastic process has stationary increments when the probability distribution of depends only on the duration , whenever both times belong to the index set. The clock origin then does not change the increment law. For Brownian motion, that law is ; for a rate- Poisson process, it is a Poisson distribution with expected value . Neither process itself is a stationary process: their variances grow with . Stationary increments and a stationary process describe different properties.
A stochastic process has independent increments when, for every , the random variables are independent. Adjacent intervals are allowed: each increment represents the change after its left endpoint up to its right endpoint. A Poisson process, Brownian motion, and a random walk with independent steps have this property. Their values at different times need not be independent: for a fair simple random walk on the integer line, because both positions contain the same first increments. Independent increments need not be stationary increments; summing independent steps with time-dependent variances gives a counterexample.
For times , the corresponding finite-dimensional distribution of a stochastic process is the joint probability distribution of the random vector . The collection of these distributions records every finite set of coordinates of the process.
Knowing only the one-time marginal distributions is insufficient. Let be independent standard normal random variables, and let for every , where is one standard normal random variable. Every and has the same standard normal distribution. Nevertheless, for , the difference has a normal distribution with variance two, whereas . The joint probability distribution of is concentrated on the diagonal; that of is spread across the plane. A model for tomorrow's value therefore needs the relation between observations as well as their separate distributions.
For a real-valued stochastic process, its finite-dimensional distributions determine its probability law on the product sigma-algebra. With an uncountable index set, a path property such as continuity need not be measurable in that sigma-algebra; specifying a suitable space of sample paths and a regular modification of a stochastic process is a separate step. This distinction is explained in MIT, The basics of stochastic processes, section 1.1.
Consistent probability distributions on finite collections of coordinates in standard Borel spaces determine a unique probability measure on the product sigma-algebra. Consistency means that discarding coordinates by marginalization agrees with the law already assigned to the smaller collection, and relabeling coordinates relabels the law. The theorem turns finite recipes into a complete stochastic process. In particular, products of one fixed probability distribution construct an independent and identically distributed sequence; putting one common random variable in every coordinate constructs the perfectly shared process above. The theorem supplies a law on the coordinate space, but does not by itself ensure continuous sample paths.
For a real-valued stochastic process with finite second moments, write . Its covariance function isThe diagonal gives the variance at each time; off-diagonal values record linear dependence between times. For the independent standard normal random variables above, , whereas the shared Gaussian process has for all . For a fair simple random walk on the integer line, ; Brownian motion has the continuous-time counterpart . These formulas quantify how much random history the observations share.
Every covariance function is a positive-semidefinite kernel. Indeed, for any real coefficients ,Thus a proposed covariance function must make every finite covariance matrix positive semidefinite. For a Gaussian process, the mean function and the covariance function determine every finite-dimensional distribution, including degenerate ones such as the shared process. Conversely, any real positive-semidefinite kernel satisfying , together with a specified mean function, defines consistent multivariate normal distributions; the Kolmogorov extension theorem then constructs a Gaussian process. For a general stochastic process, covariance alone does not determine the full law. The exceptional completeness of this description is what makes Gaussian process regression possible with a mean and a covariance model.
If a stochastic process indexed by a subset of satisfiesfor some , then it has a continuous modification. More precisely, that modification is locally -Hölder continuous for every .
For a function on the dyadic rationals in , let be its largest absolute adjacent increment on the level- grid. If for , the function extends uniquely to a Hölder continuous function withChoose with . The level- left approximations differ by at most two grid steps, and each finer approximation adds at most one level increment. Thus the difference is bounded by . For a stochastic process with , the bound makes this series converge in the Lp norm for .
For a nonnegative continuous function on that vanishes at both endpoints, the head of the Brownian snake driven by is the centered Gaussian process with covariance functionConsequently , the pseudometric used by the real tree encoded by an excursion.
If the driving function is -Hölder continuous, then its Brownian snake has a modification that is -Hölder continuous for every . Indeed,and the conclusion follows from the Kolmogorov continuity theorem by taking arbitrarily large.
Chordal Schramm–Loewner evolution in the complex upper half-plane from to is the random Loewner chain driven by , where is standard Brownian motion and .
For critical planar percolation in a conformal quadrilateral, Cardy's boundary-crossing probability is , where is its conformal cross-ratio and is the regularized incomplete beta function. This conformally invariant crossing law is associated with Schramm–Loewner evolution at parameter six.
The conformally invariant critical percolation crossing probability can be expressed in an appropriate ordered boundary cross ratio asFor the corresponding SLE exploration at parameter six, it arises from the beta integral for strict ordering of coupled Bessel lifetimes with . In the upper-half-plane configuration , the strict-swallowing probability is this function at . Exchanging the two relevant boundary arcs exchanges the probability with its complement. This is a crossing probability, not the probability of visiting a fixed boundary point.
Chordal SLE at parameter four has driver in half-plane-capacity time. The Itô formula makes the imaginary part of drift-free, a feature used in the SLE4 coupling with a Gaussian free field. The trace is simple and avoids fixed nonzero boundary points.
Radial SLE grows from a boundary point to an interior target. In the unit disc from to , its conformal-radius parameterization satisfiesThe target remains in the remaining simply connected component; the time parameter records its decreasing conformal radius.
For radial SLE at parameter two, the normalized slit-domain Poisson kernel at the growing tip is a local martingale. This observable provides the coupling to loop-erasure of planar Brownian motion, oriented from the boundary point to the interior target. Its discrete counterpart is a loop-erased random walk.
Among Loewner chains with capacity , continuous real driver and initial driver zero, scale invariance and the centered domain Markov property of a chordal Loewner chain characterize Schramm–Loewner evolution with some . Driving-function reconstruction for a chordal Loewner chain turns the hull properties into stationary independent increments and Brownian scaling for the driver. The continuous Lévy process classification then gives , and scaling eliminates . Regularity and parametrization are essential hypotheses of this characterization.
With the upper-half-plane branch, before the Loewner swallowing time. Write . The Itô formula and the Chordal Loewner equation giveAt parameter four its drift vanishes. At other parameters the drift describes the competition between the deterministic conformal evolution and the Brownian driver.
For the SLE angle process, the bounded Dirichlet problem on the unbounded surviving domain has data on the intrinsic boundary mapped to the left of the Loewner driving function and zero on the boundary mapped to its right. For a simple Loewner trace these are its left and right banks, with the negative and positive real rays respectively. The tip is a discontinuity point of the boundary data.
For Schramm–Loewner evolution with and , the Itô formula for the complex logarithm gives before swallowing. The drift cancels exactly at this parameter. Its real part is and its imaginary part is the SLE4 angle martingale. The real-part quadratic variation is , which also gives a direct non-swallowing argument.
Every fixed has infinite interior-point swallowing time for a Loewner chain under Schramm–Loewner evolution at . The centered flow is bounded on any finite horizon, making bounded above. The one-sided bound criterion for a martingale clock gives a finite logarithmic limit at any putative finite swallowing time. Thus stays away from zero and the imaginary coordinate remains positive, so the differential equation extends, a contradiction. In particular the trace misses each fixed interior point almost surely.
For a fixed interior point and parameter four, the SLE angle process has zero drift and satisfies . Its values in make this continuous local martingale a true bounded martingale. The identity , together with the Dambis-Dubins-Schwarz theorem, prevents its Loewner conformal radius from vanishing at a finite lifetime. Since the parameter-four trace is simple and does not meet the real boundary at positive times, finite swallowing would require a visit to the point and vanishing radius. Thus its Loewner swallowing time is infinite almost surely. This gives a global continuous bounded martingale, not just one defined before swallowing.
For , , let , and . Thenis a positive continuous local martingale before the Loewner swallowing time. Indeed the Itô formula gives , , andCombining the exponents cancels the drift of , including the quadratic-variation correction, leaving .
A compact H-hull is a bounded relatively closed subset of the complex upper half-plane such that is a simply connected domain.
For nested compact H-hulls whose closures avoid , the boundary derivative is an excursion avoidance probability. Avoiding the larger hull is a subset of avoiding the smaller one, which proves the derivative inequality. For a hull contained in and , comparison with the filled half-disc gives the sharp bound , since that half-disc has mapping-out function . The empty hull and filled half-disc attain the two bounds.
If a compact H-hull lies in a disc of radius centred at , the displayed estimate holds for , with an absolute constant . It refines the Laurent expansion uniformly in the hull and supplies the first-order increment needed to derive the Chordal Loewner equation from the Loewner local growth property.
Let and stop planar Brownian motion from on reaching height or leaving . Then . The stopped harmonic height is a bounded martingale. The bounded difference makes its top-boundary value differ from by a uniform constant, while optional stopping of the imaginary coordinate bounds the top exit probability by . Killing on the hull is essential.
For a compact H-hull, is harmonic and satisfies . Local boundedness and the interior continuity of show that tends to zero at every finite boundary point. The maximum principle for harmonic functions applied to , with an exhaustion controlling infinity through the Laurent expansion, proves the inequality without boundary smoothness.
The inverse of a hydrodynamically normalized mapping-out function has expansion at infinity. If bounded-domain points had unbounded images , then would be unbounded, a contradiction. Thus is bounded even near finite rough boundary points. Its own expansion at infinity then makes uniformly bounded throughout the domain. Reflection is needed only near infinity, not along the entire hull boundary.
For the compact H-hull , the square-root branch asymptotic to gives the hydrodynamic normalization at infinity of its mapping-out function of a compact H-hull. Its expansion has coefficient , the half-plane capacity of a vertical slit.
If a compact H-hull lies in the unit disc, compare its tail harmonic measure with that of the empty hull and filled half-disc. The Poisson kernel for the upper half-plane turns the inclusion of Brownian exit events into for . Reflection gives for .
For a compact H-hull inside the disc of radius centred at a real point, its mapping-out function of a compact H-hull displaces every point of its domain by at most . After scaling and translation, the real boundary bounds for a unit-disc H-hull put the corresponding inverse boundary interval inside . Boundary cluster points of the inverse over this interval lie in the unit disc. The maximum modulus principle applied to gives the bound without assuming local connectedness of the hull. The nearly closed semicircular slit makes the constant three sharp.
With , the compact H-hull is a unit semicircular arc attached at , with a narrow passage near . As , its normalized mapping-out function of a compact H-hull tends to at each fixed point of the interior bay. Points in that bay tending to therefore have displacement approaching three. The order of these two limits is important.
A conformal map from an upper-half-plane domain has hydrodynamic normalization when at infinity. For a compact H-hull this normalization makes its mapping-out function of a compact H-hull unique.
Articles were limited to the first 100 out of 730 total.


