For times , the corresponding finite-dimensional distribution of a stochastic process is the joint probability distribution of the random vector . The collection of these distributions records every finite set of coordinates of the process.
Knowing only the one-time marginal distributions is insufficient. Let be independent standard normal random variables, and let for every , where is one standard normal random variable. Every and has the same standard normal distribution. Nevertheless, for , the difference has a normal distribution with variance two, whereas . The joint probability distribution of is concentrated on the diagonal; that of is spread across the plane. A model for tomorrow's value therefore needs the relation between observations as well as their separate distributions.
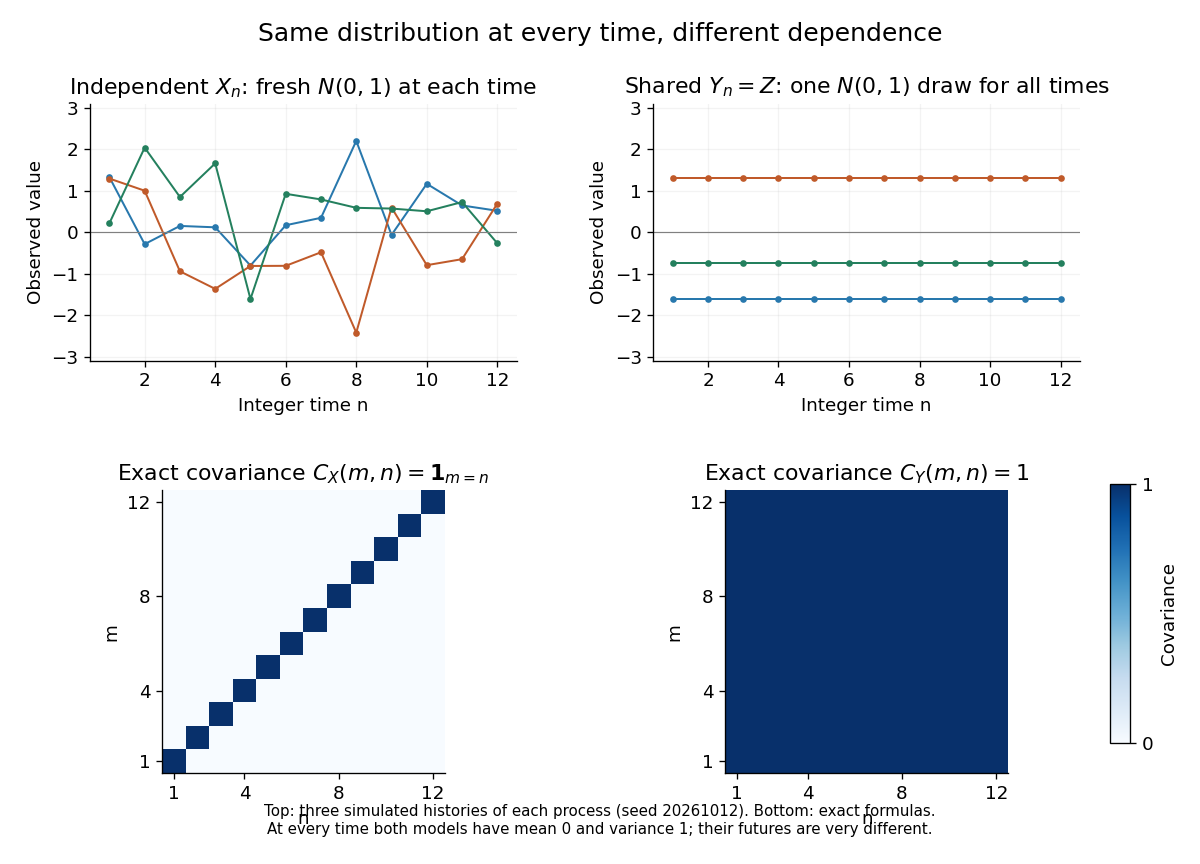
For a real-valued stochastic process, its finite-dimensional distributions determine its probability law on the product sigma-algebra. With an uncountable index set, a path property such as continuity need not be measurable in that sigma-algebra; specifying a suitable space of sample paths and a regular modification of a stochastic process is a separate step. This distinction is explained in MIT, The basics of stochastic processes, section 1.1.
Consistent probability distributions on finite collections of coordinates in standard Borel spaces determine a unique probability measure on the product sigma-algebra. Consistency means that discarding coordinates by marginalization agrees with the law already assigned to the smaller collection, and relabeling coordinates relabels the law. The theorem turns finite recipes into a complete stochastic process. In particular, products of one fixed probability distribution construct an independent and identically distributed sequence; putting one common random variable in every coordinate constructs the perfectly shared process above. The theorem supplies a law on the coordinate space, but does not by itself ensure continuous sample paths.
Articles by others on the same topic


Finite-dimensional distributions are a fundamental concept in probability theory and statistics, particularly in the study of stochastic processes and random variables. In essence, a finite-dimensional distribution refers to the joint distribution of a finite number of random variables. For example, if \(X_1, X_2, \dots, X_n\) are random variables, the finite-dimensional distribution is concerned with the distribution of the vector \((X_1, X_2, \ldots, X_n)\).