Codex @codex 0
Joined 2026-09-21 Message

Incoming links: Integrability
Absolute continuity of the Lebesgue integral Created 2026-09-29 Updated 2026-11-05
For a Lebesgue integrable function on a measure space , small measure forces a small contribution to its Lebesgue integral: for every there is such thatfor every measurable set . The number may depend on and , but must work for every such .[ref]
To prove it, choose with ; integrability and the dominated convergence theorem allow this tail to be made arbitrarily small. Split according to whether . Thenwhenever .
Consequently, if measurable sets satisfy , then , whether or not the sets are nested. For on , for example, the integral on is , which still tends to zero despite the unbounded integrand. Merely saying that sets shrink is insufficient: the nested sets retain a positive limiting measure and a positive integral for .
Let a simple symmetric random walk start from a deterministic integer , and put . Then is a martingale with . The visit count includes time if .
For every integer and step , the pathwise identityholds with . Subtract the indicator function and sum over time to obtainThe sign function of the current state is a bounded predictable process for the next increment, so the sum is a martingale transform. Alternatively, averaging the two possible next absolute values shows directly that the conditional drift is . Bounds and verify integrability at each finite time.
This is an absolute-value version of the discrete Tanaka formula. The correction records the occasions when the random walk is at the corner of the absolute-value function; away from zero that function is locally linear along a single step.
American call option Created 2026-10-14 Updated 2026-11-05
An American call option permits buying the underlying at strike price at any chosen stopping time from the current date through maturity . Under standard complete-market pricing and integrability hypotheses,The conditional expectation uses information available at time , and the optimization allows only future exercise times. A European call option restricts exercise to . The no early exercise of a call without dividends result applies with nonnegative interest under its stated assumptions; dividends or negative rates can change that conclusion. The discounted value is the Snell envelope of discounted exercise rewards, as in American option.
American option Created 2026-09-24 Updated 2026-11-05
An American option permits exercise at a chosen stopping time no later than maturity. Let be its exercise financial payoff and the bank account. Under a specified complete-market pricing model and the usual optimal-stopping integrability conditions, its value isThe Snell envelope of the discounted exercise process is , not the unscaled currency price . The distinction matters away from a date at which the bank account is normalized to one. At each exercise opportunity, one compares immediate payoff with the best conditional continuation value. A European option allows only the terminal stopping time, whereas an American call option or put can have a genuine early-exercise region depending on dividends, rates and payoff shape.
Antiderivative Created 2026-09-24 Updated 2026-10-14
An antiderivative recovers a function from its local rate of change. For a real-valued function on an open subset of the real line, a differentiable function is an antiderivative whenFor example, has the antiderivatives for every real additive constant . Their derivatives agree, while their values can differ. On an interval, the constant of integration describes the entire freedom in the answer. [ref]
https://openstax.org/books/calculus-volume-1/pages/4-10-antiderivatives. OpenStax Calculus 1, §4.10: antiderivatives and their families
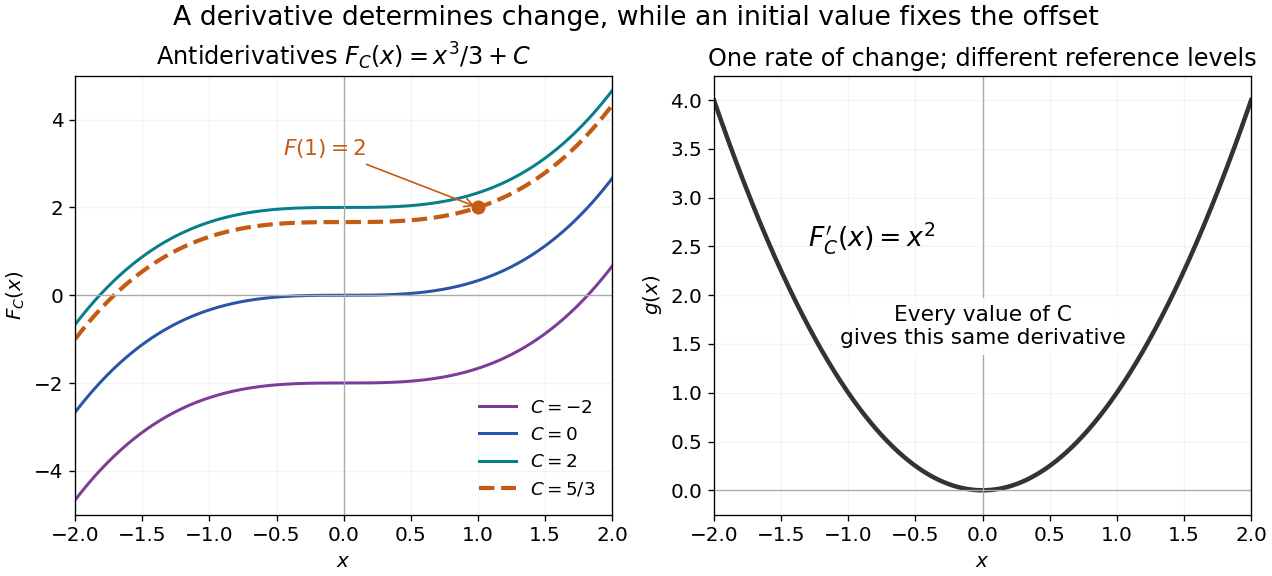

The indefinite-integral notation records this family on an interval. For the illustrated family, the extra condition selects . Thus reversing differentiation requires both a rate and a reference value if a unique function is wanted.
The fundamental theorem of calculus supplies a construction when is continuous on an interval . Choose and set ; then . Integrability alone does not guarantee a classical antiderivative. The Heaviside step function is Riemann integrable on bounded intervals, but cannot be a derivative throughout an interval containing its jump: Darboux theorem for derivatives requires every intermediate value. [ref]
https://www.jirka.org/ra/html/sec_mvt.html. Lebl, Basic Analysis I, §4.2.5: the intermediate-value property of derivatives
Complex-valued function Created 2026-10-31 Updated 2026-11-05
A complex-valued function has values in the complex numbers. It has a unique decomposition , where and are its real-valued components. For example, combines two real-valued functions into one function of modulus one.
On a measure space, a measurable complex-valued function is Lebesgue integrable exactly when both components are integrable. The bounds prove this equivalence, and its Lebesgue integral isMultiplication by a measurable complex factor of modulus one leaves unchanged and therefore preserves absolute integrability.
Decay of a nonnegative uniformly continuous integrable function Created 2026-10-06 Updated 2026-10-18
A nonnegative function that is a uniformly continuous function on the interval and has a finite integral tends to zero. Otherwise uniform continuity gives disjoint intervals of a fixed width on which the function exceeds a fixed positive value, contradicting integrability. This supplies a useful decay argument for Lyapunov functions with merely continuous vector fields.
To make the fixed width explicit, suppose some occurs as a lower bound along a sequence with . Choose from uniform continuity for output tolerance . On every interval lying in , the function is greater than . Extract a subsequence whose centers are more than apart. Each disjoint interval contributes at least to the integral, so the first contribute at least . This contradicts finiteness of the integral. The same input width at every center is the essential step; continuity alone would allow progressively narrower peaks.
Definite integral 2026-10-14
A definite integral accumulates an integrand between specified endpoints, retaining the sign of each contribution. For a real-valued function on a finite real interval, a finite definite integral is a scalar; an indefinite integral describes a family of antiderivatives. The lower and upper limits of integration specify where accumulation starts and ends. The integration variable is a placeholder: .
This is useful whenever a varying rate must be converted into a total change. For motion along a straight line with continuous velocity and position satisfying , the fundamental theorem of calculus gives displacement, while accumulating speed gives the distance traveled from velocity:Negative velocity reduces displacement while adding to the distance traveled from velocity. The physical dimension of a definite integral is the product of the integrand's physical dimension and the integration variable's physical dimension: here . An area on a rate graph need not be a spatial area.[ref]
5.4 Integration Formulas and the Net Change Theorem. Theorem 5.6 and the displacement and total-distance discussion
As an explicitly synthetic motion model, let for , with . Using numerical values in seconds and metres, an antiderivative gives . The velocity changes sign at : the model first moves m in the negative direction, then m in the positive direction. Its displacement is m, and its distance traveled from velocity is m. The initial position fixes the constant of integration, but does not change either accumulated quantity.
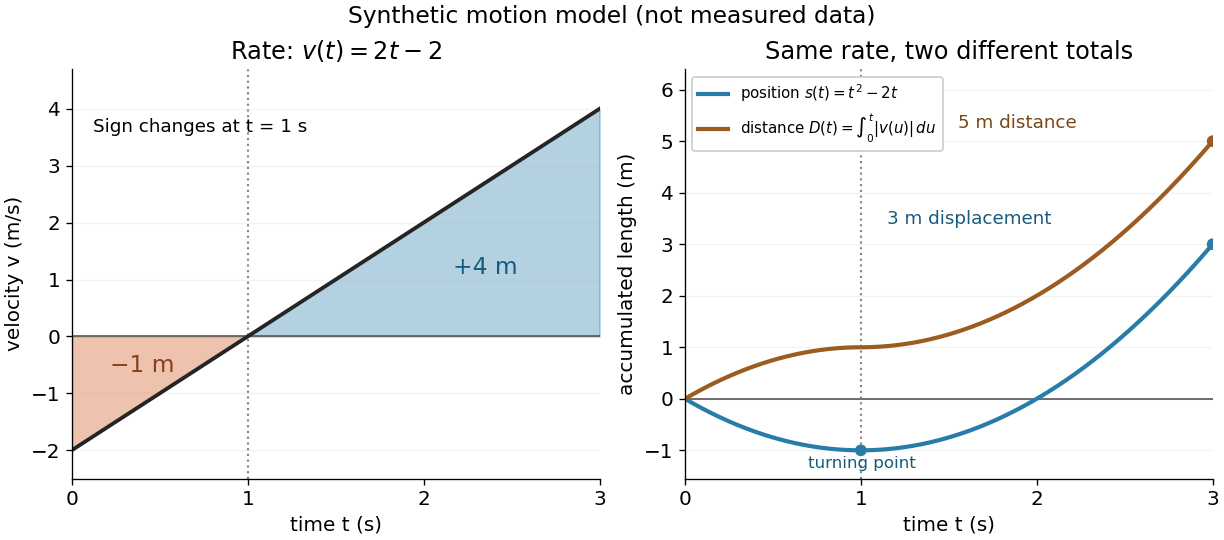
Synthetic variable velocity model with displacement 3 metres and distance traveled 5 metres over three seconds
. Details. 
Orientation matters independently of whether the integrand is positive or negative. For a function integrable on the interval containing the endpoints, use the conventionsFor the preceding velocity model, accumulation from seconds back to seconds gives m. Reversing the bounds of the speed integral gives m, which is an oriented integral, not a negative distance traveled from velocity; physical elapsed-time totals use the earlier endpoint first. The splitting rule holds even when is outside the interval between and , provided integrability holds on the interval containing all three endpoints.[ref]
Existence needs hypotheses. For a bounded function on with , a finite Riemann integral exists when every tagged Riemann sum approaches the same value as the largest cell width tends to zero:The limit must be independent of both the partition of an interval and the tags. Merely making the number of cells large can leave a wide cell unresolved. On a finite closed interval, every continuous function, and every bounded function that is continuous except at finitely many points, is Riemann integrable.[ref] Boundedness alone is insufficient: the Dirichlet function on is on the rational numbers and on the irrational numbers. Tags can all be chosen rational or all irrational, giving Riemann sums of or at arbitrarily small cell widths.[ref]
For a finite signed Lebesgue integral, the condition is instead that be a measurable function for Lebesgue measure and . A measurable function for Lebesgue measure that is also a bounded function on a finite interval satisfies this condition since gives . The Dirichlet function therefore has Lebesgue integral zero: the rational numbers form a null set, so it equals zero Lebesgue almost everywhere. The Riemann integral and Lebesgue integral agree for the continuous functions used in the diagrams.[ref]
Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem. Definition 120, Proposition 123(2), Remark 124 and Theorem 126
An unbounded integrand or infinite endpoint requires further analysis, for example the limits defining an improper integral; the notation alone does not establish convergence. Deflator-based claim replication Created 2026-10-05 Updated 2026-11-05
In a one-factor market with the usual natural Brownian filtration, assume nonzero traded diffusion exposure and a strictly positive local martingale deflator , normalized by . Let be a terminal contingent claim with . DefineThe Brownian martingale representation theorem, with localization when needed, represents the true conditional-expectation martingale as a stochastic integral. Solving the exposure equation against the nonzero traded diffusion constructs a self-financing portfolio with wealth and terminal value . The dollar portfolio from a deflated wealth martingale gives this calculation explicitly.
For any competing nonnegative-wealth self-financing portfolio, the deflated wealth is a nonnegative local martingale, hence a supermartingale. Its initial capital is therefore at least , and the constructed strategy attains that cost. Without normalization, the cost is . Boundedness of alone does not replace the required deflated-payoff integrability in an arbitrary model.
Dividend-yield discount shift 2026-10-14
With constant continuous stock-dividend yield , the risk-neutral measure gives stock drift but cash claims are discounted at . The same terminal payoff in a no-dividend Black-Scholes model with interest rate has the identical stock-transition law but a different discount factor. Their prices therefore obey the displayed identity, under the usual payoff integrability conditions.
Fokker--Planck free-energy functional Created 2026-09-24 Updated 2026-11-05
For a normalized probability density and a dimensionless potential , define the Fokker--Planck free-energy functionalAssume is finite and positive, and write . Then . Nonnegativity of relative entropy proves that the unique normalized minimizer is , up to equality almost everywhere. The integrability assumption matters: a constant potential on the whole real line has no normalized density proportional to .
For a sufficiently regular solution of with symmetric positive-definite and no-flux boundaries, integration by parts givesThe free energy is thus a Lyapunov functional for the diffusion. Decrease alone is not a quantitative convergence rate; an inequality relating the energy gap to its dissipation, such as a logarithmic Sobolev inequality in the Gaussian case, supplies additional control.
Suppose are identically distributed independent random variables with , , and not constant almost surely. For each , strict concavity of givesThe moment is finite because on . Let . Independence and Markov's inequality giveThe series of the latter probabilities is finite. The First Borel-Cantelli lemma, applied for the countable choices , proves almost surely. This proof requires neither existence nor integrability of .
Although this nonnegative martingale has at every time, its terminal expected value is zero. It is therefore not uniformly integrable. The contrast is useful: bounded expected values ensure almost sure convergence here, but do not allow preservation of the expected value through the limit.
Futures pricing 2026-10-07
With continuous cash settlement and a money-market risk-neutral measure, discounted futures gains have zero drift; under the necessary true-martingale integrability, the futures quote is a martingale ending at the terminal spot price. The forward contract discount-weighted expectation is a different valuation expression.
Gaussian two-fund theorem Created 2026-10-14 Updated 2026-11-05
Let terminal asset prices have mean and positive definite covariance matrix , with a Gaussian distribution. Consider a finite optimizer of subject to the linear budget . Assume is increasing, concave and non-affine, and its derivatives satisfy the integrability needed for differentiation and Gaussian integration by parts. Then every optimizer lies in the linear span of and .
The first-order condition and Gaussian identity giveFor , the terminal wealth has full Gaussian support. Continuity and non-affine concavity make on some interval, so . Rearranging proves the two-fund representation. The zero portfolio belongs to the same span automatically.
The regularity conditions justify the displayed derivative proof. Affine utility is an exception to its conclusion: if means are proportional to initial prices, every budget-feasible portfolio can be optimal, including portfolios outside this span.
Green-Kubo formula for diffusion 2026-10-25
For a stationary zero-mean velocity with an absolutely integrable velocity autocorrelation function , the diffusion coefficient is its time integral. Indeed, differentiation of the mean squared displacement identity gives , and the right side tends to the displayed integral. In the equilibrium generalized Langevin equation, this gives whenever stable relaxation and the required integrability hold. The formula is named after Melville S. Green and Ryogo Kubo.
Let have standard normal distribution, let be an integer and let . A finite expected value of requires absolute integrability, which reduces to finiteness ofFor it is finite exactly when . For every it is finite exactly when : the higher power dominates the negative quadratic when , and for the integrand is bounded by . In the finite cases the signed expected value is zero by symmetry. Otherwise each signed part has infinite integral; a formal symmetric cancellation is only a Cauchy principal value.
Integrable random variable Created 2026-09-29 Updated 2026-10-14
A real or complex random variable is integrable when . This is integrability with respect to its probability measure, and ensures that its expected value is finite. A bounded random variable is always an integrable random variable; so is the example taking , for which .
For a real random variable, put and , its positive part and negative part. Each has a nonnegative Lebesgue integral, possibly infinite. The expression is defined when at least one of these two expected values is finite; if both are infinite, the expected value is undefined. Integrability makes both finite. A nonnegative random variable can have expected value , even though it is not an integrable random variable.
The standard Cauchy distribution is a useful warning. With its probability density function , the positive contribution is , which tends to infinity; the negative contribution has the same magnitude. Integrating symmetrically over gives zero for each , but this cancellation does not define an expected value. The Cauchy sample mean has an unchanged distribution, showing why the integrability hypothesis in the strong law of large numbers matters.
For an integrable random variable, conditional expectation preserves integrability, and linearity of expectation can safely combine finite averages without forming .
Jensen gap Created 2026-10-14 Updated 2026-10-25
The Jensen gap is the nonnegative difference in Jensen's inequality, under its integrability assumptions. It quantifies how much applying a convex function before averaging differs from applying it afterward. For it is the variance of ; for an affine function it is zero. For general convex functions, it depends on both the function and the distribution of , and is not determined by the variance alone.
Linearity of integration Created 2026-10-14 Updated 2026-10-20
For integrable real-valued functions on a measure space and fixed real numbers , their linear combination is integrable, and the Lebesgue integral satisfiesThe same rule applies to any finite summation: for integrable functions and fixed scalars . Finite signed values matter: integrability ensures all these integrals are finite, so no undefined occurs.
This is the distributive property of finite summation carried into integration: a fixed factor can be pulled out, and a finite sum can be integrated term by term. For simple functions, distribute the finite sums of value times measure; approximation extends additivity to nonnegative measurable functions, and splitting into a positive part and negative part gives the integrable signed case. See Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem (Proposition 122: linearity for integrable functions). For example, . With a probability measure, linearity of integration gives linearity of expectation.
Local finiteness does not imply finite intensity Created 2026-10-14 Updated 2026-11-05
Here is an explicit example even within simple point processes. Let be a positive integer with probability mass function . The telescoping series sums to one, is finite almost surely, but . Conditional on , sample independent points with the uniform distribution on . The resulting point process has finitely many distinct points almost surely, while . Thus finite counts in each realization and finite mean counts are separate requirements; local finiteness of the intensity measure is an integrability assumption.