Collect the two dependent variables in a column vector. The vector field and initial vector areThe given system of ordinary differential equations is then with . Both components of are continuous on all of , since their denominators are at least one.
Each denominator is at least one and positive, so each component of lies in . Taking the maximum norm therefore givesThis is a global bound, so in particular the constant is valid throughout the specified cube.
For and ,Apply this to the first component with , , . The reverse triangle inequality givesFor the second component use , , to obtain . Taking the maximum yieldsThus is globally Lipschitz continuous in the dependent vector, uniformly in , with Lipschitz constant . Differentiability of the absolute-value function at zero is unnecessary.
A Lipschitz condition here is uniform in the independent variable: there is a finite constant such that, whenever both and belong to the cube,The same must work for every allowed . Part (c) proves this with . This controls changes in the dependent variables; no Lipschitz condition in is required for the Picard-Lindelöf theorem.
The quantitative Picard-Lindelöf theorem applies on a rectangle , . Suppose is continuous there, bounded in maximum norm by , and uniformly Lipschitz continuous in . Then the initial value problem , , has a unique solution onwith the usual interpretation if . The solution remains in the dependent-variable ball. Its endpoints are included when is continuous on the closed rectangle, as here. Equivalently, existence first on every smaller interval and the derivative bound give extension to those endpoints.
For the given cube, and . Thus the theorem gives once a bound and a uniform Lipschitz constant have been established. The theorem does not require : convergence of Picard iteration can be proved by factorial estimates or by using successive shorter intervals.
The vector field is continuous on the cube. Part (b) gives , and part (c) supplies a uniform Lipschitz constant . In the quantitative Picard-Lindelöf theorem, the independent-variable half-width and the dependent-variable radius are both one, soThereforeThe global derivative bound also makes the cube condition explicit. Along any solution segment starting at the initial point,Thus it cannot leave the dependent-variable ball before . Bounded derivatives give limiting endpoint values, and local existence extends to them because is defined continuously on all space. Uniform Lipschitz continuity ensures that all such local pieces agree on overlaps, proving uniqueness throughout the closed interval.
For , the discriminant is , so the equation is an elliptic partial differential equation, already in the canonical Laplace equation form .
For , the discriminant is , so it is a hyperbolic partial differential equation, the wave equation . Introduce characteristic coordinatesThen and , givingOn , the discriminant vanishes and the principal part has rank one; the degenerate parabolic type is . This is an interface line, rather than an open parabolic subdomain. ThusThis is a mixed-type partial differential equation. The classification concerns the principal part and remains meaningful even though the coefficient jumps at the interface.
In the lower triangular region, the characteristic coordinates obey . Integrating the canonical wave equation givesOn the right characteristic edge, and , so its prescribed value gives . On the left edge, and , giving . At the common vertex the two values agree and equal zero; hence .
Adding the two edge identities and subtracting this vertex identity determines the entire solution:The apparent freedom to add a constant to and subtract it from does not change . Every classical lower-region solution has the displayed separated form, so these two characteristic boundary traces determine it uniquely. Substitution into and into both edge values directly verifies existence.
The lower formula has a smooth continuation as a function of , and on it has trace . Its second tangential derivative iswhich vanishes at . Hence the continued lower formula satisfies the equation restricted to the interface, where the formal equation is .
Assuming the solution itself is continuous across the interface, the upper region therefore has the Dirichlet boundary value problemThe zero function satisfies these data. The maximum principle for harmonic functions, applied to both and , proves uniqueness among harmonic functions continuous on the closed rectangle. Thus is the continuous upper continuation. Satisfaction of the degenerate interface equation does not impose continuity of the normal derivative; that is the issue in part (d).
Differentiate the uniquely determined lower solution and the zero upper solution:Their one-sided traces areThey disagree, for example at , so the normal derivative is not continuous across the interface. The jump, defined as upper trace minus lower trace, is . It vanishes at the two interior points , but not identically on the interface.
This illustrates that continuous transmission need not preserve normal derivatives. In fact, at any point where these traces differ, the two-sided first derivative with respect to does not exist. The resulting function is continuous and smooth separately on each open side, but is not globally . Consequently a globally classical solution satisfying all these data cannot exist. The calculation in part (c) evaluates the smooth lower formula on the interface; it does not supply the missing cross-interface regularity.
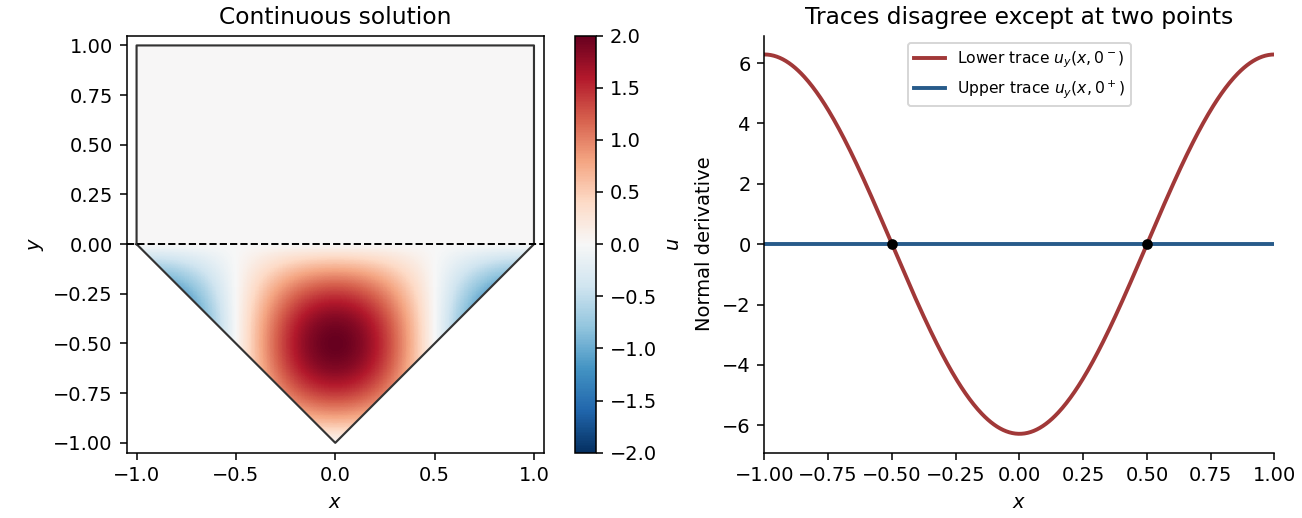
Continuous piecewise solution and unequal normal derivative traces
. Details. 
Inside the half-plane of convergence, the differentiation theorem for the Laplace transform permits differentiation with respect to the transform variable. Since ,Repeating the argument, or applying induction using , givesThe identities hold for , within the stated convergence half-plane. The usual transform differentiation theorem uses an interior margin in the real part of to control the polynomial factors in ; it makes no assertion on the boundary .
Integrating the complex exponential and taking its even and odd combinations gives the standard Laplace transformsFor example, for , and the real sine and cosine identities follow by combining the two signs of .
Apply part (a) once to the cosine transform and twice to the sine transform:All four transforms are valid on the stated right half-plane.
Write and . The zero initial data and the Laplace transform of a derivative give . Transforming the forcing with part (b),ThereforePart (b) with gives . Comparing coefficients and using uniqueness of the Laplace transform,As a direct check, , so both initial values vanish. Differentiating once more cancels the terms in , leaving as required. This also checks the factor in the inverse transform.
Articles by others on the same topic
There are currently no matching articles.