The raw natural filtration isEquivalently it is the smallest sigma-algebra making every observation , , measurable. As enlarges the set of observations, . It is the smallest filtration to which the process is adapted. If the usual conditions for a filtration are imposed, take the completion by the probability-zero sets and its right-continuous augmentation. Brownian independent increments remain valid for this usual augmentation. Adding arbitrary future information is not part of the generated filtration.
Independent increments give independent of . Their joint probability density function at is the productThe change of variables has Jacobian determinant one. Therefore the joint probability density function of isIn particular these coordinates are correlated, with covariance , although the first pair has independent coordinates.
The increment is independent of , with characteristic function . Since is measurable at time ,The heat kernel identity in the hint gives , so this is exactly . Multiplying by the deterministic factor givesThe process is adapted, and is finite at each fixed time. Thus it is a complex martingale, meaning that its real and imaginary parts are integrable martingales.
Apply Itô's lemma to . Since , and , the drift terms cancel:This is initially a local martingale. On every finite interval ,so the stochastic integral is a true square-integrable martingale. Conditional expectation gives ; divide by the nonzero -measurable factor to obtain
If is Brownian motion with respect to the given filtration, independent Gaussian increments give the identity immediately.
Conversely, fix and let . Taking expectations gives its characteristic function , so . To prove independence, for any define the finite measure . The conditional identity givesUniqueness of Fourier transforms of finite measures implies . This is independence of from . Iterating over times proves independent increments. Together with the stated continuity and , this gives standard Brownian motion.
Here a process with the stated filtration is understood to be adapted, as required when saying it is Brownian with respect to that filtration. If adaptedness is not implicit, it must be added: an ordinary Brownian motion with a trivial filtration satisfies the displayed conditional characteristic function but is not adapted to that filtration.
Lévy characterization of Brownian motion says that a continuous local martingale with is standard Brownian motion with respect to its filtration if its quadratic variation is . Equivalently one may require to be a local martingale.
Any weak solution has the integral form . Its bounded integrand makes it a continuous local martingale starting at zero, andThe specified value of the sign at zero has square one as well. Lévy characterization of Brownian motion therefore proves that every such weak solution is Brownian motion. This is a statement about its law and filtration; it does not assert or provide a strong solution as a function of a specified driver.
Let and . Itô's lemma for the exponential givesTo justify that this local martingale is true, note that a deterministic Itô integral is Gaussian: step-function approximations are centered Gaussian sums with variances tending to , and Itô isometry gives their convergence. Thus andContinuity of on the compact interval bounds and , soThe differential above is therefore a square-integrable stochastic integral, proving the martingale property on , with initial value one.
Integrating the preceding differential gives . Consequently , and the representation isThe process is continuous and adapted, hence progressively measurable, and the finite-sum inequality together with the previous second-moment estimate gives .
If is another square-integrable predictable integrand with the same representation, Itô isometry givesThus uniqueness is up to null sets in the square-integrable integrand class. Pointwise uniqueness is impossible: changing a value at one deterministic time changes no Itô integral. Square integrability is the natural class for this representation and is needed for this uniqueness argument; the mere word adapted does not by itself specify an integrable stochastic integral.
The semimartingale integration by parts givesHere . Substitution therefore gives cancellation of the drift:The continuous adapted integrand is locally square integrable. Stopping when first exceeds an integer produces true stochastic-integral martingales, hence is a local martingale. No unproved global integrability of the product is needed.
Put and . Since and has finite variation, the product rule has no quadratic-covariation contribution:Integrating and multiplying by yieldsThe deterministic integrand is square integrable on every compact interval. This constructs a strong solution. Two solutions driven by the same Brownian motion have difference solving , , hence their difference vanishes, proving pathwise uniqueness.
The deterministic stochastic integral in the solution is centered Gaussian with varianceTherefore has mean and varianceFor this is strictly positive, since . Its density at isThe boundedness assumptions on and its reciprocal in particular ensure nondegeneracy; compact-interval continuity is already sufficient for the displayed finite-time construction.
With a standard normal random variable,For , in the usual sense that and its continuous derivative are bounded, the mean value theorem bounds the difference quotient by . Dominated convergence theorem therefore allows differentiation inside the integral:This also follows pathwise from . If the textual description were read as assuming only bounded differentiability, some control of is needed for the displayed right side; the stated hypothesis supplies it. Gaussian smoothing itself still differentiates a bounded measurable , using the derivative of the Normal distribution instead.
First take the intended annulus configuration with . The first stopping time is finite by the allowed fact, and continuity gives . After , the annulus exit time is bounded by the exit time of the outer disc, which is almost surely finite; use the Strong Markov property at . Thus almost surely.
The function is harmonic on this annulus. Its stopped value is a bounded martingale, so optional stopping theorem and continuity give, if is the probability of hitting the inner circle first,ConsequentlyFor fixed , one may take and let . The probability of hitting the inner circle before the outer one tends to one. The probability of ever hitting that inner circle is at least each of these probabilities, hence is one. Taking the countable intersection for , , proves visits to balls of arbitrarily small radius almost surely.
The source permits as well. Then and the actual starting radius for the next exit is one, rather than . More generally put . If , the answer for the literal definition is . If , the infimum defining the next exit is already almost surely and the inner-circle probability is zero. Positive is implicit in an annulus and is necessary for the logarithmic calculation.
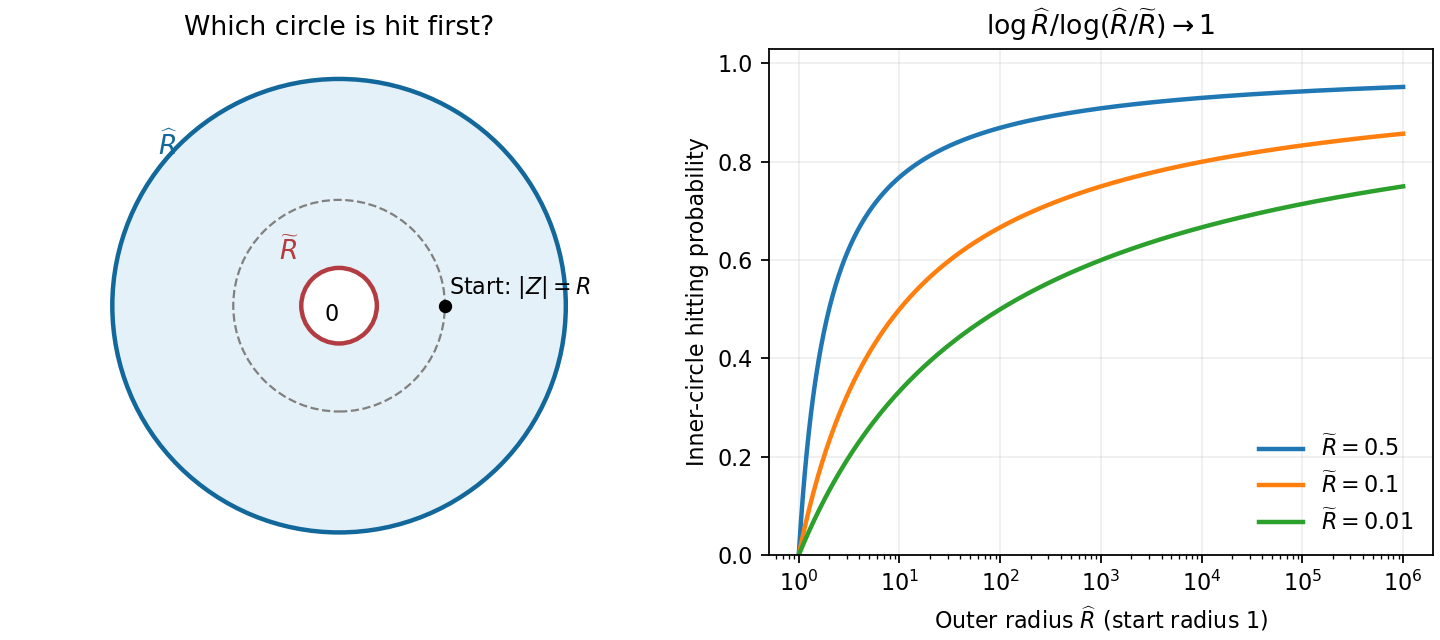
Logarithmic annulus hitting probabilities and visits to arbitrarily small discs
. Details. If , apply translation, rotation and Brownian scaling toThis is standard planar Brownian motion started at one. Its almost-sure visits to arbitrarily small discs about zero translate to visits of to discs about , with radii multiplied by . Therefore the same neighborhood recurrence holds for every pair . If , every such disc is already hit at time zero. If positive hitting times are requested, continuity gives positive times within every fixed disc as well. A countable sequence of shrinking radii suffices to obtain one probability-one event for this assertion.
For a continuous local martingale starting at zero, Burkholder-Davis-Gundy inequalities compare its maximal size with its quadratic-variation clock:They remain valid with infinite values, by stopping and passage to the limit. Their significance here is that the horizontal and vertical martingales share the same stopping-time clock, so one coordinate's maximum can determine moments of the other and of the clock. For a process started away from zero, first subtract its initial value.
Starting at , the vertical coordinate starts at one and is stopped on first hitting zero. For , it reaches level before zero with probability , by optional stopping theorem of one-dimensional Brownian motion on . ThusThe tail integral formula givesand it diverges for .
The stopped martingale has quadratic variation . Its maximum in absolute value is , between and , so it has precisely the same finite positive moments as . BDG therefore gives exactly for . Applying BDG to , which starts at zero and has the same clock, yieldsTaking the displayed or powers does not change finiteness. In particular the exit time is almost surely finite while its mean is infinite.
First, planar Brownian motion started away from zero almost surely never hits zero. To see this without confusing it with neighborhood recurrence, stop in an annulus with inner radius and fixed outer radius . The preceding logarithmic calculation gives probability of reaching the inner circle first. A hit of zero before the outer exit would require all these inner hits, so its probability is zero as . On every finite path interval the continuous path is bounded; a countable union over integer outer radii and integer times proves the all-time assertion.
Consequently the integrand is locally square integrable: on every compact time interval the nonvanishing continuous path has a positive minimum modulus. Write with independent standard real coordinates. Complex quadratic covariation satisfies , so analytic Itô's lemma has no second-derivative drift. For one likewise has , and . The product rule therefore givesIts initial value is , proving, simultaneously for all times by continuity,Thus and is the continuous accumulated change of complex argument of the path about zero, measured in radians. It is a winding angle, without reduction modulo . A single-valued logarithm on the whole punctured plane is unnecessary; the path has a continuous stochastic logarithm of planar Brownian motion.
Write with and choose its initial argument once. The exponential map in the source is a covering of the punctured disc, rather than a bijective map onto the full disc. Its pathwise inverse is the continuous liftFor this lies in the upper half-plane, and at the disc exit it lies on the real line. Local conformal invariance of planar Brownian motion, or the quadratic variation of its analytic derivative , shows that is planar Brownian motion run at the clockThe disc exit time is finite almost surely. The path avoids zero on the compact interval through its exit, so its minimum modulus there is positive and . Before this terminal clock time the lifted imaginary coordinate is positive, and at it the coordinate is zero. Hence it is exactly the upper-half-plane exit time of the time-changed Brownian motion, not an additional arbitrary stopping time.
The starting point of the lift is with . Its real exit coordinate has Cauchy distribution . Since that coordinate is , we obtain the stronger exact lawIts first absolute moment diverges:There is no contradiction with the terminal point lying on the compact unit circle: reducing its argument modulo loses the number and direction of turns accumulated before exit.
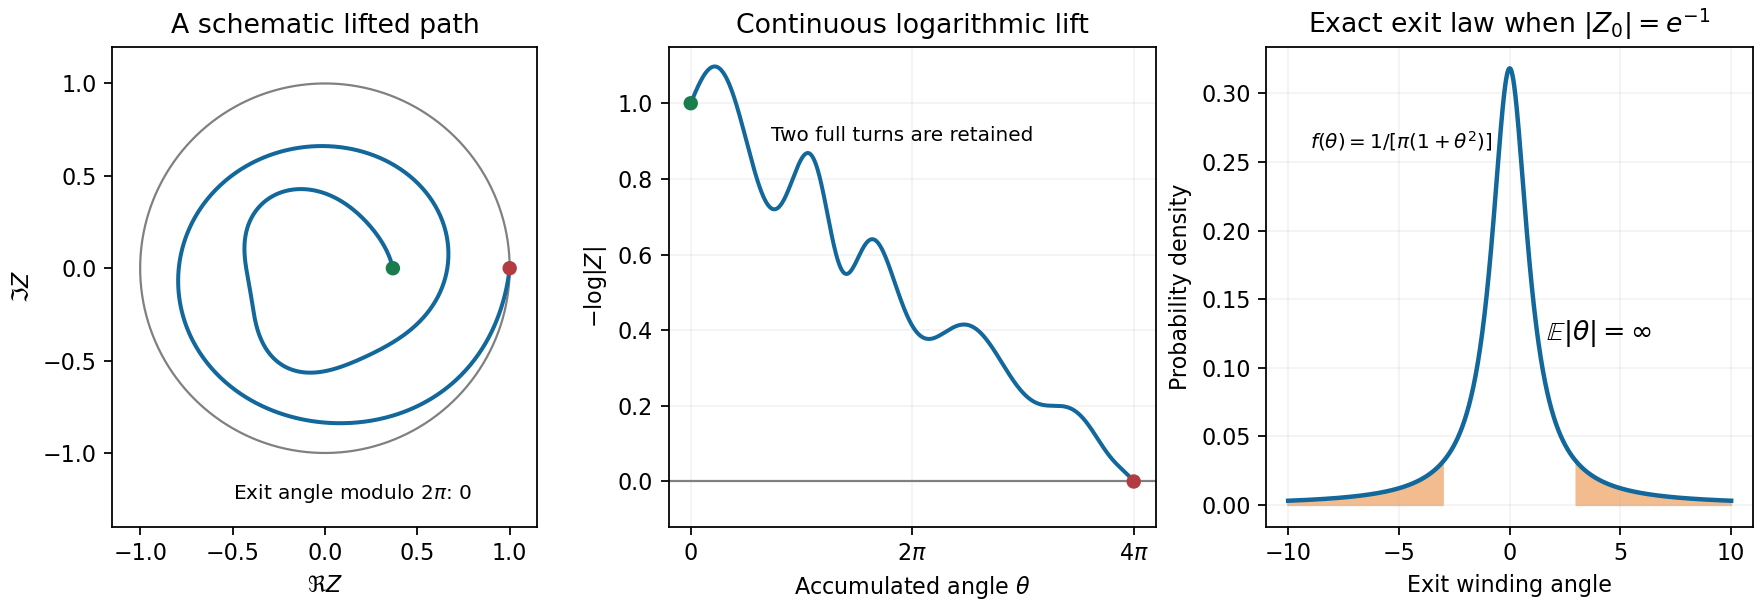


The printed upper-tail identity cannot be a probability formula: it vanishes at zero and increases in . Its correction isEquivalently the cumulative distribution function is . Differentiating that cumulative function gives the densityThe normalization and sign can also be checked directly by conformal invariance of planar Brownian motion: the Cayley transform sends the starting point to the center of the unit disc. Its exit angle is uniform by rotational symmetry. The inverse on the unit circle gives , uniform on , whose change-of-variable density is exactly the one above.
For a start , , translation and positive scaling send it to . Thus the exit coordinate has law , where is standard Cauchy. The corresponding formulas areThis is the upper-half-plane Poisson kernel. The printed density is correct; it is the preceding asserted tail from which it is meant to follow that needs correction.
Using the Cauchy distribution from the preceding part gives one common probability space for all starting points:As with , almost surely, since is a finite real random variable almost surely. Continuity of at zero gives almost surely, and boundedness supplies an integrable constant bound. Dominated convergence theorem therefore provesThe argument applies to every sequence approaching zero, including tangential approaches. Along the real boundary the extension is already , which is continuous. Hence the extension is continuous at zero in the closed half-plane. No finite moment of the Cauchy distribution is required.
Articles by others on the same topic
There are currently no matching articles.