Source: released examination bundle,
Part C 2007 11.pdf, pages 372–377. All six questions in both halves are covered. No mark allocations are printed.Write the stochastic differential equation in integral form and replace the unknown integrand by the preceding Picard iterate. With the deterministic initial vector , the recursion isEach iterate is a continuous adapted process. The Itô isometry inductively gives its square integrability on every bounded time interval, so all these Itô integrals are well defined.
Use for the dummy integration variable in the printed integral. The Itô isometry givesThe assumed second-moment bound also proves the integrability needed to apply the Itô isometry. The extra time integration is the source of the factorial improvement.
Set , where the norms are operator norms, and . Independence of the Brownian coordinates and the vector Itô isometry giveInduction, as in part (b), yields the Factorial Picard estimate for a linear stochastic differential equationFor , the triangle inequality in therefore bounds any tail of the iterates by the corresponding tail ofThis numerical series converges by the ratio test: successive terms have ratio . Thus the iterates are Cauchy in , uniformly in the deterministic time parameter on each bounded interval. Completeness of Lp spaces gives a limit . Once its continuous adapted version is chosen in part (d), the Itô isometry permits passage to the limit in the integral equation: the squared norm of each integral difference is bounded by . Consequently the Picard limit solves the stochastic differential equation.
For every , is a continuous square-integrable vector martingale. Its norm is a submartingale, so the Doob L2 maximal inequality and the estimate from part (c) giveThe Cauchy-Schwarz inequality now showsBy Tonelli's theorem, the random sum of these suprema is finite almost surely. Therefore the telescoping series converges absolutely and uniformly on outside one null event. Its limit is continuous and agrees at each fixed time with the limit from part (c). Taking the intersection of the probability-one events for integer provides a single version on the whole half-line. HenceThis also gives the requested pointwise almost-sure convergence of the full sequence.
Standard Brownian motion is centered, so . If , write ; the final increment is independent of and has mean zero. ThusThis is the Brownian covariance kernel. Together with joint Gaussianity and continuous paths, it gives the Gaussian-process characterization of Brownian motion.
For positive times the transformed process is centered and jointly Gaussian, andIts paths are continuous away from zero. To verify continuity at zero, we need almost surely as . The strong law of large numbers applied to the independent increments gives . On the unit interval after , the Doob L2 maximal inequality givesThe Borel-Cantelli first lemma, first for each positive rational , shows that these between-integer fluctuations divided by tend to zero. Hence for all real , and as .
The Gaussian-process characterization of Brownian motion now proves is standard Brownian motion, with respect to its natural filtration. This is time inversion of Brownian motion; the transformed process need not be adapted to the original forward filtration.
The Itô formula for givesThe stochastic integral has expectation zero: its square integrability on a finite horizon follows from the finite sixth moments of a normal distribution. Since , integration and expectation yield
Put and . In the two-variable Itô formula, has finite variation, while the only nonzero quadratic term is . ThereforeThis proves the stochastic exponential solves the equation. Its initial value is ; no normalization was stipulated.
The resulting process is initially a continuous local martingale. Since and ,A bounded local martingale is a true martingale: apply the martingale identity to a localizing sequence and use dominated convergence in conditional expectations. The deterministic bound works on every finite horizon, proving is a martingale on every . The bound on also gives a positive deterministic lower bound , although the upper bound already proves the martingale assertion.
There is a printed domain error: defines the right half-plane. Taken literally, continuity forces almost surely, so its law is a point mass at zero. The displayed density belongs to the intended upper half-plane , with . We prove that intended assertion explicitly.
Write for independent standard Brownian motions. The exit time is the first time hits , and depends only on . Its density, by the supplied Brownian first-passage time law, is . Conditional on , the real exit coordinate is normally distributed with mean and variance . Independence therefore givesWith , the integral is . Thus the Cauchy exit law from a Brownian half-plane isFor the literal right half-plane, the corresponding nondegenerate coordinate is , whose density is for .
If is a conformal map, the image of planar Brownian motion in is Brownian motion in after the increasing clock changeMore precisely, is planar Brownian motion, starting at and run up to the relevant exit time. The Itô formula and the Cauchy-Riemann equations give image-coordinate local martingales with common bracket and zero cross bracket; the Lévy characterization of multidimensional Brownian motion identifies the time-changed process. In particular, conformal invariance of planar Brownian motion transports exit locations and harmonic measure, while changing traversal speed.
For in the strip,so . This is a bijective conformal map onto the upper half-plane. One way to verify bijectivity is to factor it as , followed by . The first map gives , . The two inverse roots of the second map have product one; for any point in the upper half-plane exactly one root has modulus greater than one, and its imaginary part is positive because .
The three boundary pieces map as follows: the lower edge goes to , the upper edge to , and the vertical edge to . Thus the desired exit event becomes exit from the upper half-plane to the left of . WriteBy conformal invariance of harmonic measure and the Cauchy exit law from a Brownian half-plane,The strip exit is finite almost surely, since its imaginary coordinate exits in finite time; corners have probability zero because individual points are polar points for planar Brownian motion. This is the Top-edge exit probability of a Brownian half-strip.
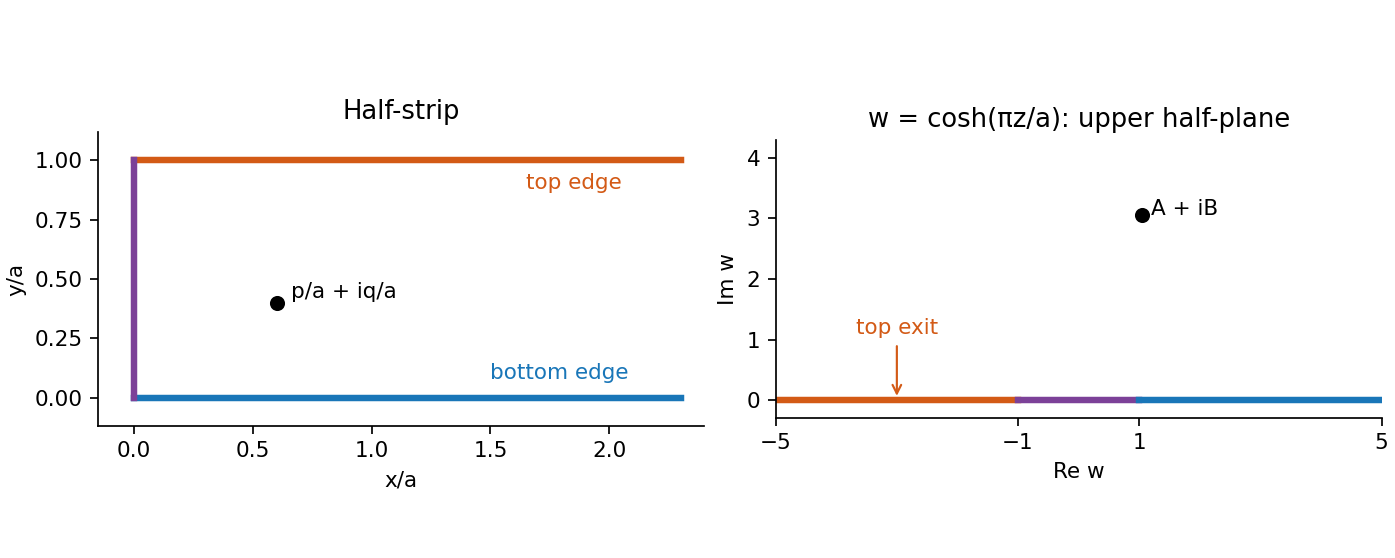
Boundary pieces of the half-strip under the hyperbolic-cosine map
. Details. 
Let . With and fixed,The principal arctangent satisfies throughout this interval. Substitution givesFar from the vertical boundary, the limit agrees with the one-dimensional Brownian motion probability of reaching height before zero.
The disk exit time is finite almost surely; for example, either coordinate of the planar Brownian motion eventually leaves . By path continuity, the exit lies on the unit circle. Starting at the origin, rotational invariance of planar Brownian motion makes the exit law invariant under every circle rotation. The unique rotation-invariant probability measure is normalized arc length. Consequently is uniform on the unit circle, or equivalently its angle has density on .
By conformal invariance of planar Brownian motion, has the uniform boundary law from part (a), because the image process starts at zero. A disk automorphism extends to an orientation-preserving boundary diffeomorphism. Choose a continuous angular lift satisfyingThe principal-angle version may have a branch jump, which is harmless for the density. The change of variables for probability densities yields the exit-angle density . Differentiating the boundary relation givesTaking absolute values proves . ThereforeThe angular lift explains rigorously the derivative appearing in the printed hint despite the principal-angle branch cut.
By Brownian scaling, is planar Brownian motion started at . Its unit-disk exit angle is exactly the original radius- exit angle. Substitute into the supplied Poisson kernel for the unit disk:This density is with respect to angle . Its density with respect to arc length would be smaller by a factor .
Put . The triangle inequality gives , so the Poisson kernel for the unit disk obeysIf , replace the lower bound by and the upper bound by . Integrating against the positive measure givesHere is exactly the uniform boundary average from part (a). Positivity permits multiplication of the pointwise kernel bounds; continuity on the compact circle ensures all integrals are finite. This is the Harnack inequality on the unit disk.
Use first that planar Brownian motion avoids a fixed point, so the path starting at never reaches zero. Its continuous logarithmic lift, initialized at zero, has real part and imaginary part the continuous unwrapped angle . Local branches of the complex logarithm, patched along the path, and the Itô formula show that both coordinates are continuous local martingales withThe clock is finite on every compact time interval, since a continuous nonvanishing path stays a positive distance from zero there. It is continuous and strictly increasing. Moreover : by recurrence, planar Brownian motion spends infinite total time in a fixed disk, and inside the unit disk the clock integrand is at least one. This is the divergence of a positive planar Brownian occupation integral.
The common-clock time change of orthogonal local martingales, using the Lévy characterization of multidimensional Brownian motion, supplies independent Brownian coordinates such that . Exponentiating givesTo identify the inverse clock, write . The derivative of an inverse function and the representation just obtained giveConsequentlyThe strict inequality in this generalized inverse has the same infimum as the unique inverse value, since is continuous and strictly increasing onto the half-line.
Assume , as required for the annulus and logarithms. The logarithmic radius of planar Brownian motion is a local martingale. Stopping at keeps it between the constants and , so the stopped process is a bounded martingale. The exit time is finite almost surely because the annulus is bounded and Brownian motion eventually exits its containing disk.
The optional stopping theorem followed by dominated convergence gives . Continuity puts the exit radius at either or . If is the inner-exit probability, then . HenceStopping before taking expectations matters: the unstopped logarithmic-radius process is a strict local martingale, so one cannot assume its unrestricted expectation is constant.
The second coordinate is one-dimensional Brownian motion, whose zero set is unbounded almost surely by recurrence. The clock and its inverse are continuous, increasing, and unbounded, so the unwrapped angle has zeros at arbitrarily large original times.
To ensure the times are stopping times for the original Brownian filtration, define directlyThe logarithmic lift makes a continuous adapted process. Hitting a closed set after a stopping time is a stopping time under the usual filtration conditions, and the unbounded zero set proves inductively that each is finite almost surely. Since , the sequence tends to infinity, and continuity givesGeometrically, the Brownian path returns to the positive real ray at arbitrarily late times with zero net unwrapped winding angle about the origin. The assertion is stronger than principal argument zero, which also allows any integer number of completed turns.
The long-time Spitzer winding theorem states that, for the continuous unwrapped angle of planar Brownian motion started at ,Here has the standard symmetric Cauchy distribution. The notation means convergence in distribution: for every real ,Equivalently, expectations converge for every bounded continuous test function. This is a statement about the laws at large deterministic times, without asserting almost-sure convergence of sample paths. The angle is unwrapped; a principal argument is bounded and would instead give zero after division by .
Let . It is a nonnegative extended random variable, and implies . Otherwise its expectation would be infinite. Intersect this event with the countably many probability-one events on which the individual sample paths are continuous.
For every path in that intersection, . The Weierstrass M-test gives absolute and uniform convergence of on the entire stated time domain. A uniform limit of continuous functions is continuous. Therefore has continuous paths almost surely. The finite expectation is used to obtain pathwise summability before applying this deterministic theorem.
The subsequent printed maximum inequality is false as stated. For its integrand never reaches one, and its right-hand side isBut for two independent absolute standard normal variables, using their common distribution function and the standard normal density ,The middle step is integration by parts with . Thus no proof of the displayed source inequality can hold for all its stated indices.
The correct tail integral formula for expectation isA valid union bound givesIn particular, for this is at most , where . This corrected estimate proves the intended summability in part (c), without silently replacing the source formula.
Use the valid Gaussian maximum estimate from part (b), withSplit the tail integral formula for expectation at . Bounding the first part by and applying the Gaussian tail estimate to the second givesThus . The finitely many small indices also have finite expectation; the bound above already covers them.
By Tonelli's theorem, nonnegativity permits interchanging sum and expectation:The final series converges because its exponential decay dominates the factor . This establishes the requested conclusion independently of the false bound printed in (1).
In the Lévy construction of Brownian motion, each level is a continuous piecewise linear sum of tents with disjoint interiors. Its supremum norm is therefore the largest absolute tent height, not the sum of the heights. With the standard construction's height standard deviation ,Part (c) makes finite, and part (a) proves almost sure uniform convergence to a continuous path on . The separately chosen linear endpoint term completes the construction; its Gaussian finite-dimensional distributions and covariance must also be checked to identify the limit as Brownian motion. Independent copies on successive unit intervals extend it to the half-line.
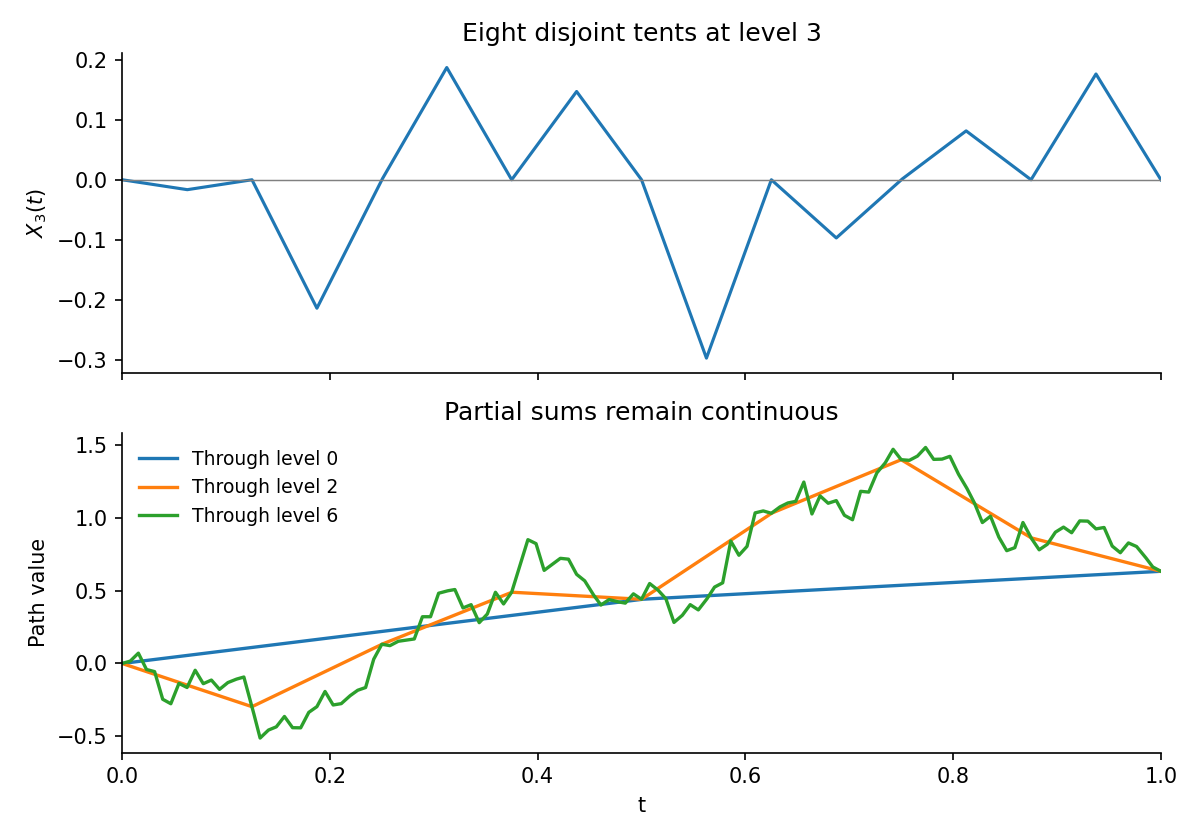
Disjoint dyadic tents and successive continuous Lévy approximations
. Details. 
The source calls a variance. Literally using that variance would give height standard deviation instead. The same maximum estimate still proves uniform convergence, since , but the resulting covariance is not that of the standard Lévy construction. The standard midpoint Brownian bridge variance on an interval of length is . Thus continuity follows under either summable scaling, while Brownian covariance requires the correct variance.
For a continuous semimartingale and a function , Itô's formula isFor Brownian motion , . With , the drift cancels:ConsequentlyThe stochastic-integral representation makes this a local martingale; localization handles unbounded . In fact it is the average of the two positive exponential Brownian martingales and , so it is a true martingale on every finite time interval.
The two-dimensional Itô formula gives the local martingale part of as , with all derivatives evaluated along . Independent Brownian coordinates have brackets and . Hence the quadratic variation isSimilarly, the quadratic covariation with isSufficient pointwise conditions are equal gradient lengths and perpendicular gradients:The Cauchy-Riemann equations , imply both. These are the quadratic covariations of an analytic Brownian image; harmonicity is needed to remove the drift, but the two bracket identities themselves follow just from the displayed derivative relations.
The solution is the continuous Doléans-Dade exponential:Here is the continuous quadratic variation starting from zero, denoted by the angle-bracket notation in the source. If with continuous of finite variation, then .
Set . Its quadratic variation is still . Applying Itô's formula to givesThe initial value is . This verification applies to the full semimartingale, including its finite-variation part.
A uniformly bounded local martingale is a true martingale: stop at a localizing sequence and use dominated convergence in its conditional-expectation identities. Its deterministic bound also gives uniform integrability. The uniformly integrable martingale convergence theorem therefore yields an integrable limit with convergence in andSince , the Radon-Nikodym derivative defines a positive measure of total mass one:The limit can vanish on a set of positive measure, so global equivalence is not required. At each finite time, however, the density is the strictly positive .
Write the integral with an explicit dummy time:On every compact time interval, strict positivity and continuity of make its reciprocal locally bounded; the covariation has locally finite variation. Thus is a well-defined continuous semimartingale.
Apply the Itô product rule. Subtracting a finite-variation process does not change covariation, so . The finite-variation terms cancel:Thus is a local martingale under .
For the transfer step, choose stopping times increasing to the horizon that bound , , reciprocal , and the brackets needed for the stochastic integrals. For each such time , the same product calculation with shows that is a true martingale. The part after is simply the bounded held value times the density martingale. By the Bayes formula for conditional expectation, for ,The stopping times exhaust the horizon also under . Hence is a continuous local martingale, proving this form of the Girsanov theorem without assuming a positive terminal density everywhere.
Conformal invariance of planar Brownian motion means invariance after changing the clock, not preservation of the original speed. If is a conformal bijection and is planar Brownian motion stopped on exiting , putThen has the law of planar Brownian motion started at and run at time , up to the corresponding lifetime. Equivalently, composing with the inverse clock produces ordinary Brownian motion in .
Indeed, the real and imaginary parts of a holomorphic function are harmonic, so Itô's formula gives zero drift. The Cauchy-Riemann equations give equal coordinate brackets and zero cross bracket. The Lévy characterization of multidimensional Brownian motion after time change identifies the image. In particular the harmonic measure of boundary arcs is carried to their conformal images.
Let and . The Möbius transformation sends the semicircle endpoints toAlso . Therefore the left semicircle maps to the unit-circle arc centered at with angular width .
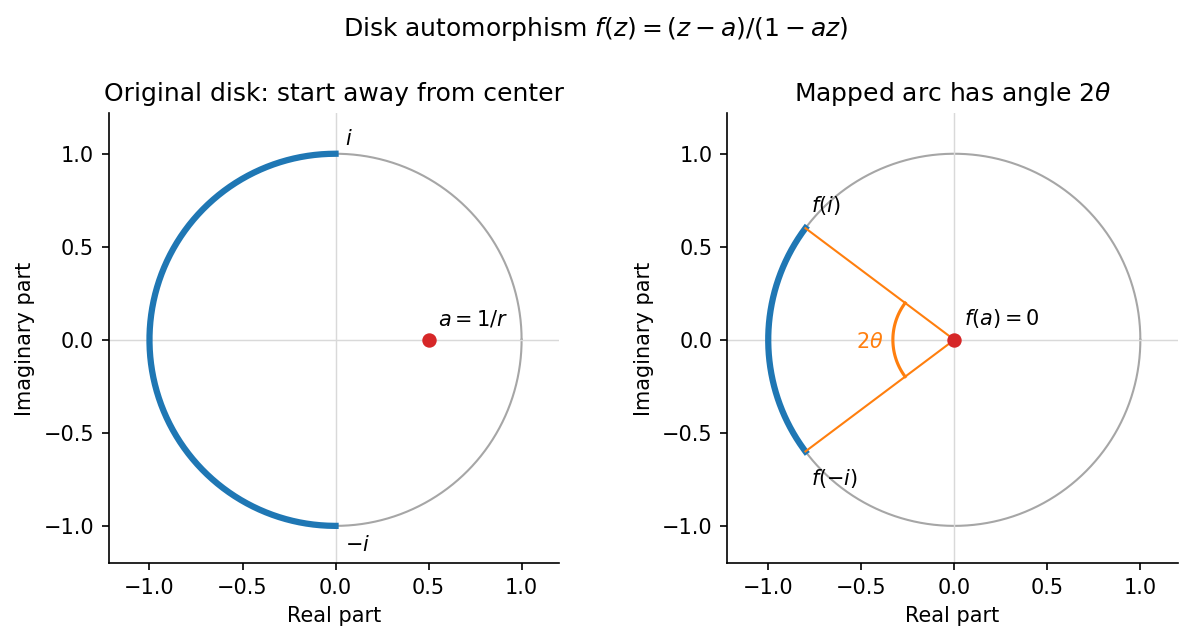
The left semicircle becomes a shorter arc viewed from the mapped starting point
. Details. 
By conformal invariance of harmonic measure, its exit probability from the starting point equals the probability of this image arc for Brownian motion started at zero. Rotational symmetry makes the latter exit angle uniform. ThusFor scaling, if starts at , then is planar Brownian motion started at one. Its unit-disk exit becomes radius- exit, and multiplication by the positive number preserves the sign of the real part. This proves exactly the same formula for .
Continuity and the regularity of zero for a one-dimensional Brownian coordinate make the first contact with the imaginary axis. The Strong Markov property and symmetry of the subsequent real increments imply that reversing those increments after preserves the Brownian law. The imaginary coordinate is unchanged, so is again planar Brownian motion started at one.
Reflection preserves distance to the origin, hence pathwise. On , the path exits through the right semicircle and reflection has not yet acted. On , reflection reverses the sign of the exit real part. ThusThe two circular points on the imaginary axis have zero exit probability, so they cause no extra term. Subtracting proves the reflection identity for Brownian exit from a half-disc requested in the question.
Both processes have the same exit law. With from part (b),The final trigonometric identity follows from for .
A continuous nondecreasing function with has moderate growth if for some fixed and finite ,Iteration and monotonicity then give such an inequality, with a different constant, for every fixed dilation factor. Powers , , are standard examples.
The Burkholder-Davis-Gundy inequalities say that for a real continuous local martingale with and any stopping time , there are positive finite constants , depending only on , such thatHere . Expectations may be infinite, with the inequalities understood by localization. For , these compare the th moment of the running maximum with the th moment of quadratic variation.
Set , , and . On the event , one has and the Brownian path remains in throughout the next time units after .
For Brownian motion started at , let be its first exit time from . The martingale , stopped at , gives . Monotone convergence first proves finite mean exit time, and dominated convergence for the bounded stopped position then givesThus Markov's inequality yields . Remaining in the closed interval for a fixed positive duration has the same probability as avoiding boundary exit: Brownian motion crosses immediately after first hitting an endpoint.
Condition on . The event is measurable there because is a stopping time, and future Brownian increments are independent of this sigma-algebra. The preceding bound is uniform in the current point inside the interval. ThereforeThis is a good-lambda bound for Brownian stopping time and maximum.
Put and . Splitting according to whether , the good-lambda bound for Brownian stopping time and maximum givesIntegrate against the positive measure . The tail integral formula for expectation in Stieltjes form yieldsBy moderate growth, choose with . ThenFix and choose small enough that . Absorb the last term and apply moderate growth once more to the fixed dilation . This provesTo avoid subtracting infinities, perform the argument first for , where Brownian maxima have all finite polynomial moments and moderate growth is at most polynomial, and then use monotone convergence. Applying the Dambis-Dubins-Schwarz theorem transfers this Brownian estimate to continuous local martingales, giving the lower-maximum side of the Burkholder-Davis-Gundy inequalities.
Let , the initial distance from the annulus center, and . The function is harmonic on the annulus, so its value along stopped planar Brownian motion is a local martingale by Itô's formula. It is bounded between and before exit, hence is a true bounded martingale.
By the assumed almost sure finiteness of , continuity, and dominated convergence,where is the inner-boundary exit probability. Solving gives the harmonic measure of an annulus:The two probabilities sum to one, as the exit must lie on one of the two circles.
Suppose first that . Apply part (a) with inner radius and outer radius :Each event implies finite hitting time of the circle, so that hitting probability is one. If , the hitting time is zero. If , it is the exit time from a bounded disk. The martingale , stopped before that exit, gives a finite mean exit-time bound . Thus the asserted hitting time is almost surely finite in this case too.
For alternating visits, choose two closed smaller disks strictly inside the given open disks , so their distance is positive. Define successive first hitting times of . Translation invariance and the Strong Markov property apply the just-proved hitting result from every successive starting point. A countable intersection makes all these times finite almost surely, with the required disk memberships.
These increasing times cannot accumulate at a finite time. On a compact time interval a continuous Brownian path is uniformly continuous, whereas every consecutive visit must cross the fixed positive distance between and . ThereforeThis is the recurrence of planar Brownian motion in neighborhoods; it does not assert that every individual point is hit.
Write and . Since is entire, is a harmonic function, so . The two-dimensional Itô formula givesThe drift vanishes. Stop on successively larger disks to bound the derivatives and define the stochastic integrals without global growth assumptions. ThusThis is the harmonic functions of Brownian motion principle.
Assume that a nonconstant polynomial has no zero. Then is entire. The leading polynomial term makes as , so there. On any remaining compact disk, continuity and absence of zeros bound . Consequently is bounded on the entire plane.
Part (c)(i) makes a bounded local martingale, hence a true bounded martingale. The martingale convergence theorem says it converges almost surely as .
The harmonic function cannot be constant. Otherwise the Cauchy-Riemann equations would make both derivatives of zero, so and then would be constant. Choose points with . Continuity supplies two disjoint disks on which the ranges of are separated by a positive gap. By part (b), the Brownian path visits these disks alternately at times tending to infinity. The corresponding subsequences of then remain separated, contradicting its almost sure convergence.
The zero-free assumption is impossible. Hence
Every nonconstant complex polynomial has a complex root.
This proves the fundamental theorem of algebra using recurrence and martingale convergence, without invoking Liouville's theorem as a prior algebraic shortcut.
Every nonconstant complex polynomial has a complex root.
This proves the fundamental theorem of algebra using recurrence and martingale convergence, without invoking Liouville's theorem as a prior algebraic shortcut.
Articles were limited to the first 100 out of 188 total.
Articles by others on the same topic
There are currently no matching articles.