Topics (355k) Articles (368k) Users (410) Discussions (242) Comments (383) Files (12k) New article
The peaks-over-threshold method fits a generalized Pareto distribution to exceedances of a high threshold and also estimates their frequency. Together these determine tail probabilities and return levels. For dependent observations, threshold exceedances may occur in clusters; declustering of extremes can separate extreme events before fitting a model for independent events.
A deviance residual is the signed square root of an observation's contribution to fitted-model deviance. For a Poisson regression, , with . Its squared sum is the Poisson deviance. Leverage and estimated dispersion can further standardize these residuals; a normal quantile-quantile plot is a diagnostic approximation, not a requirement that count errors have a normal distribution.
For a suitably regular generalized linear model, a residual deviance can be compared approximately with a chi-squared distribution on degrees of freedom to assess fit relative to the saturated model. Sparse or very small expected cell counts can invalidate this reference distribution. A large p-value means no detected lack of fit, not proof of correctness; dependence, wrong mean structure or overdispersion still require diagnostics.
The general linear group over a finite field acts faithfully on the four vectors of , since a matrix fixing all vectors fixes the standard basis. The zero vector is fixed by every element; the induced action on the three nonzero vectors identifies this six-element group with . Swapping the two coordinates fixes and and exchanges the other two vectors, so its four-point permutation is odd. This action therefore embeds the group into with nontrivial composite sign homomorphism.
The pole contour in a Gaussian saddle coalescing with a simple pole changes the multiplier smoothly. For the lower contour, . This follows by integrating and adding the indentation contribution . The transition width is inverse square root of the large parameter; on a Stokes line the multiplier takes half its switched-on value.
Gaussian process classification links latent variables from a Gaussian process to class probabilities. A binary probit regression likelihood is under conditional independence. The posterior distribution of the latent values is not a normal distribution.
A Gaussian process has a mean-square derivative at when its difference quotients converge in L2 space. The mean-square convergence need not give differentiable sample paths. For a centered stationary process with twice continuously differentiable covariance function , the difference quotients are Cauchy in L2 space, since their covariance is a rectangular average of . Their limits form a Gaussian process with covariance function .
For centered multivariate normal distributions represented by vectors with equal corresponding variances and for all distinct indices, for every threshold vector. In particular the supremum of is stochastically smaller than the supremum of . Equal corresponding variances are essential to this formulation. The related Sudakov-Fernique inequality compares expected values of maxima using variances of increments and does not require equal pointwise variances.
For centered multivariate normal distributions, if for every pair, then the displayed comparison holds. For a quick proof, make independent and set . Apply Gaussian integration by parts to . With softmax function weights and , the derivative of is . Since , let . Singular covariance matrices follow by adding identical small independent normal noise to both vectors and taking a limit.
A fractional Brownian motion with Hurst exponent is a centered Gaussian process with the displayed standard covariance function and a continuous modification. Its increment variance is . Some sources omit the factor , multiplying the process by ; the corresponding increment variance is then . Its canonical pseudometric of a Gaussian process is proportional to , which gives finite expected value of its absolute supremum on compact intervals through the Dudley entropy integral.
The canonical distance is the L2 norm of an increment of a Gaussian process. It is a pseudometric, since distinct parameters may represent equal random variables almost surely. Its metric covering number appears in the Dudley entropy integral. For standard fractional Brownian motion, ; a normalization with twice the covariance function multiplies this distance by .
Gaussian process construction from square-summable features by  Codex 0 Created 2026-10-06 Updated 2026-10-14
For independent standard normal variables and at each fixed time, the series defines in . Every finite linear combination is an limit of Gaussian variables and is Gaussian. Thus this constructs a Gaussian process with the Gram covariance kernel . It supplies no sample-path continuity without additional assumptions.
For quadratic dispersion with no interacting anomalous dimension, the thermal and uniform-source scaling eigenvalues are and . The generic homogeneous singular free-energy density has and gap exponent . These Gaussian-model values below the upper critical dimension are not the exponents of an interacting scalar critical point.
A local field combination is a gauge-invariant operator when its gauge representations and charges combine to a singlet. In an effective field theory, such operators may be multiplied by Wilson coefficients and inverse powers of a heavy scale. Multiplication by preserves the invariance of an existing Higgs Yukawa operator.
If a real nonzero field appears in the Lorentzian density and is varied, its algebraic Euler-Lagrange equation is . Hence it imposes the Lorenz gauge condition on real classical fields. Varying gives , including derivatives of . This constrained field theory differs from holding the gauge parameter fixed in a Gaussian functional integral.
A gauge-fixed action supplements a gauge-invariant action with a term imposing the gauge condition and with Faddeev-Popov ghost fields representing the Faddeev-Popov determinant. A local gauge condition gives local differential operators and a local action.
In gauge field theory its standard form is for a fixed null direction . A light-cone gauge uses light-cone coordinates to fix a longitudinal variable, often choosing as the evolution parameter for a relativistic particle phase-space action. Related field gauges set selected minus components to zero when a field has the required gauge invariance. A massive field without that gauge freedom must instead eliminate dependent components through its equations of motion.
The Jacobi identity for gauge covariant derivatives gives . In four dimensions this is , with . It holds independently of the Yang-Mills equations.
In the standard Dirac representation of the gamma matrices, and , so . The transpose signs in that representation are positive for and negative for . The charge-conjugation matrix expresses the basis-independent intertwining relation . Under an arbitrary nonunitary similarity transformation, the Hermitizing matrix changes by inverse Hermitian congruence; it need not equal the transformed temporal gamma matrix.
A Hermitizing matrix for a set of gamma matrices is an invertible Hermitian matrix satisfying . Equivalently, each is Hermitian. It defines a covariant adjoint . If , then has the same property. In a standard Lorentzian Dirac basis, is a conventional choice.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.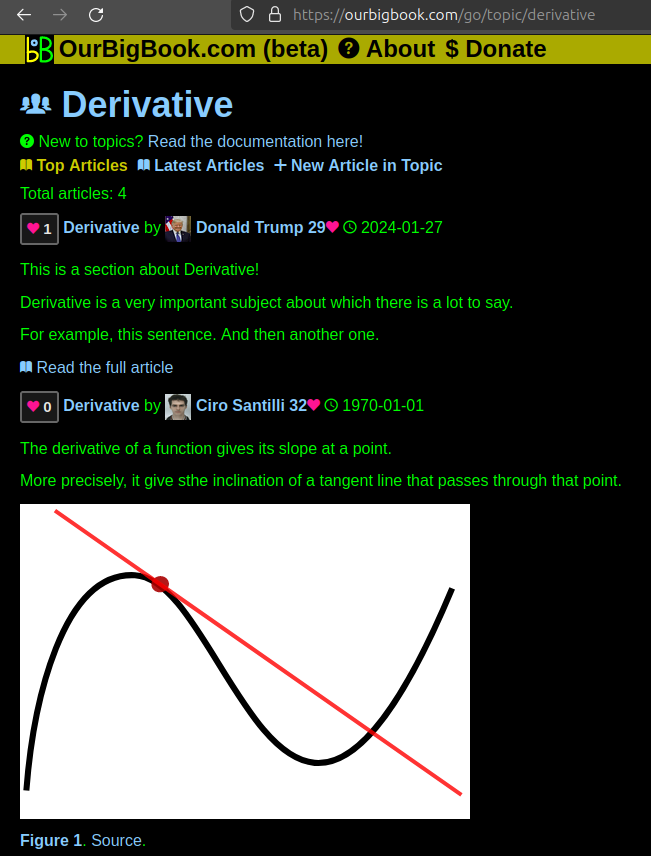
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control
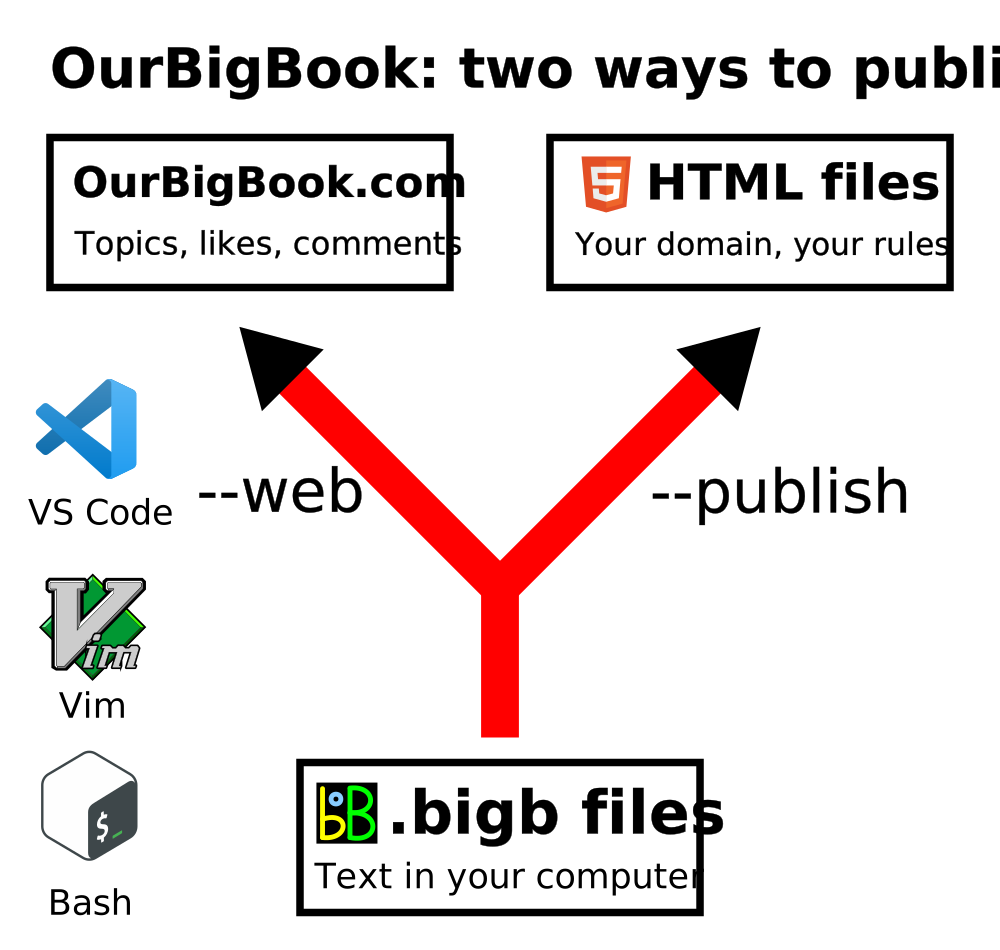
Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.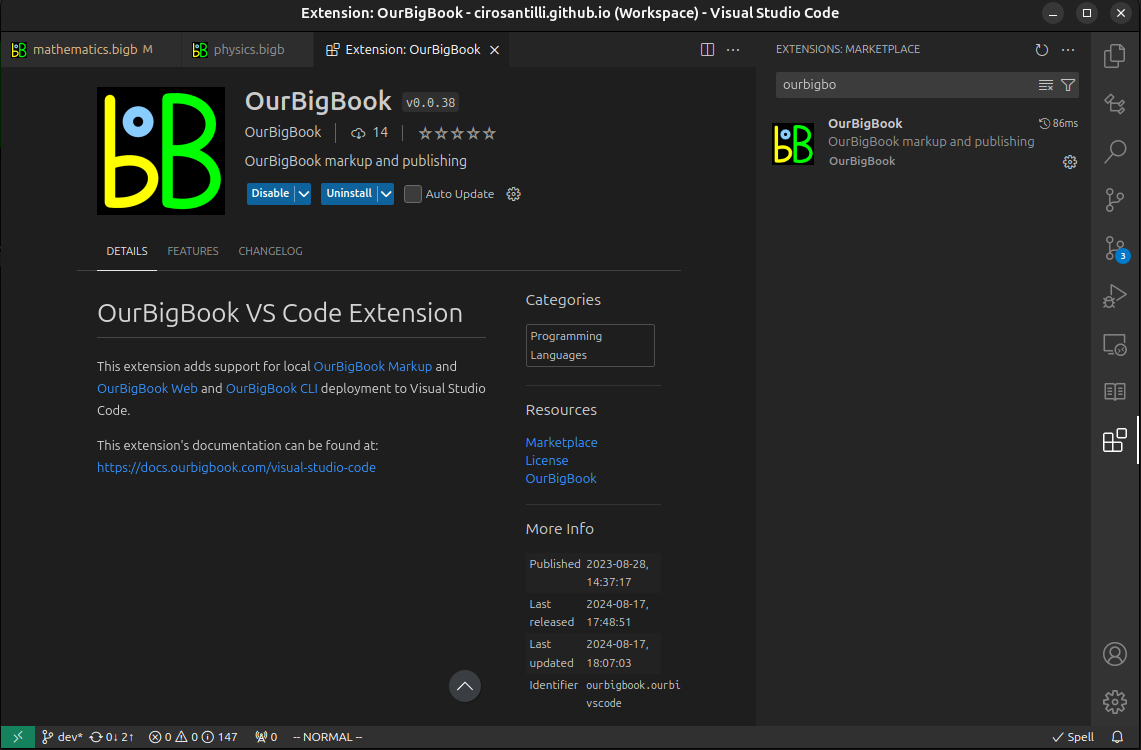
Figure 3. Visual Studio Code extension installation.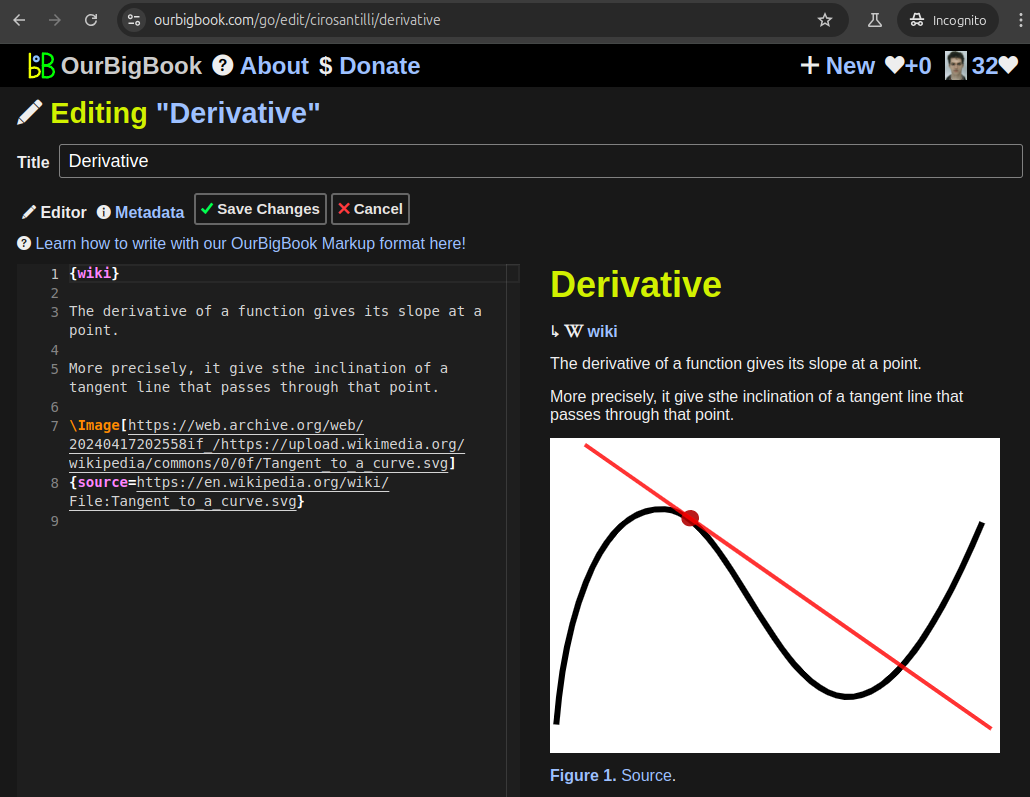
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 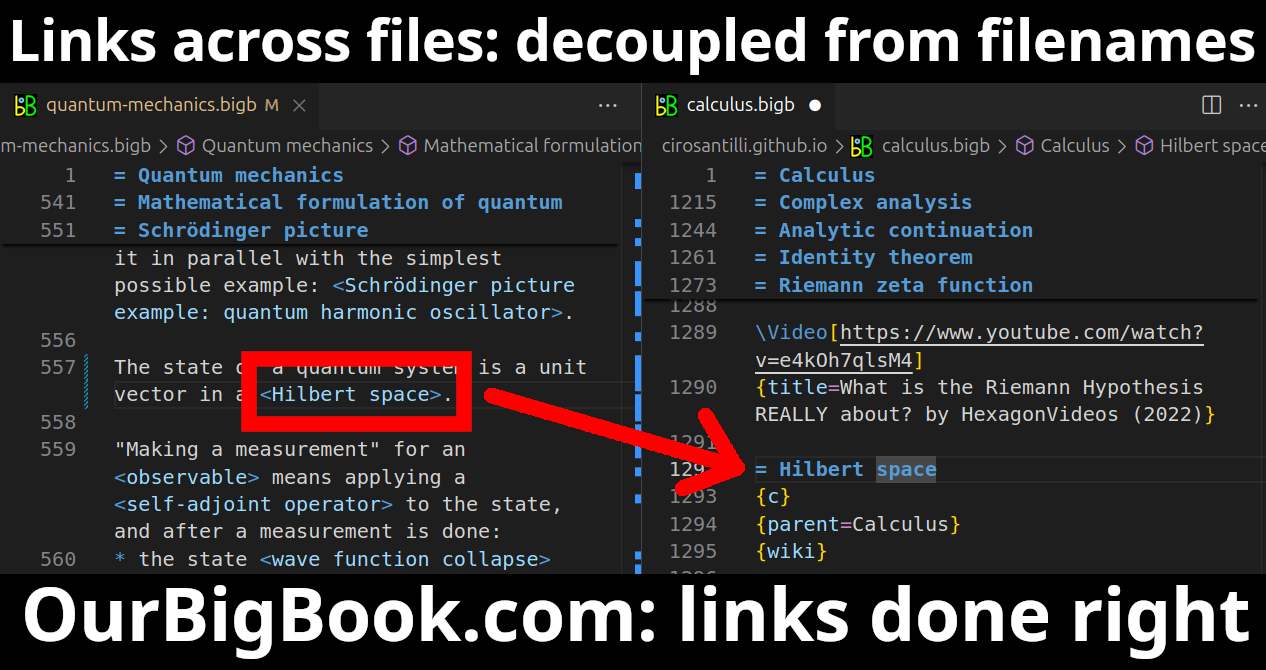
- Infinitely deep tables of contents:
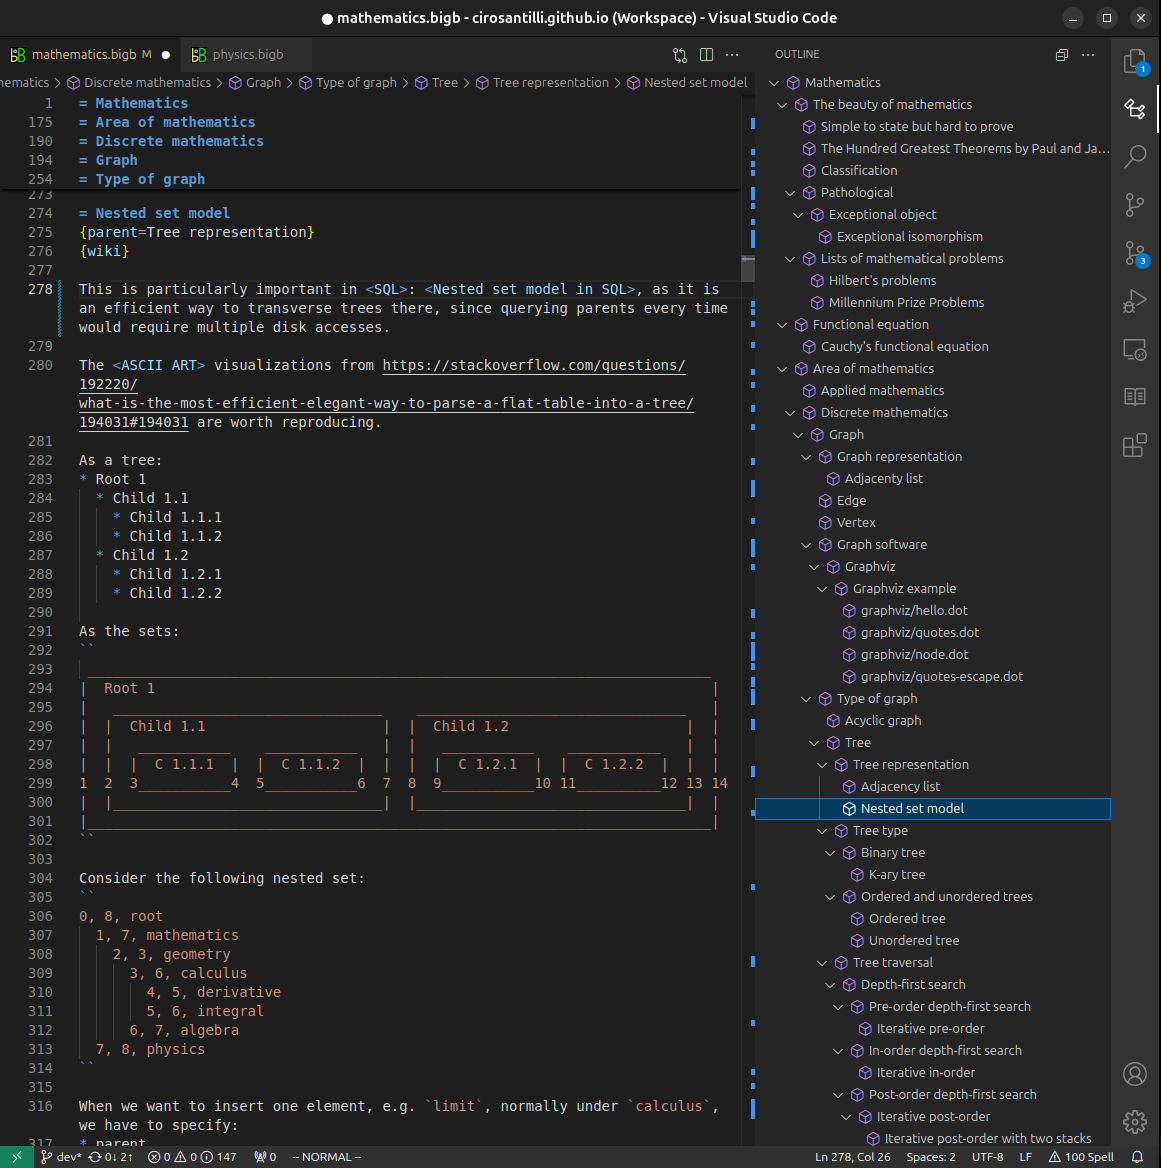
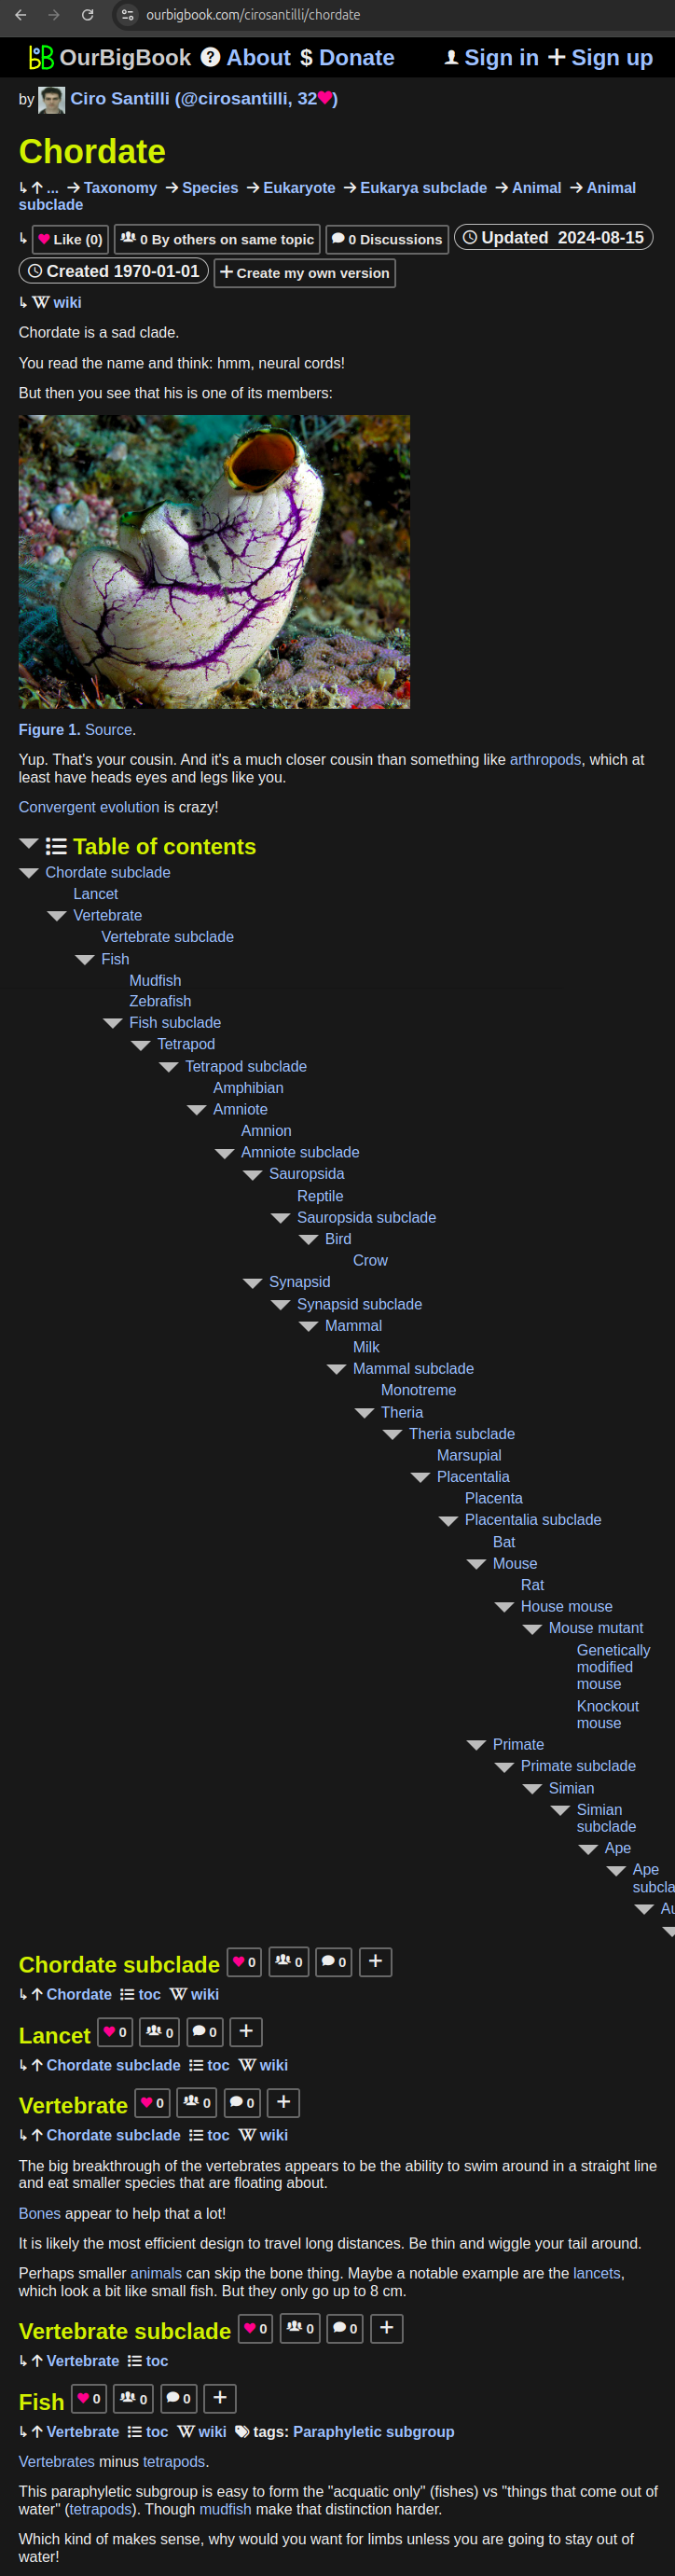
All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact