
A conservative variance estimator bounds an expectation, whereas Wald confidence interval coverage is a probability of a joint event involving the centre and its random width. These are different requirements. In the cited sampling-design result, conservativeness means ; the proposition is not a normal-distribution theorem.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. §3.1, Proposition 2, expected-value inequality
The rare-large-variance counterexample in conservative variance estimator already shows how little that expectation alone controls coverage.A separate original example isolates the distributional issue even when the variance is known exactly. Let , where is zero with probability and is each of and with probability . Symmetry gives , while . Use the deterministic estimate : it is even a samplewise variance upper bound. Nevertheless,because . Accurate variance alone does not supply the normal distribution of a standardized error. NIST likewise distinguishes multiplying a standard uncertainty by a coverage factor from establishing a confidence level without distributional information.[ref]
Guidelines for Evaluating and Expressing the Uncertainty of NIST Measurement Results by Barry N. Taylor and Chris E. Kuyatt. §§6.2–6.3, conditions for approximately 95 percent expanded uncertainty
The tail assumptions needed for conservative Wald coverage may instead come from an asymptotic normal approximation with a consistent standard-error estimate, or from a justified finite-sample model. If only unbiasedness and a samplewise variance upper bound are available, Chebyshev's inequality gives a different, usually wider, confidence interval. One must establish the centre's bias, the variance condition, and the critical-value argument together.
Conservative variance estimator 2026-11-05
A conservative variance estimator, in the finite-sample expectation sense used here, is an estimator of a sampling variance satisfyingfor every statistical parameter value in the stated statistical model. Assume and are finite. In design-based inference, the same definition applies for every permitted fixed population, with the sampling design supplying the randomness. The bias of an estimator is then nonnegative for this target. Aronow and Samii use this expectation criterion for their correction to the Horvitz-Thompson variance estimator when some pairs cannot be sampled together.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. Section3.1, Proposition2: expected corrected variance estimate is at least the true design variance
A samplewise variance upper bound would require the stronger inequality almost surely. An expectation bound allows some estimates below . It does not even require that every realized value be nonnegative; in practice a variance estimate is commonly chosen to be a nonnegative random variable.
One construction starts with an integrable random variable that is an unbiased estimator of and might take negative values. Its positive part satisfies , hence is a conservative variance estimator. The amount of upward bias of an estimator is exactlyThe identity follows from the positive part and negative part decomposition . The Horvitz-Thompson variance estimator supplies a concrete setting in which the untruncated unbiased estimator can be negative.
A deliberately constructed example proves that conservative variance estimation does not guarantee Wald interval coverage. Observe from a normal distribution and an independent from a Bernoulli distribution with success probability . Use and . This nonnegative random variable hasThus it is even an unbiased estimator of the sampling variance. Yet the usual Wald confidence intervalhas coverage probabilitywhere is the standard normal distribution function. When , the interval is the singleton , which contains with probability zero because is a continuous random variable. When , its conditional coverage probability is the bracketed expression. At , overall coverage probability is at most 1 percent, despite the nominal 95 percent rule and the exactly normal centre.
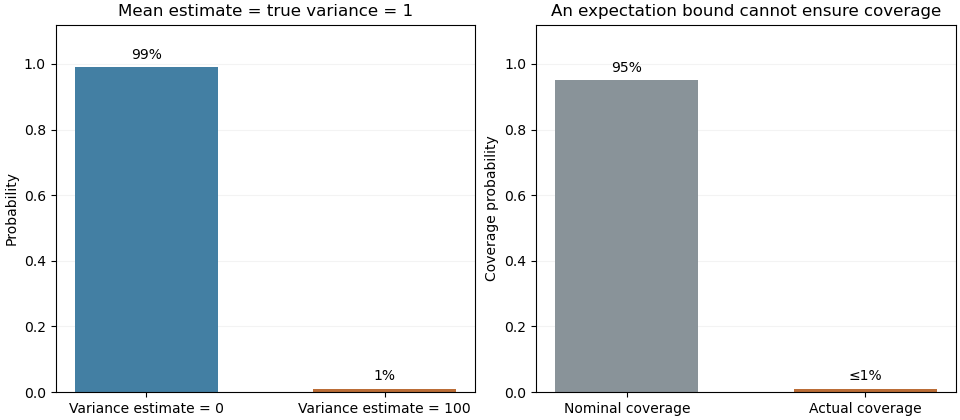
This example concerns the logical strength of the expectation criterion. Controlling the distribution of an estimated standard error, for example through an appropriate consistent estimator in an asymptotic argument, is additional work needed to justify confidence interval coverage.
Cyrus Samii 2026-11-05
Cyrus Samii is a political scientist at New York University whose methodological work concerns quantitative field research and causal inference. His academic biography connects the design of randomized controlled trials to empirical social research.[ref]
Affiliations and Bio by Cyrus Samii. Affiliations and Bio, methodology and field-research description

Cyrus Samii
. Portrait linked as cds_self from Samii's personal academic biography; served directly by the original website.With Peter M. Aronow, Samii studied sampling designs in which every unit can be observed but some pairs can never be observed together. The distinction matters: positive individual inclusion probabilities suffice for an unbiased estimator of a finite population total, whereas the usual Horvitz-Thompson variance estimator also needs pairwise inclusion positivity.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. Section2, conditions1–2 and Sections2.1–2.2, observable and unobservable cross-products
An original two-unit example makes the single-draw variance identifiability obstruction explicit. Fix two unknown population values and choose one index with probabilities . The Horvitz-Thompson estimator is , soAn estimator based only on the selected index and its observed value has expected value of the form . Such an additive expression cannot equal for every pair of real values. Taking the mixed finite difference at gives zero for the additive expression butfor the desired variance. Thus a single draw permits an unbiased estimator of the total but no universally unbiased estimator of its sampling variance. Independent auxiliary randomization cannot repair this: averaging that randomness still gives functions and of the same observed data.
This is a restriction imposed by the observation mechanism, rather than a shortage of algebraic ingenuity. It motivates separating design-based inference about a total from the additional information needed to quantify its uncertainty.
Horvitz-Thompson variance estimator 2026-11-05
The Horvitz-Thompson variance estimator estimates the sampling variance of a Horvitz-Thompson estimator using observed values and known individual and joint inclusion probabilities. It is a random estimate of a fixed design-dependent variance, rather than the variance itself.
Let be an inclusion indicator, , and , with . For fixed population values , write . Bilinearity of covariance givesUnder pairwise inclusion positivity, a sample provides the estimatorThe diagonal terms are included. Taking expected values replaces by 1, proving . This is the pairwise counterpart of inverse-probability expansion for the finite population total.[ref]
An original exact example uses fixed values . Select with probabilities , respectively. Then , and the possible total estimates are . Their expected value is the true total 4, with varianceFor those same samples, the variance estimates are . Their expected value is also 2. In particular, for , the two diagonal contributions are 4 and 2, while the combined off-diagonal contribution is , giving .
Thus this unbiased estimator of variance can be negative in a realized sample. Replacing a negative result by zero changes its expected value; in this example that modification raises the mean estimate to . A positive square root is therefore not always available as a sample standard error from this particular formula. If some , dropping an unobservable cross-product does not preserve the proof; the missing term needs separate analysis.
Pairwise inclusion positivity 2026-11-05
Pairwise inclusion positivity requires every distinct pair of population units to have positive joint inclusion probability under the sampling design:For Horvitz-Thompson variance estimator, the probabilities must also be known, and individual inclusion probabilities must be positive. Each pair can then, at least in principle, contribute an observed product to a pair-expansion estimate. Positivity is not independence: need not equal .[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. Section 2, conditions for measurability; section 2.1, pair expansion
For simple random sampling of distinct labels from , . Consequently, gives pairwise positivity, whereas selecting exactly one label gives positive individual inclusion probabilities but zero probability of ever observing two distinct values together. This distinction separates unbiased total estimation from unbiased estimation of its sampling variance.
An original two-unit proof shows what information is missing. Sample one of two fixed values uniformly. The Horvitz-Thompson estimator is or , and its variance isAny estimator based only on the observed label and value has expected value of the form . Its mixed difference over is zero. The target's mixed difference is insteadNo such estimator can therefore be unbiased for this variance for every possible pair of values. Additional randomization internal to the estimator does not help: conditioning on the observed data still produces functions of this same separated form. This is an information limitation, not division by zero that can be repaired by assigning a convenient numerical convention.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. Sections 1 and 2.2, impossible unbiased recovery of jointly unobservable cross-products
Strict positivity alone also does not guarantee useful precision. A very small produces a large inverse-probability multiplier on a rare observed pair. Designing a usable survey therefore requires attention to both observability and the resulting sampling variance.
Peter M. Aronow 2026-11-05
Peter M. Aronow develops statistical methods for causal inference, particularly design-based inference. Yale's institutional biography identifies research on complex experimental designs, network settings and incomplete survey data alongside appointments spanning political science and statistics.[ref]
Peter M. Aronow profile by Yale School of Public Health. Titles and Biography, design-based methodological research
His joint work with Cyrus Samii studies how to estimate sampling variance when a sampling design never observes some pairs together. A missing product cannot simply be deleted from the population variance formula: doing so can produce either sign of bias. Their construction uses Young inequality to bound unobserved products by individually estimable powers and obtain a conservative variance estimator.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. Section2.2, Proposition1; Section3.1, Proposition2; Section3.2, quadratic special case
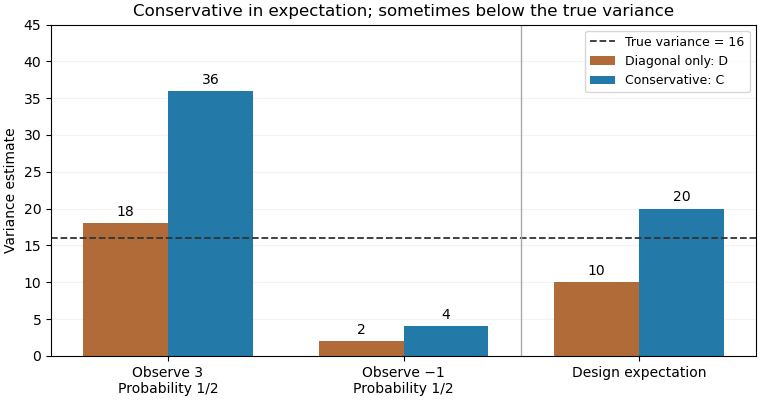
For an original exact illustration, choose one of two fixed values with equal probabilities. As in the single-draw variance identifiability obstruction, the Horvitz-Thompson estimator has true variance . Retaining only diagonal contributions gives , withOpposite signs therefore produce downward bias. The elementary inequality , obtained from , instead givesConsequently is a conservative variance estimator for this stipulated sampling design; its excess in expected value is exactly .
With , the true variance is16. The two possible values of are18 and2, averaging10; those of are36 and4, averaging20. Although , a realized value of can be below16. Conservativeness here is an expectation inequality, rather than a bound for every sample. By itself it also does not prove a specified confidence interval coverage probability.


Samplewise variance upper bound 2026-11-05
A samplewise variance upper bound is a nonnegative statistic satisfying , where is the fixed sampling variance at parameter . It controls each realized value outside a probability-zero exceptional set. This implies the expected-value condition for a conservative variance estimator when the expectation exists; the converse fails, as the parent article's counterexample shows. The primary sampling-design definition only asserts the weaker expectation condition.[ref]
Suppose is an unbiased estimator with finite variance, and let . Then Chebyshev's inequality and the samplewise comparison giveNo independence between and the centre is needed. If , unbiasedness makes the centre equal to almost surely, so coverage still holds. This proves confidence bounds from a samplewise variance bound; it does not justify replacing by a normal distribution critical value.
For an original bounded-data example, take independent and identically distributed measurements known to lie in , and estimate their population mean by the sample mean. With , the inequality givesThe deterministic choice is a samplewise variance upper bound for every such population. Thus covers with probability at least . The radius shows the price of distribution-free reasoning; the estimate may be much wider than a model-specific confidence interval.
The single-draw variance identifiability obstruction is the inability, for an unrestricted finite population, to construct a universally design-unbiased estimate of a total estimator's variance from just one observed unit. The estimator can estimate the total unbiasedly while the required cross-products for estimating its sampling variance are never jointly observed. This is an obstruction to the stated one-draw estimation problem, not a claim that a parameter can never be identified from repeated independent samples.
An original two-unit proof makes the distinction exact. Sample label or2 with equal probability and observe only . The Horvitz-Thompson estimator of the finite population total is . Its expectation is , and its design variance isSuppose a proposed variance estimate returns after observing unit1 and after observing unit2. Unbiasedness for every pair would requireThe left side is additive in the two unknown values, while the right side contains an unobserved product.
To prove impossibility without smoothness assumptions, evaluate both sides at . Every additive function has rectangular contrast . The required variance has contrast . The contradiction rules out such an unbiased estimator. Independent auxiliary randomization does not help: averaging it out merely replaces each by another function of the same single observed value.
Here the individual inclusion probabilities are positive, but the joint inclusion probability for distinct units is zero. The usual Horvitz-Thompson variance estimator needs pairwise inclusion positivity to turn sample cross-products into unbiased population cross-product estimates. The primary analysis of zero pairwise probabilities identifies precisely these missing terms.[ref]
Conservative variance estimation for sampling designs with zero pairwise inclusion probabilities by Peter M. Aronow and Cyrus Samii. §2.1, pair-expansion variance estimator; §2.2 and Proposition1, missing products under zero pairwise probabilities
Extra information can change the problem: observing suitable pairs, imposing a justified population relation, or accepting a model-based or conservative estimate uses assumptions absent from the proof. Observing one value also does not prevent writing a biased variance estimate. What fails is a single-draw unbiased estimator valid for every unrestricted population, even though the total estimator itself remains unbiased.