The intensity measure of a point process is its expected counting measure:It may take the value .[ref]
Lectures on the Poisson Process by Günter Last and others. Section 2.2, Definition 2.5, printed p. 12: intensity as the expected counting measure
Countable additivity follows by applying the monotone convergence theorem to the counts of finite unions of pairwise disjoint observation windows. If is locally finite and absolutely continuous with respect to Lebesgue measure, its Radon-Nikodym derivative is the intensity function of a point process :This is an expected number per unit volume, not a probability density function for a randomly selected point. For example, a single deterministic point has , a Dirac measure, and no Lebesgue measure density. The density representation requires its own assumption.[ref]Spatial Point Processes and their Applications. Section 2.1, Definitions 2.1-2.2, printed pp. 26-27: expected counts and intensity functions
For a bounded Borel set , , but local finiteness alone does not ensure that this expected value is finite. Conversely, implies almost surely, even when is unbounded. A constant finite intensity function of a point process on all of has infinite total intensity measure, although every bounded window has finite expected value.
Here is an explicit example even within simple point processes. Let be a positive integer with probability mass function . The telescoping series sums to one, is finite almost surely, but . Conditional on , sample independent points with the uniform distribution on . The resulting point process has finitely many distinct points almost surely, while . Thus finite counts in each realization and finite mean counts are separate requirements; local finiteness of the intensity measure is an integrability assumption.
The same intensity measure can belong to very different point processes. A Poisson point process with a locally finite intensity measure adds two requirements: each finite-intensity window count has the Poisson distribution of mean , and counts in pairwise disjoint observation windows are mutually independent. These requirements determine its probability law; they do not follow from the formula for .[ref]
Lectures on the Poisson Process by Günter Last and others. Section 3.1, Definition 3.1 and Proposition 3.2, printed pp. 19-20: Poisson count laws, independence, and uniqueness
A randomly shifted lattice point process, a unit-rate Poisson point process, and the shared random rate gives dependent point counts construction all satisfy on the real line. Nevertheless, their counts in have respectively variance zero, one, and two. Counts in the disjoint observation windows and have respectively covariance , zero, and . These exact calculations show why measuring mean density cannot identify a spacing or statistical dependence model.
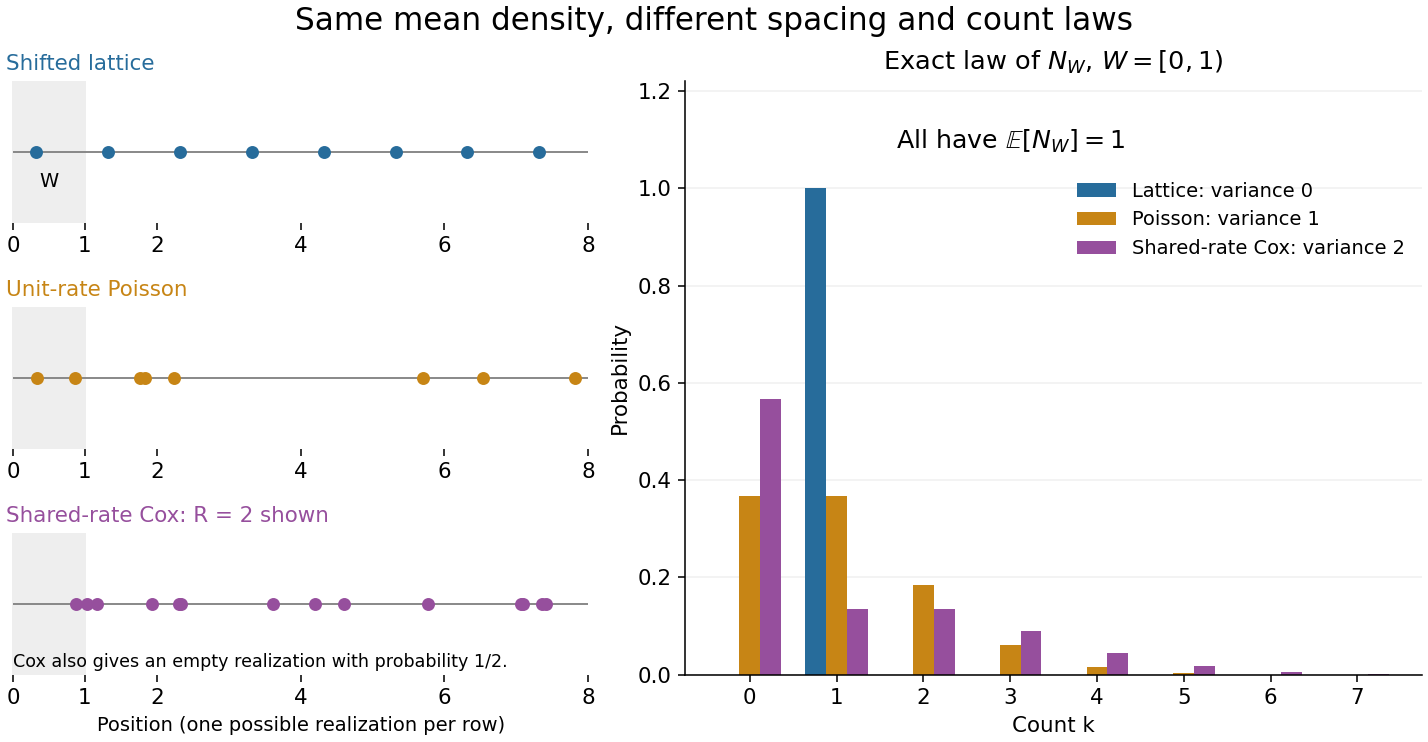
Equal intensity permits regular spacing, Poisson counts, and shared-rate dependence
. All three laws have intensity measure . Left: illustrative realizations of a randomly shifted lattice point process, a unit-rate Poisson point process, and the shared random rate gives dependent point counts construction conditional on rate two; the latter also has a completely empty outcome with probability . Right: exact probability mass functions of the count in , with the axis displayed through seven. Equal expected values of one coexist with variances zero, one, and two. Realizations illustrate spacing; the bars describe laws, not frequencies estimated from those realizations. Details.
Let have the uniform distribution on and place a point at every , . This is a simple point process, locally finite, and a stationary point process: a translation only changes the phase modulo one, preserving its uniform distribution. For every Borel set , the Tonelli theorem givesIts consecutive points are exactly one unit apart, despite having the same intensity measure as a unit-rate Poisson point process. This is the one-dimensional translated-grid construction.[ref]
Spatial Point Processes and their Applications. Section 2.1, Example 2.3, printed pp. 26-27: randomly translated grids have constant intensity
Every half-open interval of length one contains exactly one point. For and , , each count has the Bernoulli distribution with parameter , andMore generally, an interval of length , with a nonnegative integer and , contains or points with probabilities and . Its count variance is , while a unit-rate Poisson point process has count variance .
Articles by others on the same topic
There are currently no matching articles.