Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 2 d Solution by  Codex 0 Created 2026-10-03 Updated 2026-10-14
The Brownian reflection principle and Brownian scaling givewhere has the standard normal distribution. Combine part (c) with the allowed Gaussian tail bound to obtainThis is the Brownian martingale proof of Gaussian concentration. It proves the intended Gaussian concentration inequality. The denominator printed in the initial bound is , whereas the gradient hypothesis and part (c) give . The stronger printed bound is false in general. For a concrete counterexample, take , , and . At ,where the first strict inequality follows by integrating the decreasing normal density over . The rightmost term is the printed bound. Thus the square on is a necessary source correction, rather than a change of proof technique.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 2 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Let . The triangle inequality for the conditional average givesThe independent coordinate Brownian motions have zero cross-variation, so the quadratic variation of a stochastic integral givesThe Dambis-Dubins-Schwarz theorem says that a continuous local martingale starting at zero whose quadratic variation diverges admits a Brownian motion , with the inverse-clock filtration, such that . If the total clock is finite, one may enlarge the probability space and append independent Brownian motion after the clock terminates. This gives the same identity up to the original lifetime.
Apply this theorem to . The clock bound implies the event inclusionThe latter event is contained in the union of the upper and lower crossing events. Symmetry of Brownian motion givesThis uses only an event inclusion; independence between the Brownian motion and its random clock is neither assumed nor needed.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 2 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Let for . Differentiating the Brownian transition semigroup in the spatial variables is justified by the bounded gradient and givesThe heat equation for this semigroup is the backward equation . Applying the multidimensional Itô formula yieldsThe finite-variation term vanishes. ThusInitially this calculation holds on . The vector of stochastic integral coefficients has norm at most , so the Itô isometry lets the integrals extend to time one. Also in by the Lipschitz function bound and continuity of Brownian motion. The same representation therefore holds on the entire interval.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 2 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The gradient bound makes a Lipschitz function, with , so its value at a Gaussian random variable is integrable and square integrable. The future Brownian increment is independent of and has distribution . Conditioning on the current location therefore givesThis is the Markov property expressed through the Brownian transition semigroup. In particular and .
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 1 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14No quadratic variation argument is needed. For deterministic , the martingale property and square integrability giveConsequentlyApply this identity separately to each consecutive grid increment. The second moments telescope, givingThis uniform bound follows directly from martingale-difference orthogonality, including the final interval specified by the ceiling.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 1 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Fix the specified time . With the path modulus on as above, comparison of increment powers now givesThe hypothesis makes the second factor eventually bounded almost surely, while the first tends to zero almost surely because . Thus the squared-increment sums tend to zero almost surely. They also converge in probability to the quadratic variation , so uniqueness of the limit in probability implies almost surely.
The quadratic variation is nondecreasing, hence it vanishes throughout . To see explicitly that the continuous local martingale must then be constant, localize it to square-integrable stopped martingales. The Itô isometry givesRemove the localization, apply the conclusion at every rational , and use continuity. Since , this provesThus is indistinguishable from the zero process on that interval. This is the subquadratic case of dyadic power variation of a continuous local martingale.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 1 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Fix . By uniform continuity of each path of the continuous local martingale on , its modulustends to zero almost surely. For every , comparison of powers of each increment givesThe squared-increment sum converges in probability to , by the dyadic definition of quadratic variation. Including the last full grid interval instead of the last partial interval changes that sum by a quantity bounded by , so the ceiling convention has the same limit. In particular these squared-increment sums are bounded in probability.
Since , a quantity tending to zero almost surely multiplied by a family bounded in probability tends to zero in probability. HenceThis is uniform convergence on compacts in probability, and proves the superquadratic case of dyadic power variation of a continuous local martingale.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 29 1 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Set and . Replace the last sampled value by , and call the resulting absolute-increment sum . This is a sum over a genuine partition of an interval of , andby right continuity. This is the dyadic approximation of total variation. Let be the total variation of a function on , allowing . Every is at most . Conversely, take any finite partition of an interval of . Approximate its interior points from the right by dyadic grid points, retaining the endpoint . For large these approximating points remain distinct, and right continuity makes their absolute-increment sum converge to that of the original partition. The triangle inequality makes at least this selected sum. Taking the supremum over all partitions provesThe limit is the total-variation function; for locally finite variation it is the total-variation process.
There is a missing hypothesis in the assertion about being càdlàg. A general càdlàg function can have infinite total variation of a function arbitrarily close to zero. For example,is continuous. At the successive points its values alternate in sign with magnitude . The variation along these points dominates a divergent harmonic series. Thus for every , but , so even extended-valued right continuity fails at zero.
The correct càdlàg conclusion holds when has finite variation on every compact interval. Indeed is then finite and nondecreasing, so it has finite left limits. To prove right continuity at , fix and choose a partition of whose sum is within of its variation. If lies before the first interior partition point, changing the first endpoint from to changes that sum by at most . Additivity of total variation of a function therefore givesLet and then . This proves right continuity. This proves càdlàg regularity of finite total variation. Under that qualification, the jump formula isIf the variation is infinite, a difference of two infinite variation values is not a defined jump.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 6 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The printed assertion is false in the usual pointwise meaning of nowhere continuous. The original PDF explicitly has this wording. Part (c) proves that has nondecreasing càdlàg paths; such paths can have only countably many discontinuities, so they are continuous at uncountably many levels. We prove the precise valid statement:For countability, fix a path and a bounded level interval . A discontinuity is a jump , since right continuity is already known. The sum of any finite family of these jumps is at most . Thus there are only finitely many jumps of size at least , for each positive integer . Taking the countable union over and over integer proves that all discontinuities form a countable set.
For density, work on the common probability-one event of Brownian continuity, unboundedness above, and the conclusion of part (a). The inverse is strictly increasing: for every level , path continuity gives , so two distinct levels cannot have the same passage time. Suppose there were a nonempty open level interval on which had no discontinuity. Choose inside it. Its restriction to would be continuous and strictly increasing, hence onto . For every time in this positive-length interval there would be a unique with , and then . Increasing increases , so the Brownian path would be nondecreasing throughout . This contradicts part (a).
Therefore every open level interval contains a jump. This establishes Countable dense jumps of the Brownian first-passage subordinator, and in particular rules out any interval on which is continuous throughout. It does not rule out continuity at an individual level. In fact, for every fixed deterministic , part (b) gives almost surely, so is almost surely continuous at that specified level. Its dense discontinuities occur at random levels.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 6 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Under the path convention used here, a real Lévy process starts at zero, has independent increments and stationary increments, is stochastically continuous, and has càdlàg paths almost surely. We verify all four requirements for .
The immediate positive excursions proved in part (b) give . For a deterministic , is an almost-surely finite stopping time, and continuity gives . The Strong Markov property implies that is a fresh Brownian motion independent of the information up to . For ,No crossing of could have occurred before . The increment thus has the same law as and is independent of the past. Apply this successively at a finite increasing sequence of deterministic levels to prove stationary independent increments.
For and , part (b) and reflection giveHence in probability. Stationarity of the increments gives stochastic continuity at every level, from either side where defined.
For path regularity, on a single probability-one event the Brownian running maximum is continuous, nondecreasing and unbounded, andThis inverse is nondecreasing. If , then . For any , some has ; for all sufficiently large , , so . Thus , proving right continuity at every level simultaneously. On each bounded level interval it is bounded by the finite value at a larger integer level. Monotonicity then gives finite left limits. ThereforeThe Brownian first-passage subordinator is the level-indexed increasing process, rather than a process indexed by the original Brownian time.
For , the inverse relations for a continuous running maximum areFor example, if then ; while for , and any has . Taking limits gives . Similarly for , and a crossing of any level strictly above before a given bounds from above for sufficiently close to . This proves . These are the non-strict inverse of a continuous nondecreasing function identities.
At the random level in part (b), , so fails right continuity almost surely. Thus it is not a Lévy process under the stated càdlàg-path convention. It does have the same finite-dimensional distributions and stochastic continuity as , so definitions of a Lévy process that require only the increment and stochastic-continuity properties would call a Lévy process with a càdlàg modification. The reason for excluding the particular version here is its path regularity.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 6 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14For each deterministic , the Brownian reflection principle givesso is finite almost surely; . Here is the standard normal cumulative distribution function. The same reflection formula at levels decreasing to zero gives for every . Taking a countable intersection over shows that Brownian motion exceeds zero arbitrarily soon after its start.
By the Strong Markov property at the finite stopping time , the process is fresh standard Brownian motion. It therefore exceeds zero arbitrarily soon. Path continuity gives , and the preceding fact gives the reverse inequality. ConsequentlyThe exceptional event may depend on ; this does not imply simultaneous equality for all levels.
To exhibit the difference, set , a random level. The reflection formula gives almost surely. Also almost surely: if were the maximum, the reversed increment process would be nonnegative throughout . This process has the law of standard Brownian motion, whose probability of staying nonnegative from zero is zero by reflection and symmetry. The level is attained at some time strictly before one, so . It is not exceeded by time one, and continuity with gives a further positive interval before it can be exceeded. ThusAll these passage times exist simultaneously on the probability-one event where the Brownian path is continuous and unbounded above, obtained by intersecting the finite-hitting events for positive integer levels.
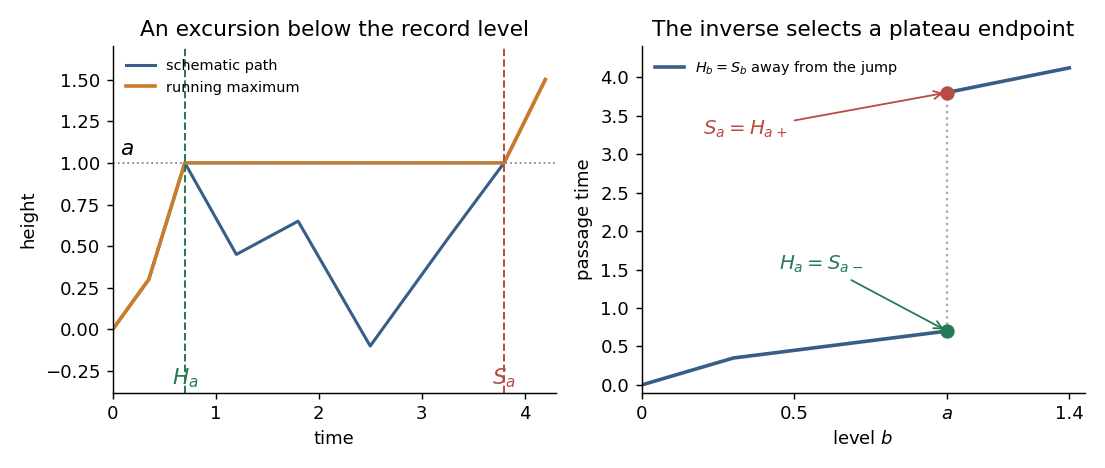
The illustration shows the pathwise mechanism. The Brownian running maximum stays flat during an excursion below an attained record. The non-strict inverse chooses the beginning of that plateau, while the strict generalized inverse of a nondecreasing function chooses its end. The curve is a schematic of this mechanism, not a claim of piecewise linear Brownian paths. The fixed-level equalities give the modification of a stochastic process relation, while the random-level discrepancy rules out indistinguishability of stochastic processes. This is fixed-level versus simultaneous Brownian passage-time equality.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 6 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Use standard Brownian motion, started at . Fix , and divide into equal subintervals. Its Brownian increments are independent centred normal random variables with strictly positive variance, so each is nonnegative with probability . A nondecreasing path on the entire interval must have every one of these increments nonnegative. Hencefor every , and therefore this probability is zero.
There are only countably many pairs of rational endpoints . Take the union of the corresponding null events. Every interval of positive length, even one selected depending on the path, contains an interval with rational endpoints. Outside that single null event no such interval can be nondecreasing. ThusApplying the same argument to also rules out nonincreasing intervals, the full nowhere monotonicity of Brownian motion property.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 5 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Again suppose is a nonconstant polynomial without a complex zero, and put . As proved in part (c), is an entire holomorphic function with at infinity. Choose and then a disk large enough that outside it. On the closed disk, attains its maximum by the extreme value theorem, and that maximum is positive and greater than every value outside the disk. It is therefore a global, and in particular local, maximum on .
Part (b)(ii) forces to be constant. A nonzero constant reciprocal makes constant, a contradiction. Hence . Equivalently one can minimize globally and apply the maximum modulus principle to its reciprocal if that minimum is positive. This supplies the second proof of the fundamental theorem of algebra using part (b).
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 5 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Suppose a nonconstant polynomial has no zero in . Its reciprocal is then an entire holomorphic function. If is the degree and its leading coefficient, division by shows as . Hence , so . Continuity on compact disks now makes bounded on all of .
Fix and let be standard planar Brownian motion started at zero. By part (a) and Itô formula, both components of are local martingales. Since is bounded, they are true martingales, andFor , choose such that whenever , and write . The two-dimensional Gaussian density of is bounded by , soConsequentlyLet , then , to obtain . This is impossible for . ThusThis Brownian proof of the fundamental theorem of algebra uses only harmonicity, the bounded-martingale property and the spreading Gaussian transition density. It does not use either maximum principle from part (b), nor does it incorrectly assume that planar Brownian motion hits a specified point.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 5 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Write . The prescribed complex-linear differential is exactly the Cauchy-Riemann equationsA holomorphic function is smooth, as follows locally from its Cauchy integral formula, so its mixed second partial derivatives commute. Differentiating the two equations givesand, rewriting them as , ,Thus : both components are harmonic functions. Here , the sign convention used for the Brownian generator .
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 4 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Let be the average over all coordinate tuples in part (a), and the distinct-tuple average in part (b). Every product summand lies in . A proportion , where , of all tuples have distinct coordinates. Thuswhere is the average over the remaining tuples. If there are no remaining tuples, the error is zero. Hence .
For independent uniform choices from indices, any particular pair coincides with probability . A union bound over the pairs givesThis deterministic sampling with and without replacement comparison for bounded products is the needed link between the two averages.
Part (a) identifies the almost-sure limit of as . By part (b) and the reverse martingale convergence theorem, converges almost surely to . Their difference vanishes, soThis is precisely conditional independence. Exchangeability also makes the single-coordinate conditional laws identical, by applying a coordinate transposition and testing against invariant events. The result is the De Finetti theorem, established here by finite symmetrization and the vanishing collision fraction.
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 4 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Put and . Average over all permutations of the first coordinates, as justified in part (a). For any prescribed ordered tuple of distinct images , exactly permutations produce that tuple. ThereforeThe denominator is the falling factorial , with exactly factors. The sum must be over ordered distinct tuples: its th coordinate is attached to , and these sets need not be equal. This is the finite-sample version of symmetrization as conditional expectation.
The original PDF, as well as the TeX, prints the final factor as . That is an off-by-one error: it must be . With every , the conditional expectation is one and the numerator counts exactly ordered distinct tuples. This forces the normalization above and immediately detects the printed error. Interpreting the sum as unordered subsets would likewise give the wrong normalization and would lose the assignments to the different .
Past exam of the mathematics course of the University of Cambridge 2010 iii Paper 28 4 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Let permute coordinates , fixing the later coordinates. For any integrable random variable , its group averageis invariant under this group, hence -measurable. If , invariance of and measure preservation of each give . Thus satisfies the integral definition of . This proves symmetrization as conditional expectation.
Apply it to for . Under a uniform permutation of coordinates, its selected coordinate is uniform among all of them, soThe reverse martingale convergence theorem says that, for decreasing sigma-algebras and an integrable , these conditional expectations converge almost surely and in to . Here , because every finitely supported permutation belongs to one of the finite groups. ThereforeIntersect these probability-one events for the finitely many and multiply the limits. Expanding the product of finite sums givesThe sum here includes repeated indices. No independence of the original coordinates was assumed; exchangeability and reverse conditional-expectation convergence are precisely what replaced it.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact