Addition combines two numbers into their sum. For natural numbers, joining disjoint collections of sizes gives a collection of size . On a number line, adding shifts a starting position by : rightward when and leftward when .
Starting at and adding reaches . Starting there and adding returns to , because . Additive inverses turn this return move into an algebraic rule. With real numbers, addition is commutative and associative: exchanging two shifts or grouping several shifts differently leaves the final position unchanged.
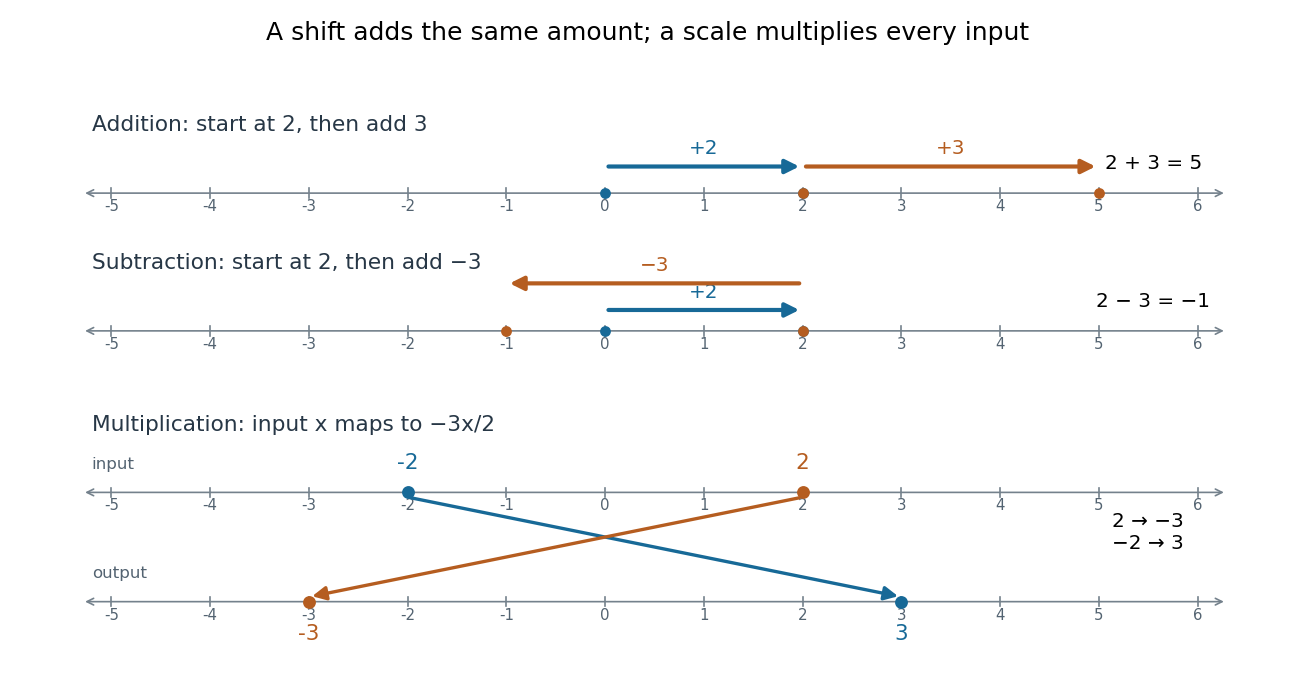
Addition shifts positions on a number line, while a negative multiplication factor changes both scale and direction
. Details. The bottom panel applies . Input becomes , and input becomes . Multiplication by a negative real number rescales distances from zero and reverses direction, giving a reflection in mathematics as well as a scale change. This is a different operation from shifting every input by one fixed amount.
Uniform approximation minimizes the supremum norm of the difference between a target function and an approximant.
The error is measured uniformly over the domain using the supremum norm. A sequence of approximants whose uniform error tends to zero converges by uniform convergence; the optimization problem and the convergence notion are distinct.
Calculus of variations finds stationary points of functionals, often among functions or regular curves.
Distribution theory extends functions to continuous linear functionals on test functions, allowing generalized derivatives and point sources.
A partial differential equation relates an unknown function of several independent variables to its partial derivatives. For , the notation means changing time while holding position fixed; measures how its spatial slope changes. Unlike an ordinary differential equation, a partial differential equation can describe an entire evolving profile rather than a single trajectory.
The heat equation smooths spatial variations, the transport equation moves them, and Laplace's equation describes a spatial equilibrium. Here is a diffusivity, is a velocity, and is the Laplacian. The periodic heat and transport comparison makes the difference visible using identical initial conditions.
A partial differential equation usually supplies a local rule rather than a complete answer. For example, every satisfies the heat equation with zero PDE source term; data select which profile is relevant. A complete problem specifies its domain of a function, coefficients, initial conditions, boundary conditions, and meaning of solution of a partial differential equation. A well-posed problem has existence, uniqueness, and continuous dependence on initial data in stated spaces; the equation alone guarantees none of these.[ref]
Real analysis studies limits, continuity, differentiation, integration, and convergence of sequences and functions taking values in the real numbers. Its central question is how finite approximations determine an exact answer: what does an arbitrarily small error mean, and which operations respect that error? A derivative is a limit of quotients, while a Riemann integral is obtained from increasingly fine Riemann sums. Both need conditions that make the answer independent of the approximations chosen.
Two organizing ideas are completeness of the real numbers, which ensures that suitable approximations have a destination, and uniform convergence, which controls approximation error over an entire domain. Pointwise convergence supplies separate guarantees at separate inputs; uniform convergence supplies one guarantee for all inputs. This distinction explains why replacing an approximating function by its limit can preserve continuity or integrals under appropriate hypotheses, yet fail without them.
For historical context, Cauchy's 1821 Cours d'analyse explicitly discusses convergence of series. Its Note VII treats double series and compares summing by rows and by columns under stated convergence assumptions: controlling an infinite process was already a concrete problem. This is historical context for questions about limits, rather than an attribution of the modern definitions below. [ref]
https://www.e-rara.ch/download/pdf/8543076.pdf. Cauchy, Cours d'analyse (1821), Note VII, pp. 537–539, original scan
. Uniqueness theorem for ordinary differential equations by  Codex 0 Created 2026-09-24 Updated 2026-09-24
Let be a piecewise smooth contour forming a simple closed curve, positively oriented: travel counterclockwise, with the interior on the left. Suppose is holomorphic on an open set containing and its interior, except at finitely many isolated singularities strictly inside. ThenNo isolated singularity may lie on : the ordinary contour integral must be defined there. Reversing the direction of the contour reverses the sign of the answer. The theorem applies to essential singularities as well as poles. [ref]
Return to . A counterclockwise circle encloses both simple poles, soYet is nonzero everywhere it is defined. A zero contour integral does not imply a zero function, or even absence of poles: the enclosed residues can cancel. By contrast, the counterclockwise circle encloses only , givingThe picture compares these two selections. Changing the shape of a contour while keeping the same enclosed poles leaves the contour integral unchanged, provided the contour deformation stays where is holomorphic.
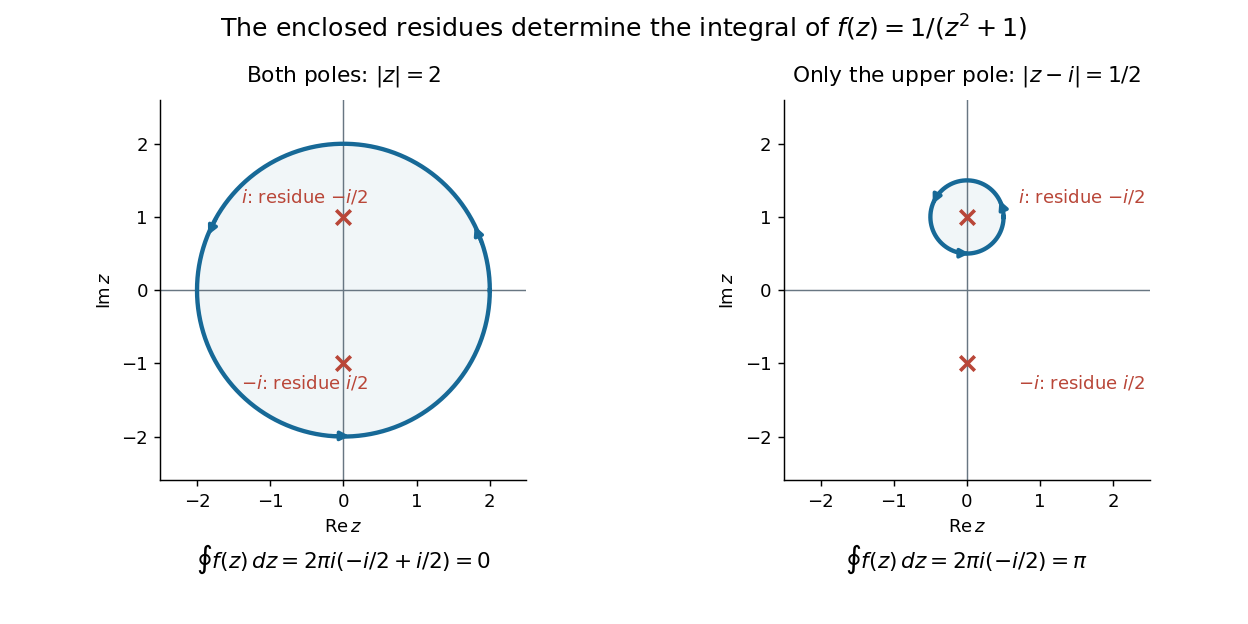
This is the practical appeal of the residue theorem: local Laurent coefficients determine a global contour integral. For a rational function, a few simple pole computations can replace a long parametrized calculation. It also makes real improper integrals accessible by treating the real line as part of a closed contour in the complex plane.
To compute , take and travel along the real line from to , then return along the upper semicircle , parametrized by for . This contour is positively oriented and encloses the simple pole only; is outside. HenceThe added arc must be controlled before taking a limit. On , the reverse triangle inequality gives , and the arc length is . The estimation lemma therefore yieldsThe denominator grows quadratically while the arc length grows only linearly. This quantitative comparison, rather than a sketch alone, explains why closing the contour does not alter the limiting real improper integral. It even supplies an error bound: the difference between and the finite real integral is at most .
For a numerical check, gives the finite real integral , leaving about to reach . The arc bound is , comfortably larger than that error. The graph shows both quantities approaching zero. The exact tail here can be checked with the antiderivative ; the residue theorem method remains useful for improper integrals where a convenient real antiderivative is unavailable.
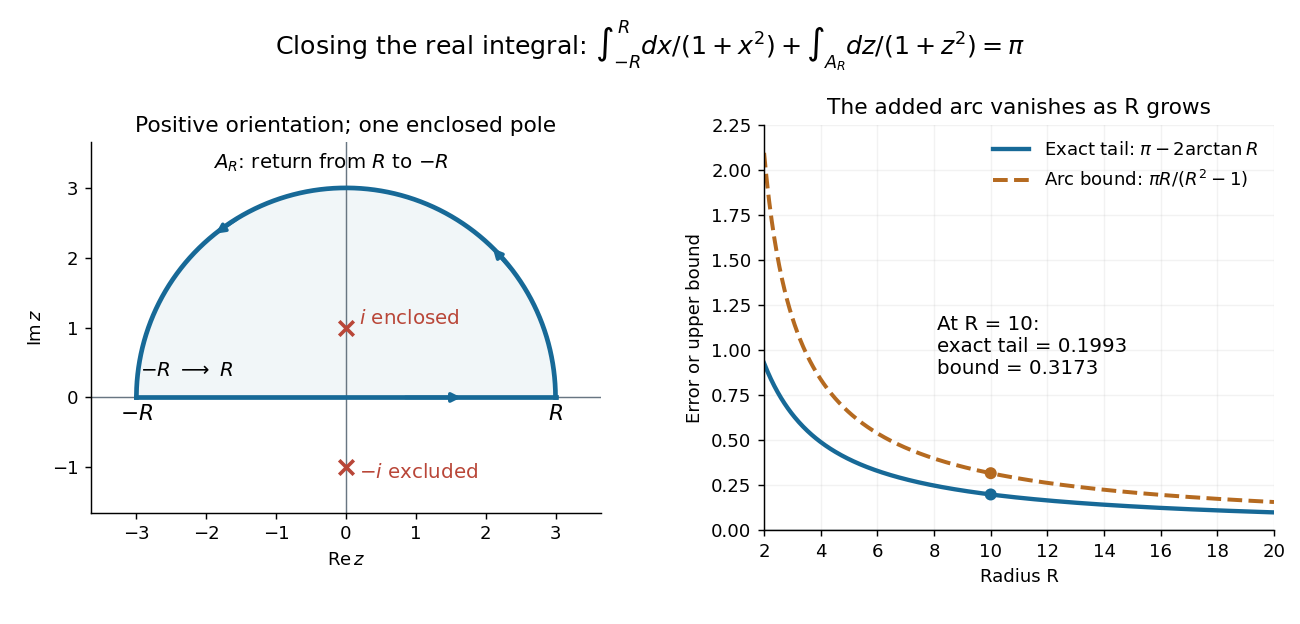


Finally, both one-sided improper integrals converge absolutely: for , , whose tails are integrable. Thus the symmetric limit computes the ordinary improper integral, not merely a Cauchy principal value, andClosing below instead would enclose the simple pole . With the same left-to-right traversal of the real line, that contour is clockwise, so its contour integral is again. This provides a useful sign check: the opposite residue is accompanied by the opposite direction around the enclosed region.
The same strategy extends to many other rational functions: choose a contour, identify its enclosed isolated singularities, compute their residues, and bound the added pieces. The choice of contour and the bound are as much part of the calculation as the residues. [ref]
The residue of a function at an isolated singularity is its Laurent coefficient of degree . More explicitly, if is holomorphic for , write its Laurent series asThis one Laurent coefficient determines the contour integral around a sufficiently small counterclockwise circle about . A complicated local Laurent series can therefore leave a remarkably simple answer after one complete trip around the point.
For a simple pole, multiplying by removes the pole, leaving a holomorphic extension whose value at is the residue:There is a useful shortcut for a quotient . If and are holomorphic near , has a simple zero there, and , then has a simple pole andThe first-order Taylor series of explains the denominator: dividing by leaves its derivative at in the limit. This computes a residue without finding the full Laurent series, which is especially useful when the numerator or denominator is complicated. [ref]
For example, the rational function has simple poles at and . Factoring the denominator makes both residues immediately visible:The signs matter: these residues cancel when both poles are enclosed, but either one contributes when enclosed alone. The residue theorem below turns this distinction into different contour integrals of the same function.
A residue is not the same thing as a pole, nor does it measure the order of a pole. The function has a double pole at zero but residue zero. Conversely,has an essential singularity at zero and residue one. Infinitely many negative powers cause no difficulty in reading off that particular Laurent coefficient. At a removable singularity the residue is zero. [ref]
Why does only this Laurent coefficient survive? Parametrize a counterclockwise circle by , , with . For every integer ,When , the complex exponential completes a whole number of turns and its contributions cancel; when , it is constant. Uniform convergence of the Laurent series on this circle justifies termwise integration, giving . Thus the residue isolates exactly the local information that a closed contour integral detects. [ref]
This selection rule explains why a very large value near an isolated singularity need not produce a large contour integral. The double pole grows faster near zero than , yet its contributions around a circle cancel completely. What matters is the arrangement of complex values along the path, including the differential , rather than their moduli alone. A residue records that surviving contribution, not the size of the function near the point.
A differential equation is an equation relating an unknown function to its derivatives. It specifies how change depends on the present state, and sometimes on the independent variables themselves. A solution of a differential equation is a function satisfying that relation throughout a stated domain; giving a formula without its domain can conceal a point where the equation is undefined.
The central idea is to turn a local law into a whole trajectory. For example, , with constant , says that the instantaneous derivative is proportional to the current value. If and per day, the solution of a differential equation is , so . This is an ideal growth model assuming a constant proportional rate; the exponential function emerges from repeatedly applying the same local rule. Changing the sign of gives exponential decay.
An ordinary differential equation uses one independent variable. A partial differential equation can involve several, such as space and time, and uses partial derivatives. Additional information selects a particular solution of a differential equation: an initial condition describes a starting state, whereas a boundary condition imposes constraints at the edge of a domain. The useful questions extend beyond finding a formula: does a solution of a differential equation exist, is it unique, and what happens to it over time?
There are unlisted articles, also show them or only show them.