A partial differential equation relates an unknown function of several independent variables to its partial derivatives. For , the notation means changing time while holding position fixed; measures how its spatial slope changes. Unlike an ordinary differential equation, a partial differential equation can describe an entire evolving profile rather than a single trajectory.
The heat equation smooths spatial variations, the transport equation moves them, and Laplace's equation describes a spatial equilibrium. Here is a diffusivity, is a velocity, and is the Laplacian. The periodic heat and transport comparison makes the difference visible using identical initial conditions.
A partial differential equation usually supplies a local rule rather than a complete answer. For example, every satisfies the heat equation with zero PDE source term; data select which profile is relevant. A complete problem specifies its domain of a function, coefficients, initial conditions, boundary conditions, and meaning of solution of a partial differential equation. A well-posed problem has existence, uniqueness, and continuous dependence on initial data in stated spaces; the equation alone guarantees none of these.[ref]
The initial table of content was limited to the first level because it is larger than 1000 articles. There are 1098 articles in total. Expand a branch to load its children.
A stochastic partial differential equation describes an unknown random field through spatial differential operators and random forcing. A model form is . The meaning of the noise, boundary data and solution is part of the specification; writing a formal derivative of Brownian motion does not define an ordinary function-valued forcing term.[ref]
An Introduction to Stochastic PDEs by Martin Hairer. Introduction and mild solutions of linear stochastic evolution equations
A simple exact example avoids the complications of noise at every spatial point. On with zero boundary values, considerThe solution is , whereHere . Spatial diffusion damps a single mode while noise continually excites it. More spatially irregular forcing can yield solutions that are distributions rather than pointwise functions, so regularity must be proved for the chosen dimension and noise.
A stochastic convolution propagates random forcing through a linear evolution. Let be a strongly continuous semigroup on a Hilbert space , let be a Cylindrical Wiener process on a Hilbert space , and let be a bounded linear operator. The expressionis an Itô integral whenever its integrand is square integrable in the Hilbert-Schmidt operator norm. In particular,This Itô isometry tests whether the accumulated forcing is actually -valued. The factor evolves the contribution arriving at time through the remaining time . For with deterministic initial value , the mild solution is .[ref]
An Introduction to Stochastic PDEs by Martin Hairer. §6, Definition 6.5, equation 6.3 and Remark 6.6; §4.4, Hilbert-space stochastic integration
For , and real Brownian motion , with ,This is the zero-initial-value Ornstein-Uhlenbeck process: damping limits the variance despite continued forcing. With , the limit is instead. These formulas follow by integrating in the Itô isometry.
The word convolution describes the dependence on the time difference . It does not mean an ordinary integral against a differentiable noise function; Brownian motion requires a stochastic integral.
A mild solution of an evolution equation satisfies an integrated equation built from its linear evolution, rather than requiring all derivatives in the differential equation to exist pointwise. Let generate a strongly continuous strongly continuous semigroup , and consider . Whenever the integrals are defined, its mild formulation isThe final term is a stochastic convolution. The linear evolution propagates both the initial condition and each later contribution for the remaining time. This is the infinite-dimensional counterpart of variation of constants.[ref]
An Introduction to Stochastic PDEs by Martin Hairer. Section 5, linear stochastic evolution and stochastic convolution; section 7, Definition 7.4 and equation 7.6, additive-noise mild formulation
A deterministic heat equation already shows why the definition is useful. Take on , zero forcing, and the discontinuous initial function . The mild solution is its convolution with the heat kernel:It is smooth for and approaches in as decreases to zero, even though the initial function lacks the derivatives appearing in the classical equation.
The word mild does not mean approximate. It specifies how the equation is interpreted. Existence, uniqueness and whether a mild solution is also a classical or distributional solution depend on the generator, initial data, nonlinear term and noise.
A stochastic heat equation combines diffusive smoothing with random forcing. On the real line, a basic additive model iswhere is space-time white noise, formally specified by . The noise is a random distribution, so this expression is interpreted through integration, not ordinary pointwise values. With zero initial data the mild solution isHere denotes the Gaussian noise integrated over space and time, and is the heat kernel.[ref]
An Introduction to Stochastic PDEs by Martin Hairer. Section 2.3.1, equations 2.5–2.6, additive white-noise model and heat-kernel representation
The Itô isometry turns a rough random field into a tractable calculation:Thus the standard deviation at a fixed location grows like from zero. Diffusion reduces the influence of each earlier disturbance while fresh noise continually arrives.
Dimension changes the answer. In spatial dimensions the kernel's squared integral is proportional to . Its integral near zero is finite only for . Consequently this additive white-noise model has pointwise finite-variance values in one dimension, whereas higher-dimensional versions require a distribution-valued interpretation or spatially smoother noise. The formal differential expression alone does not settle the solution's regularity.[ref]
An Introduction to Stochastic PDEs by Martin Hairer. Sections 2.3.1–2.3.2, covariance calculation and dimension-dependent roughness
A regularity structure is an algebraic framework for local expansions that can include singular distributions as well as smooth functions. Its formal data are : a locally finite set containing zero and bounded below; a graded vector space of Banach spaces, with the constants; and a group of linear maps fixing such thatThus changing an expansion's base point modifies a symbol only through lower-homogeneity terms. Martin Hairer introduced this framework to treat classes of singular stochastic partial differential equations.[ref]
A theory of regularity structures by Martin Hairer. Definition 2.1, arXiv v4 printed pages 18–19; Introduction, motivation from singular equations
Ordinary polynomials provide a complete elementary example. In one dimension take , spanned by , and realize around as . The function then has abstract local expansion . To transfer the expansion from to , substitute . For example,The expression on the left is the expansion at transported to . In particular, has strictly lower degree, illustrating the defining triangular property.
A model of a regularity structure adds concrete distributions and analytic bounds to these abstract symbols. Writing their realizations as , compatibility requires and . For singular equations the symbols extend beyond monomials; constructing a model, proving reconstruction and controlling corrections are additional steps. The triple alone does not make arbitrary products of distributions meaningful.[ref]
A theory of regularity structures by Martin Hairer. Sections 2.2–2.3, polynomial example and Definition 2.17 of a model
A model of a regularity structure realizes the abstract symbols of a regularity structure as concrete distributions, consistently across expansion points. It comprises continuous linear realization maps and maps satisfyingThus transports an expansion from to without changing the represented distribution.[ref]
A theory of regularity structures by Martin Hairer. Definition 2.17, printed pp. 25–26, algebraic identities
Analytic bounds connect each symbol's assigned order to its actual small-scale size. For ordinary isotropic scaling, put . For one requiresThese bounds are uniform on each compact set of base points, below each fixed upper order, for and smooth test functions supported in the unit ball with norm at most one; choose an integer . Other scaling choices change the rescaled test functions and distance. Negative allows singular distributions, whose small-scale averages can grow as shrinks.[ref]
A theory of regularity structures by Martin Hairer. Definition 2.17, equation 2.15; Remark 2.24, interpretation for negative orders
In the one-dimensional polynomial model of a regularity structure, and . For ,A change of variable in the test function pairing gives exactly , explaining the analytic bound for the monomial . The realization maps supply information absent from the abstract triple alone.
The polynomial model of a regularity structure realizes abstract monomials as ordinary coordinate differences around each base point. It is the example that turns a regularity structure into familiar Taylor polynomials. In dimensions, use a polynomial ring in symbols , graded by total degree. For a multi-index ,Re-expansion uses . Substitution immediately gives and , the compatibility identities of a model of a regularity structure.[ref]
A theory of regularity structures by Martin Hairer. §2.2, polynomial regularity structure; §2.3, Definition 2.17 and Remark 2.23, canonical polynomial model
For example, has local abstract expansion at . At it has . Transporting the latter substitutes :The coefficients change because the expansion point changes; the represented function is still .
The analytic scaling also follows by calculation. For a smooth test function and , changing variables givesThus the assigned degree predicts exactly the power of in the model bound. Anisotropic scaling can assign different weights to different coordinates instead; ordinary total degree is the isotropic choice. General regularity structures retain this organization of local expansions while admitting symbols that are not polynomials.
The complex Monge-Ampère equation prescribes the determinant of the complex Hessian of a real-valued function. On a domain in , one local normalization isThe positivity condition means that the complex Hessian is positive semidefinite; where it is positive definite the equation is elliptic. The determinant is nonlinear when , unlike the Laplace operator, which takes a trace.
For , the complex Hessian is the identity and . In one complex dimension, , so the equation reduces to a Poisson equation. On a Kähler manifold, its geometric version prescribes the volume form of a positive metric. Different conventions for change constants, so a determinant normalization should always accompany a coordinate formula.[ref]
https://www3.nd.edu/~jdiller/teaching/archive/spring11_80380/blocki2.pdf. Zbigniew Błocki, The complex Monge-Ampère equation, local determinant formulation and Kähler geometry
For a differential equation with its comparison order fixed, a supersolution satisfies . For example, if with , a sufficiently regular satisfying and dominating the initial and boundary data lies above a solution by the parabolic comparison principle. An unbounded-domain barrier such as can provide the missing boundary control at large distance. The sign convention belongs to the chosen differential operator and must be stated.
A subsolution satisfies a one-sided version of a partial differential equation, with the inequality convention tied to the operator's sign. For the Dirichlet problem with boundary data , a classical subsolution satisfiesIf a suitable comparison principle for harmonic functions holds and is a solution, then . Supersolutions reverse both inequalities.
In the unit ball of with , take . It vanishes on the boundary and , so it lies below the zero harmonic solution. The maximum principle explains the general comparison: is subharmonic and nonpositive on the boundary.
Weak subsolutions interpret the inequality against nonnegative test functions; viscosity subsolutions instead use touching smooth test functions. These are specified solution notions, not an automatic pointwise interpretation for a nonsmooth function.
A free boundary problem determines both a field and part of its domain boundary. A glacier terminus, for example, separates positive ice thickness from bare bed. Mass conservation, nonnegative thickness, a rule for ice ablation only where ice exists, and suitable interface or entropy solution conditions are needed; a formal zero of one characteristic branch alone need not give the selected physical boundary.
A drying front separates a positive liquid layer from a region where its thickness is zero. Its position is an unknown boundary determined with the wet-region solution. At a continuous zero-height front, a jump balance alone need not fix its speed; the vanishing-depth profile and removal law can supply that information. Source terms representing evaporation or infiltration must respect nonnegative water availability in the dry region.
A second-order partial differential equation is of mixed type when the type of its principal part changes across its domain. For , the sign of distinguishes a hyperbolic partial differential equation, parabolic type and an elliptic partial differential equation. For example, is elliptic above , hyperbolic below it, and degenerate on the interface. On its hyperbolic side, the change , reduces it to ; above it is the Laplace equation. Type classification alone supplies no matching rule for the normal derivative.
A function continuous across an interface can have different one-sided normal derivatives. For instance, when and when is continuous, satisfies on each open side, and has zero tangential second derivative on the interface. Its lower -derivative is one and its upper -derivative is zero. Thus the normal derivative does not exist there as a two-sided derivative.
More generally, for functions smooth on each side with one-sided first derivative traces, global regularity would force both traces to equal the derivative on the interface. Unequal traces therefore preclude a globally classical solution as well. A condition on the function value alone is not a condition on its normal derivative; a specified transmission law or an appropriate weak formulation is additional information.
A partial differential equation whose highest partial derivatives have order one. For , the method of characteristics follows the ordinary differential equations , , .
For a forward heat equation or a related reaction-diffusion equation on a spatial domain , the parabolic boundary is the union of the initial face and the lateral spatial boundary. It excludes the interior of the final-time face. This is the boundary relevant to the forward maximum principle: values at a later time are controlled by earlier data and the lateral boundary. Writing instead of in the union gives the same set, since the lateral term includes the initial rim.
On , , an initial condition gives the starting profile. For the heat equation, Dirichlet boundary conditions , can model ends held at prescribed temperatures. Alternatively, zero Neumann boundary conditions describe insulated ends in the constant-conductivity model. These choices can produce different evolutions from the same initial condition.
For a continuous classical solution reaching the corners, the Dirichlet boundary data must satisfy and ; higher smoothness can require further compatibility. In dimensionless variables, a complete worked heat equation problem isIts exact classical solution is . The straight profile is the equilibrium; the extra bump decays. Substituting verifies the equation and every datum, and the energy estimate proves uniqueness among smooth solutions with these data.
For the transport equation with on the same interval, prescribe an inflow transport boundary condition only at . Backtracking a characteristic curve gives if , and otherwise. Values at are determined by this formula; independently prescribing them can make the problem inconsistent.[ref]
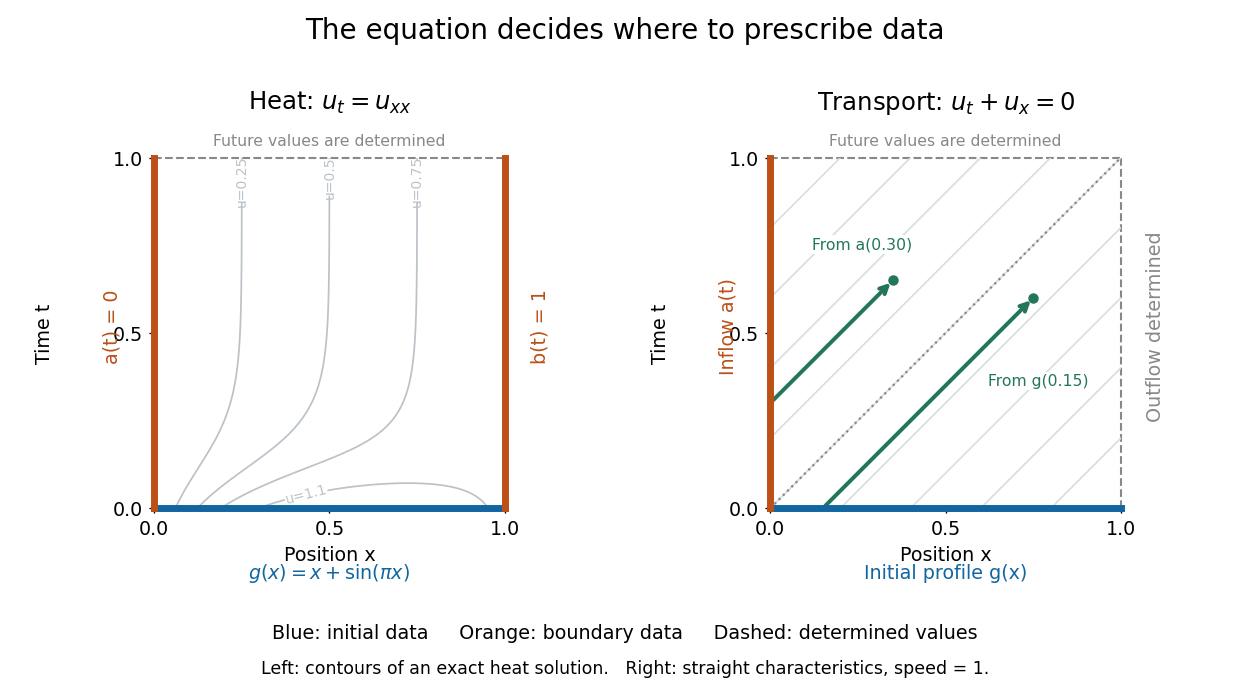
On the unit square, these data determine only the zero solution of the heat equation . The squared norm decreases because its derivative is , and its initial value is zero. For Laplace's equation, is a nonzero solution with the same three data; adding zero Dirichlet data on the top edge restores uniqueness by Green's first identity. For the wave equation , is a counterexample; the missing datum is initial velocity. Adding restores uniqueness by conservation of . Thus the type of equation determines what information is needed on an unprescribed edge.
An initial-boundary value problem specifies a partial differential equation, initial conditions, and boundary conditions. For example, the half-line wave equation requires an initial displacement and initial velocity for together with an endpoint condition such as for . Its meaning also depends on the chosen solution class: a classical solution satisfies the equation pointwise, while a weak solution satisfies an integrated form. These data must obey the compatibility conditions needed by the chosen regularity.
A prescribed PDE source term changes the heat equation to , or the transport equation to . If is a temperature, has units of temperature per time. The formulas below assume ; a nonzero PDE source term can change the spatial average even with periodic boundary conditions.
The Kuramoto-Sivashinsky equation combines destabilizing long-wave growth, stabilizing fourth-order diffusion, and nonlinear transport. Its potential form is , with . It arises as a long-wave phase amplitude equation near loss of the Benjamin-Feir stability condition. On a domain of period , the zero solution's Fourier modes grow at rate , .
Fix zero mean and period in the Kuramoto-Sivashinsky equation. At the first Fourier mode becomes neutral and all higher modes are damped. For , expand . The first equations are , , with . Slaving the second harmonic gives . Since at onset, this is a supercritical bifurcation. The small nonzero branch is stable in the sense of orbital stability against disturbances of the same fixed period, modulo translation; stability against disturbances of larger period does not follow from this local argument.
Green's identities relate volume integrals involving gradients and Laplacians to boundary values and normal derivatives. They follow from the divergence theorem and include Green's first identity, Green second identity and Green's third identity.
For a bounded smooth domain and , let , normalized by . For an interior point , Green's third identity isIt represents the function through its volume PDE source term, boundary values and outward normal derivative. For a harmonic function the volume term vanishes, so boundary data alone reconstruct the interior.
To derive it, apply Green's second identity on . The inner sphere has the outward normal of the punctured domain, pointing toward . Its singular fundamental solution term tends to as , giving the stated signs. Replacing by the Dirichlet Green function makes its boundary value zero and leaves the Poisson kernel multiplying the boundary values of . Thus the identity connects Green functions, boundary integral representations and Dirichlet problems.
If is constant on the boundary and is a regular harmonic function throughout a volume, the divergence theorem applied to gives . The constant boundary value factors out; a second application of the divergence theorem makes the remaining flux . This requires enough regularity to use Green's first identity over the entire volume.
Although is harmonic away from the origin in three dimensions, it is not a regular harmonic function on a ball containing the origin. Its gradient is , so the displayed improper volume integral follows by canceling the in the spherical volume element. On the annulus , Green's first identity gives outer boundary contribution and inner contribution , recovering the same limit. Its global Laplacian contains a Dirac delta distribution, so the regular-harmonic gradient-pairing theorem is inapplicable.
A maximum principle bounds a solution through its boundary or initial data, often forbidding nonconstant solutions from attaining an interior extremum. Weak and strong versions depend on the differential operator and hypotheses. The maximum principle for harmonic functions and its strong counterpart are examples.
For a classical solution of with , the positive part of its maximum is bounded by the corresponding maximum on the initial and lateral parabolic boundary. When , a positive maximum in space at an interior or final time gives , , and , a contradiction. For , a small strictly increasing exponential time perturbation gives the weak inequality by a limiting argument. Applied to both signs of the difference of two solutions, the principle proves uniqueness for fixed initial and boundary data.
On , the displayed smooth nonzero function satisfies . For each fixed it tends to zero at and at spatial infinity; for each fixed it tends to zero as . Thus these three pointwise limits do not determine a unique solution: a multiple of may be added to any particular solution of the same forced equation.
To verify the PDE, set . Both and equal . The missing control is at the corner: diverges as . There is no contradiction with the weak parabolic maximum principle, because a supremum on a past strip may be infinite or unattained. A bounded-solution class excludes this example. A standard uniqueness proof there applies the maximum principle to the difference minus and lets . Conditions at infinity and at initial time must control the relevant strip, not only each fixed-variable limit.
Let be a bounded domain, with real valued and . At a positive interior maximum, but , contradicting the equation. A negative interior minimum gives the opposite contradiction. Thus any value with absolute magnitude exceeding the boundary maximum would be impossible, proving the displayed bound. In particular zero boundary data force , and subtracting two solutions proves uniqueness for the corresponding inhomogeneous Dirichlet problem.
Let be a connected domain and a classical subsolution ofwith uniformly positive definite diffusion matrix, continuous bounded coefficients, and . If on and at a spatial interior point with , then on . Continuity supplies the same conclusion at initial and lateral points where the solution extends continuously. There is generally no conclusion about times after for a subsolution.
One proof applies the strict positivity principle to , a supersolution: any positive value at an earlier interior point propagates to positive values at every later interior point along a chain of overlapping interior balls, contradicting . Nonnegative zeroth-order terms can be bounded on each compact time cylinder and removed from this positivity argument by an exponential multiplier. For the inequality , use after the weak maximum principle has established .
If a harmonic function on a connected domain attains an interior maximum or minimum, it is constant. The mean value property forces equality throughout every sufficiently small ball around an interior extremum, and connectedness propagates the equality.
This is the strong harmonic instance of the maximum principle.
A continuous function harmonic on a bounded domain attains its maximum and minimum on the boundary. Apply the strictly subharmonic result to and let , then apply the same argument to .
If are harmonic functions on a bounded domain and continuous on its closure, their difference is a harmonic function. Its minimum is attained on the boundary by the maximum principle for harmonic functions applied to its negative. Nonnegative boundary difference therefore implies nonnegative interior difference. Applying the comparison in both directions proves uniqueness for the Dirichlet problem whenever a classical solution exists. This is an order statement and does not itself establish existence.
Burgers' equation is the one-dimensional partial differential equationThe term supplies nonlinear transport in a transport equation: the transported value is also its own characteristic speed when . Larger values catch up with smaller values ahead of them, steepening a decreasing profile. The diffusion term opposes this steepening. Positive gives the viscous Burgers equation; setting gives the Inviscid Burgers equation.
This small equation makes three different behaviors accessible in one model: Burgers characteristic breaking from continuous decreasing data, an entropy shock for a downward step, and a rarefaction wave for an upward step. The Burgers Riemann problem with positive flux and the Viscous Burgers travelling shock below give exact examples. These are mathematical calculations with chosen data; the figures contain no experimental measurements.
Unless stated otherwise, take , , constant , no PDE source term, and an initial condition . There are no finite endpoints requiring boundary conditions. Where a profile has different limiting states at , those states are specified explicitly. On a finite interval, boundary conditions become part of the problem: positive diffusion normally requires a condition at each endpoint, whereas the Inviscid Burgers equation requires appropriate inflow transport boundary conditions. With dimensional variables, has units of velocity and of kinematic viscosity; all numerical examples below use dimensionless quantities.
The Burgers' equation with constant linear damping has the displayed form. For zero viscosity and , characteristics are and . A negative initial slope can make this coordinate map cease to be invertible, producing shock formation by characteristic intersection. The transformation , converts the inviscid equation to the ordinary inviscid Burgers' equation. Across a thin viscous layer the damping contributes only at lower order to the leading Rankine-Hugoniot condition.
The viscous Burgers equation combines a nonlinear transport equation with diffusion with constant . On the infinite line, a bounded initial condition gives a smooth function solving the equation for every positive time; a jump in the initial condition is smoothed rather than retained as a discontinuity. Small can nevertheless produce a steep layer, as the Viscous Burgers travelling shock illustrates. The Cole-Hopf transformation , with positive , converts this equation to the heat equation .[ref]
Positive diffusion also explains the admissibility of the inviscid limit. For the entropy flux for a scalar conservation law associated with , direct multiplication by givesThe last term is nonpositive. With convergence sufficient to pass to the limit, the vanishing viscosity approximation therefore retains an entropy inequality rather than just the weak solution equation. For general bounded data, the full Kruzhkov entropy inequalities specify the entropy solution; the quadratic identity is a useful illustration of dissipation.[ref]
A travelling wave of the viscous Burgers equation can connect constant states through a smooth decreasing layer. Require , , , , and at both ends. Substitution and one integration giveThe speed follows by evaluating the integration constant at both end states. It is precisely the Rankine-Hugoniot condition for conservation law flux . Choosing the center gives the displayed hyperbolic tangent profile. Its characteristic width scales as ; a smaller positive makes a thinner smooth layer.
For an original worked example in dimensionless quantities, take , and :This is an exact classical solution on with its own smooth initial condition and limiting states . It is a family of moving profiles, not the finite- solution starting from an exact discontinuous step. For that different initial condition, the Cole-Hopf transformation supplies the evolution. At , this front starts from the same profile as the Burgers characteristic breaking example: positive diffusion maintains a smooth moving layer while the inviscid profile breaks at .
To check the partial differential equation explicitly, set and . ThenThe independent Rankine-Hugoniot condition check gives , using and . At fixed , the vanishing viscosity approximation tends to the entropy shock for and for . At the center the smooth profiles stay at ; changing the value on the discontinuity does not change the limiting weak solution.
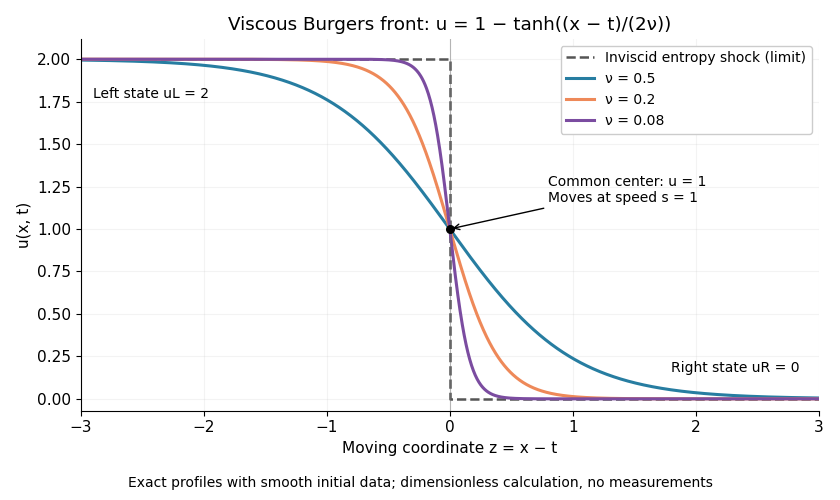
For , the same integrated ordinary differential equation has between the two states when , so it cannot supply an increasing connecting front. The inviscid admissible expansion is the rarefaction wave of the Burgers Riemann problem with positive flux.
The cubic-flux variant replaces the quadratic conservative flux of Burgers' equation by . Its inviscid characteristic speed is , while positive diffusivity regularizes shock waves. It is not linearized by the usual Cole-Hopf transformation.
For a front written in connecting at to nonzero at , one integration gives . The endpoint condition fixes . Setting gives a logistic equation and the displayed profile, with the sign of selected by . The propagation speed in the coordinate is , agreeing with the Rankine-Hugoniot condition for flux .
The Fay solution is a periodic solution of the negative-flux viscous Burgers equation for . Its Fourier series has exponentially decreasing coefficients at each positive . Expanding and summing the sine series givesFor , the first harmonic gives . The Fay shock-layer asymptotics describe its opposite, small- regime.
For and , the Fay solution becomes . The partial-fraction identity for the hyperbolic tangent sums this to the displayed smooth shock layer. It resolves the odd transition from to on angular thickness ; at both sides vanish and the comparison is read through their derivatives.
A localized negative-flux Burgers N-wave has initial profile on and zero outside, for . The Cole-Hopf solution for a Burgers N-wave expresses its viscous evolution in Gaussian interval masses. In the vanishing-viscosity limit, the interior slope becomes and its entropy-shock fronts move to .
For the negative-flux viscous Burgers equation, the Cole-Hopf transformation uses . Initial N-wave data give inside and one outside. Completing the square in the heat kernel convolution gives, with ,The Gaussian interval masses and their exponentially weighted tails must be treated together when taking the small-diffusion limit.
For positive diffusivity, the Cole-Hopf transformation with converts the negative-flux equation into the heat equation. Step data give a ratio of two Gaussian-tail integrals . At , and . Its vanishing-viscosity limit selects the shock or rarefaction wave in the Burgers Riemann problem with negative flux, depending on the sign of .
The viscous Burgers step solution with negative flux is symmetric around after subtracting . Its Gaussian-tail ratio equals one precisely at this midpoint, giving for either sign of . For this point becomes the entropy-shock center in the vanishing viscosity approximation; for it is the center of a rarefaction wave. The same trajectory therefore does not by itself identify a shock.
The Cole-Hopf transformation converts the viscous Burgers equation into the heat equation . Initial data correspond to .
Substituting into the viscous Burgers equation gives . Integration permits the arbitrary function in the title. Multiplication of by preserves and reduces its equation to the heat equation. Thus the heat-equation representation uses a permissible time normalization rather than a condition uniquely imposed on every representative .
For and initial data , the Cole-Hopf transformation gives . The Fourier series of this exponential and the heat equation give the displayed exact positive diffusion solution. Its first harmonic gives . The large-argument asymptotic expansion of a modified Bessel function makes the ratio tend to one as .
For the negative-flux viscous Burgers equation , set . A sum of exponentials in the initial heat data evolves into , giving the displayed softmax function average. Two terms produce a traveling tanh shock from the lower to the higher state, with speed minus their mean.
For ordered states , in the moving frame the first and last exponents in the finite-exponential Cole-Hopf solution have the same leading coefficient. Each interior state's coefficient is smaller by . Thus the large- moving-frame profile is the two-state shock between the extremes. At fixed , the endpoint of largest absolute value dominates; equal opposite extremes leave a stationary shock.
A semilinear partial differential equation is linear in its highest-order derivatives, with their coefficients depending only on the independent variables; lower-order terms may depend nonlinearly on the solution and its lower derivatives. A semilinear heat equation such as is an example. This differs from a quasilinear equation, whose highest-order derivative coefficients can depend on the solution or its lower derivatives.
A classical obstacle problem minimizes the Dirichlet energy with forcing while requiring the unknown function to stay above an obstacle. On a bounded Lipschitz domain , take and an obstacle . MinimizeThe closed convex set is nonempty, and the Poincaré inequality makes coercive and strictly convex. There is a unique minimizer , characterized by the variational inequalityIt follows by differentiating at ; convexity also makes the inequality sufficient for minimality.
Where regularity permits pointwise notation, the same conditions read , , and . On the noncontact set, variations of both signs recover the unconstrained Poisson equation. On the contact set of an obstacle problem, the obstacle can supply a reaction force. Its interface is an unknown free boundary problem. An analogous separation into stopping and continuation regions appears in optimal stopping, where the value must dominate the immediate payoff.
The noncontact set is where the unknown function is strictly above its obstacle. For continuous functions it is open. Every smooth variation with compact support in this set remains feasible with either sign when its amplitude is small enough. The first variation therefore vanishes there, yielding the unconstrained Euler-Lagrange equation. On the complementary contact set of an obstacle problem, only the appropriate one-sided variational inequality is available globally.
The contact set is the region where the obstacle inequality is active. On its complement the obstacle supplies no reaction; its boundary is a free boundary, determined along with the unknown solution. A point can belong to the contact set while its contact force is zero, as for a taut horizontal string just touching an obstacle at one point. Thus equality of the gap alone does not imply strictly positive pressure.
For a string of positive tension with fixed endpoints , zero transverse loading and obstacle , , equilibrium minimizes among functions above . On a free interval , while in contact . Smooth tangency of the right line through to the parabola at requires , yielding the displayed root in .
The two pieces join with equal value and slope. On the free portions ; in contact is the nonnegative reaction. These facts verify the complementarity conditions. The associated variational inequality and the exact energy difference prove global minimality; strict convexity with fixed endpoints proves uniqueness. At contact reduces to one point; at it fills the whole interval.
Minimizing the log-cosh energy over zero-trace functions above an obstacle yields the displayed inequality for every feasible competitor. Convexity supplies the one-sided admissible segments. On the open noncontact region, compactly supported variations of both signs are feasible because the gap from the obstacle has a positive minimum on their support. Their first variations vanish, giving there. This stationarity equation need not hold on the contact set.
For a bounded space-time cylinder, consider the linear partial differential operatorwith bounded coefficients, a symmetric uniformly positive-definite principal matrix, and . If sufficiently smooth satisfy inside and on the parabolic boundary, the weak parabolic maximum principle applied to gives throughout. A subsolution can therefore be compared with a supersolution. A lower bound on can replace nonnegativity after an exponential change in time.
At a first forbidden positive maximum of a strictly perturbed difference, its time derivative is nonnegative, its gradient vanishes, and its Hessian matrix is negative semidefinite. These signs contradict the strict differential inequality. The perturbation and a limit handle equality. Nonlinear comparison requires additional hypotheses rather than following automatically from this linear statement.
As a direct nonlinear example, suppose has a smooth periodic classical solution and . The constant-in-space-and-time function is a strict subsolution, since . A first downward contact at value would have and , contradicting . Thus for the lifetime of the smooth solution; the argument does not promise global existence.
For with zero Dirichlet boundary condition, choose . The constants and are a supersolution and a subsolution. More explicitly, testing with gives , since the reaction derivative is at most and the reaction at is nonpositive. The Gronwall inequality and the corresponding argument for prove that is invariant. A local variation-of-constants formula in the supremum norm then has a lifespan depending only on , which prevents finite-time loss of the classical solution.
The domain of dependence of a solution value consists of the initial and boundary locations whose data can influence it. For on the whole line, , so its initial-data domain of dependence is the foot of the characteristic. For a finite-difference scheme, repeated stencil dependencies determine a numerical domain of dependence. The Courant–Friedrichs–Lewy condition requires the numerical domain to cover the physical one for convergence; it is necessary under its usual hyperbolic hypotheses, but not in general sufficient for stability.
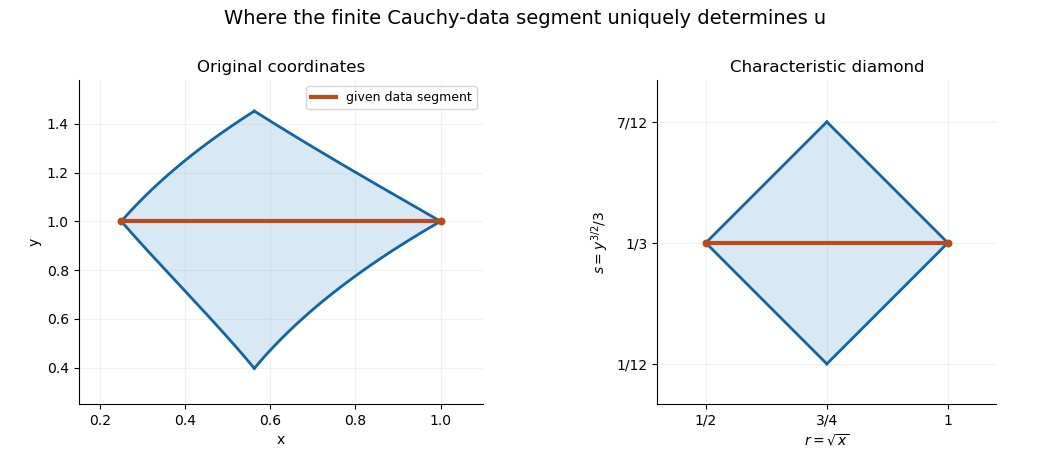
For Noncharacteristic Cauchy data parameterized by , the method of characteristics produces a surface . The part uniquely fixed as a classical graph through the data must retain both the allowed footpoint range and a nonsingular branch of the projected map. On a branch where inversion gives , require , together with the branch condition and a nonzero Jacobian determinant. The strict inequality describes its open interior; the endpoint characteristic supplies a boundary trace. A fold caustic can supply another boundary.
An algebraic formula obtained by eliminating can extend beyond this domain of dependence. Its values there need not be selected by the original data, because their characteristic footpoints can lie on the unprescribed half of the data curve. Tracking the parameter range is therefore part of the uniqueness argument, separately from selecting a real square-root branch.
For the one-dimensional wave equation with Cauchy data on , , the solution is determined where both characteristic footpoints lie in . This is the diamond displayed in the title, or . In characteristic coordinates, it is a rectangle of known arguments for the two travelling-wave functions. A smooth invertible coordinate transformation maps it to a region bounded by the original equation's characteristic curves; it need not remain a Euclidean diamond. Both forward and backward determination can be described this way. Outside the region, changing an unspecified part of one travelling-wave function can change the solution without changing the supplied finite data segment.
For , and data on , , the transformed segment is , , . The known characteristic arguments lie in and . The corresponding original region has curved boundaries despite being a rectangle in characteristic coordinates and a diamond in coordinates.
A linear partial differential equation is a partial differential equation in which the unknown function and its partial derivatives occur linearly, with coefficients independent of the unknown. Its homogeneous solutions obey the superposition principle.
For example, the heat equation permits adding independently decaying Fourier modes. For an equation with a fixed nonzero PDE source term, adding two solutions gives , so the sum generally solves a different problem. Likewise, adding solutions adds their initial conditions and boundary conditions.
For a second-order real linear partial differential equation in two variables, an invertible local change of variables simplifies its principal part. At regular points, the hyperbolic case has mixed-derivative principal part , the elliptic case has principal part , and the parabolic case has rank-one principal part , after multiplication by nonzero factors. Lower-order terms and forcing must also be transformed with the chain rule; simplifying only the principal part does not in general give the full canonical equation. In the hyperbolic partial differential equation case the new variables can be chosen constant along the two characteristic families.
For a second-order hyperbolic partial differential equation, the usual reduction to a mixed derivative uses twice continuously differentiable characteristic coordinates. Continuity of the principal coefficients alone does not ensure this regularity, even locally. Consider , and near the origin; the discriminant is the positive constant . A characteristic coordinate must satisfyThe two characteristic families have first integrals and . Locally, any coordinate transverse to the first family has the form with . If this were twice continuously differentiable, its restriction at would make twice continuously differentiable. But its second derivative approaches from the right and from the left, a contradiction. Independent characteristic coordinates cannot both choose the other family. Thus no twice continuously differentiable characteristic coordinate system exists near the origin.
With sufficiently smooth coefficients, the two distinct characteristic direction fields do yield smooth local coordinates. If is their Jacobian determinant and is the transformed mixed coefficient, then . Division by gives the mixed-derivative canonical form, including all lower-order terms produced by the chain rule. This is a local result; global intersections of characteristic curves can create separate obstructions.
For , , the Jacobian determinant is and the transformed domain is . The chain rule gives , while . The drift terms cancel, leaving . Thus the general solution is ; its characteristic curves are the level sets of the two new coordinates.
An ill-posed problem fails existence, uniqueness or continuous dependence in the specified function spaces. Backward heat equation evolution is unstable because its Fourier modes grow like , making arbitrarily small high-frequency errors grow without a uniform bound.
A linear partial differential operator sends a function to a linear combination of its partial derivatives. If its coefficients are constant, the Fourier transform of a derivative turns it into multiplication by its polynomial symbol .
The elliptic Liouville equation in the conventionarises from a planar conformal metric . Its Gaussian curvature is , so this equation is precisely the condition . Different curvature normalizations change the constant on the right; writing an exponential without specifying that convention can hide a sign or factor.
For example, on , has . The resulting metric is the Poincaré half-plane model. The nonlinear partial differential equation therefore constructs a geometry of constant negative curvature, rather than merely adding an arbitrary reaction term to the Laplace equation.
A radial function depends only on the distance from the origin: . Differential operators then reduce to radial formulas such as .
A radial profile is a one-variable function representing a radial function by . On an annulus , with , the spherical coordinate system identifies its Lp norm with the weighted profile norm through . Thus equality of two radial functions almost everywhere identifies their profiles almost everywhere in the ordinary one-dimensional sense.
A periodic domain identifies opposite faces of a fundamental cell, producing a flat torus. On an interval , smooth periodic boundary conditions require and matching spatial derivatives. These endpoints are one location, rather than two independently controlled walls. Periodic integration by parts has no boundary term, and zero-mean functions have no zero Fourier mode.
An energy estimate tests a differential equation against the solution or one of its derivatives to control a norm by initial data and forcing. Coercive terms represent dissipation, while Young inequality and the Gronwall inequality control lower-order terms.
For the difference of two smooth heat equation solutions with , identical PDE source term, initial conditions, and either periodic boundary conditions or Dirichlet boundary data, integration by parts givesThe initially zero nonnegative integral stays zero, proving uniqueness. The same computation bounds changes in the L2 norm when the initial conditions differ. Specifying data and a solution class makes this argument meaningful.[ref]
https://web.stanford.edu/class/math220b/handouts/heateqn.pdf. Stanford Math 220B heat-equation notes, section 2.8.3
A bootstrap argument assumes an a priori bound on an initial time interval and derives a strict improvement using an energy estimate or another inequality. Continuity extends the improved bound to the entire interval under consideration. For example closes when is sufficiently small. The strict improvement is what prevents a first failure time.
If with d'Alembert operator , then , where . Test the wave equation against , use integration by parts, and apply the Cauchy-Schwarz inequality. The same energy estimate applies to a finite system of wave equations.
For the unit-speed wave equation, the integral of over at time is at most its initial integral over . On a shrinking ball the outward energy flux minus the loss from its moving boundary is , hence nonpositive. This estimate establishes the domain of dependence and finite propagation speed without any assumptions at spatial infinity.
An estimate bounds the energy in a ball by the energy in the surrounding annulus. Moving the smaller-ball energy to the left gives the strict contraction with . Iteration turns this contraction into decay at small scales.
If and is nondecreasing, then . Between dyadic radii, monotonicity gives for any . This transfers a discrete contraction into a uniform power bound.
For a smooth Dirichlet Laplacian eigenfunction, testing with for gives the displayed energy estimate. The Sobolev chain rule for then yields . The absolute value and the sign in the test function permit nodal changes. At , use the Lipschitz absolute-value chain rule and the fact that a gradient of a Sobolev function vanishes on a level set.
A Caccioppoli inequality is a local energy estimate obtained by testing an elliptic equation with a cutoff times the solution. It controls the gradient on a smaller ball by the function and forcing on a larger ball.
For a weak solution of with real symmetric coefficients satisfying the two-sided uniform ellipticity bounds , the displayed Caccioppoli inequality holds with for a smooth cutoff function of compact support. Put and test the weak formulation with . The Sobolev chain rule gives , and Cauchy-Schwarz inequality yields . Divide and square. The constant is independent of the level .
For with bounded measurable coefficients and uniformly elliptic , testing with and using Young inequality gives . No sign condition on is needed for this interior estimate. A cutoff equal to one on and supported in yields the displayed bound; the constant depends only on dimension, ellipticity, coefficient bounds and the separation of from the boundary of .
Solutions of one fixed bounded-coefficient uniformly elliptic equation that are bounded in global have a subsequence converging strongly in on every relatively compact subdomain. Local energy bounds and the Rellich-Kondrachov compactness theorem first give local strong and weak convergence on a smooth exhaustion. Pass to the weak equation to identify the limit. Differences solve , so the interior Caccioppoli inequality upgrades the local strong convergence to strong gradient convergence. Global weak convergence preserves the original global bound.
For a weak solution of a uniformly elliptic homogeneous divergence-form elliptic operator, testing with and choosing the gradient of the cutoff function in gives . The arbitrary constant can be chosen as an annular average, which makes the estimate suitable for a hole-filling argument.
For a nonnegative bounded weak subsolution and , test with . Uniform ellipticity and Cauchy-Schwarz inequality give , with an operator norm bound for the coefficient matrix. The Sobolev chain rule and justify fractional powers and zero values. An entrywise bound yields .
For a nonnegative weak solution of a homogeneous divergence-form elliptic equation on , , with symmetric measurable , set and . There is independent of such thatTest the equation with a cutoff times , first regularized or truncated, to get . Apply a fixed-domain Sobolev embedding theorem to and take the power. Keeping the constant inside that power is crucial for Moser iteration.
For a positive weak supersolution of a uniformly elliptic divergence-form equation, testing with givesThe constant depends only on the ellipticity bounds.
A second-order partial differential equation contains derivatives of the unknown function of order at most two and at least one second derivative. Its principal symbol determines its characteristic directions and elliptic, parabolic or hyperbolic type.
In two independent variables, a scalar second-order partial differential equation with a definite principal symbol. It has no real characteristic direction. Laplace's equation is the basic example.
In two independent variables, a scalar second-order partial differential equation with a nonzero rank-one principal symbol. Its two characteristic directions coincide. The heat equation is the basic example.
For , the sign of distinguishes a hyperbolic partial differential equation when , an elliptic partial differential equation when , and a parabolic partial differential equation when and the principal symbol has rank one. If , the second-order principal symbol has rank zero and the differential order drops; this fully degenerate case must be checked separately for compatibility with the lower-order terms and forcing.
A quasilinear partial differential equation is linear in its highest-order derivatives, while its coefficients may depend on the independent variables, the unknown function, and lower-order derivatives.
For a flux and a weak solution of , discrete integration by parts and the fundamental theorem of calculus along a line segment show that solves , with and . Coercive quadratic-form bounds and operator norm bounds for on all segments between these gradients pass to . This produces a divergence-form elliptic operator without initially assuming second partial derivatives of .
The p-Laplacian is the nonlinear divergence-form operatorIt is the Euler-Lagrange operator of the p-energy. For it is degenerately elliptic where .
For a scalar differential operator of order , the principal symbol replaces each order- derivative by and discards lower-order terms. For a quasilinear partial differential equation, the coefficients are evaluated at the prescribed lower-order data.
A hypersurface is characteristic for a differential equation at when its principal symbol vanishes on the conormal :It is non-characteristic where this quantity is nonzero.
For a scalar second-order partial differential equation in two variables, a tangent direction along which Cauchy data fail to determine the highest transverse derivative through the equation. For principal part , a tangent is characteristic exactly when . Equivalently its conormal annihilates the principal symbol. A hyperbolic partial differential equation has two distinct real characteristic directions at each point.
For principal part , the displayed quadratic relation determines the characteristic directions. Curves tangent to them are characteristic curves. Lower-order terms do not enter this relation, but they may be singular where the principal coefficients alone suggest an otherwise ordinary classification. In particular, classifying a principal part on a singular line does not extend the full differential equation onto that line.
Articles were limited to the first 100 out of 1098 total.
Articles by others on the same topic

A partial differential equation (PDE) is a type of mathematical equation that involves partial derivatives of an unknown function with respect to two or more independent variables. Unlike ordinary differential equations (ODEs), which deal with functions of a single variable, PDEs allow for the modeling of phenomena where multiple variables are involved, such as time and space.



