Original solutions to both sections and all six questions of the Numerical Solution of Differential Equations paper sat on 22 June 2011. Source: released Mathematics papers,
Part B 2007 11.pdf. The real-triangularization assertion in question 6 is corrected to complex triangularization. Statements are not reproduced.Use the normalized local truncation errorThe Taylor theorem expansions about areSubstitution gives exactlyThus the theta method has order two exactly for , and otherwise order one, as a statement about the method on a sufficiently smooth class of problems. The leading term vanishes at one half, and a function with nonzero third derivative shows that the next term does not vanish universally. As usual, a uniform order estimate assumes bounded relevant derivatives; mere existence of on the open interval gives the stated pointwise remainders but not, by itself, a uniform bound. Special exact solutions can of course have zero truncation error even for a first-order method.
Put . Subtracting the numerical update from the exact update with its local truncation error givesThe Lipschitz condition in the solution variable and the triangle inequality implyThe assumed positive denominator permits division. With and , repeated substitution of this Lipschitz one-step error bound yieldsHere because , so the displayed geometric series quotient is well defined. For implicit steps, the same condition makes the scalar update map a contraction mapping, ensuring a unique numerical next value.
On the Dahlquist test equation, set . The theta method has stability functionWith the decaying-solution convention, its region of absolute stability is . Writing , squaring numerator and denominator givesFor this is the open disk with centre and radius . At it is the open left half-plane. For it is the exterior of the closed disk with centre and radius . The pole , when present, lies outside the stability region.
Every with satisfies the inequality exactly for . If , sufficiently large negative real fails it. ThereforeIf absolute stability is instead defined by bounded amplification, the boundary is included; this convention does not change the A-stability conclusion for the open left half-plane.
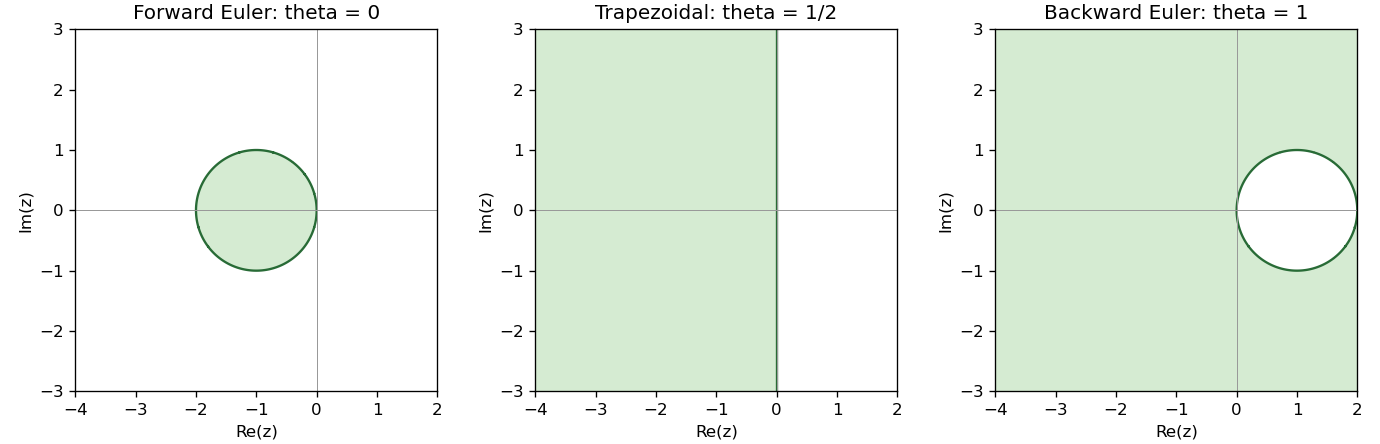
Absolute stability regions of the theta method at zero, one half and one; green regions damp the scalar test solution
. Details. 
In the normalization used by the supplied coefficient expansion, the local truncation error of the linear multistep method isThe nonzero sum in the denominator is an explicit hypothesis. Consistency of a numerical method requires uniformly on a fixed finite time interval for every sufficiently smooth exact solution as . Equivalently, the two polynomial identities areThese follow by inserting constant and affine functions, or by setting the first two Taylor coefficients to zero.
Zero-stability means that perturbations of the starting values of the zero-step recurrence remain bounded by a fixed multiple of their initial size, uniformly as the number of steps tends to infinity on a fixed time interval. In particular solutions of obey with independent of .
The equivalent root condition for a multistep method isA root outside the unit circle gives exponential growth of a recurrence relation mode; a repeated root on it gives polynomial growth. Repeated roots strictly inside it are harmless because their polynomial factor is dominated by decay.
The first characteristic polynomial factors asThe two quadratic roots have product one. Both can lie in the closed unit disk only if both have modulus one, requiring . At the root one is triple and ; at the root minus one is double. Both fail the root condition for a multistep method. In the intervening open interval the two quadratic roots are distinct conjugate unit-modulus roots, different from one. ThusUsing , the supplied expansion givesThroughout the zero-stable range, , so every such method has order two. There is a unique higher-order choice:Here and , giving exactly order four, with normalized leading truncation error . But the extra roots are , one of modulus greater than one. By the Dahlquist equivalence theorem this consistent but non-zero-stable method is not convergent for arbitrary consistent starting values.
Let , and define analogously. The Crank-Nicolson diffusion scheme isUse and zero values on every boundary node for every time level. This is the theta method with applied to the spatial finite difference method for the heat equation.
Write . The update can be rearranged asWhen , the right side is a convex combination of old values: its coefficients are nonnegative and sum to one. Assume all old values lie in . A new maximum is interior because boundary values are zero and . At its node the left side is at least , while the right side is at most , a contradiction. A new minimum similarly makes the left side at most and the right side at least , again a contradiction.
The initial values satisfy the bounds by construction; mathematical induction provesThe new-time matrix is a strictly diagonally dominant matrix with positive diagonal and nonpositive off-diagonal entries, so the linear update is uniquely solvable. This Crank-Nicolson maximum principle under a step restriction concerns preservation of value bounds, which is a stronger requirement than scalar A-stability.
For nonnegative initial data, . The proved Crank-Nicolson maximum principle under a step restriction immediately gives for all indices. For nonpositive initial data, and the same bound gives . Equivalently, apply positivity to , since the finite difference method is linear and has homogeneous Dirichlet boundary conditions. Both conclusions use .
For the second-order boundary value problem, introduce an unknown initial slope and solve the initial value problem , with , . Its endpoint mismatch is . The shooting method seeks a root ; in general the dependence of the flow on is nonlinear. A sign-changing bracket for a continuous allows the bisection method, provided the intervening initial value solutions exist up to .
For Newton's method, solve the parameter sensitivity equation alongside the trajectory. With and ,Then and the update is whenever .
For the third-order problem, shooting from leaves both and unknown, requiring two shooting parameters to satisfy two right-endpoint conditions. Shooting backwards from already knows and ; only is unknown, with the single residual . Backward shooting reduces the nonlinear solve from two scalar unknowns to one. This parameter-count advantage does not by itself guarantee numerical stability of backward integration.
The four-point midpoint third derivative uses the four values at , centred at . The Taylor theorem about that midpoint givesThus, for , take the interior equationsImpose the two value conditions exactly, , , and approximate the remaining condition with the second-order backward finite difference:This gives equations for . The endpoint derivative formula equals , so its residual tends to zero along with those of the four-point equations. Every stencil lies within ; no unprescribed ghost value is introduced. The construction is therefore a consistent finite difference method for all three boundary conditions.
The five-point equations for the Poisson equation arewith prescribed boundary values. If , an interior maximal value is at most the average of its four neighbours. Since no neighbour exceeds the maximum, equality forces all four to equal it. Repeating along adjacent nodes propagates that value to the boundary. Thus the discrete maximum principle gives , in particular the usual positive-maximum bound with zero included.
For an error estimate assume the exact solution has bounded continuous fourth partial derivatives up to the boundary. The local truncation error then satisfies by the Taylor theorem. Put , so and on boundary nodes. The Discrete Poisson barrier on a squaresatisfies exactly, on the grid boundary, and . Set . Then , with nonpositive boundary values. Applying the discrete maximum principle twice givesFor nonzero smooth Dirichlet boundary data , impose at the boundary nodes. The error still vanishes there, so the same argument and order apply, under the same fourth-derivative regularity of the exact solution. Smooth boundary values alone do not remove every possible corner-regularity issue.
Replace by . At a positive interior maximum , the neighbour average is no larger than , so . Thus cannot have such an interior maximum. The positive-maximum form of the discrete maximum principle therefore remains valid:With the error equation is , where under the preceding regularity assumptions. Since for the same Discrete Poisson barrier on a square, the comparison functions proveThere is no loss of uniqueness: apply the positive-maximum argument to both signs of a homogeneous discrete solution. The continuous weak formulation also has the coercive bilinear form , so the added positive reaction term strengthens its positive energy.
Let , and . Subtract the exact fixed-point equation to obtain . Hence convergence for every initial vector is equivalent to . If this holds, it holds after complexification; applying it to a complex eigenvector gives , so . Conversely, the complex Jordan normal form expresses each power as a finite sum of terms from its blocks. Every term tends to zero when all eigenvalues have modulus below one. ThusThe convergence criterion for a stationary iteration needs complex triangularization or Jordan normal form. The paper's assertion that every real matrix is similar to a real upper-triangular matrix is false when nonreal eigenvalues occur; complex triangularization supplies the intended argument. In the Gauss-Seidel method, with split into diagonal, strictly lower and strictly upper parts, .
For , eliminating the ghost values gives the symmetric pentadiagonal matrixAll other off-diagonal entries vanish. The first two equations areand the last two areFor the matrix is , for it is , and for it is because both ghost contributions meet the same unknown. The diagonal entries are positive in every case, so the lower triangular matrix is invertible and the Gauss-Seidel iteration is well defined.
An eigenvalue of makes singular. Let and be the sums of absolute lower and upper entries in row . The row's diagonal-dominance margin isInterior full rows have , , giving margin . Boundary rows have larger margins; for instance the first gives , and the second gives at least . Therefore would make a strictly diagonally dominant matrix, hence nonsingular, a contradiction.
At it is weakly diagonally dominant with strict boundary rows. Its nonzero nearest-neighbour entries make it an irreducibly diagonally dominant matrix. The nonsingularity theorem for that class again contradicts singularity. For the small matrices above all rows are already strict at this value. HenceThere is also a stronger conclusion. For ,including the overlap. Since is positive definite, is a symmetric positive-definite matrix. The Gauss-Seidel convergence from diagonal dominance and positive definiteness theorem consequently gives the stronger bound .
Articles by others on the same topic
There are currently no matching articles.