For a partition , approximate the integral by , using left endpoints. The defining independent Brownian increment of Brownian motion make this a centered Gaussian variable with variance . As the mesh tends to zero, that variance tends to .
The stochastic integral is the mean-square convergence of these sums. mean-square convergence implies convergence in distribution, while the characteristic function converge to . HenceThe probability is exactly one half because this centered nondegenerate normal distribution is symmetric and has no atom at zero.
Use a filtration with respect to which is Brownian. The process is adapted and continuous because it is a continuous function of and . The moment-generating function givesFor , writeThe increment is independent of and normal with variance , so the conditional expectation of the second factor is one. ThusThis verifies the martingale property from the definition and proves square integrability at each finite time, as well as continuity. It does not assert uniform square integrability over an infinite time horizon.
Lévy's characterization of Brownian motion states that a real continuous local martingale with and quadratic variation is a standard Brownian motion with respect to its filtration. Equivalently, its increments are independent of the past and have centered normal distribution with variances equal to elapsed times.
Let . The running maximum is continuous and adapted, so is bounded and progressively measurable process. It has a predictable version for integration; changing its value at the single switching time does not change its stochastic integral. Thus is a continuous local martingale starting at zero. Since ,Lévy's characterization of Brownian motion yields is standard Brownian motion. The sign depends on the entire past through the running maximum, but the unit quadratic-variation rate is exactly what the characterization needs.
The drift coefficient and diffusion coefficient are Lipschitz continuity and have linear growth. The standard existence and pathwise uniqueness theorem for stochastic differential equations therefore supplies a unique global strong solution of a stochastic differential equation, adapted to the driving Brownian filtration.
Apply Itô's formula to . Its time derivative contributes and its Itô correction contributes , giving the required equation and initial value. HenceIn particular the solution stays positive. For , factor out and use independence and the normal law of :The exponential moment exists, so this conditional expectation is well-defined for every finite .
Itô's formula identifies the infinitesimal generator on twice continuously differentiable functions:Subtract the drift coefficient integral from that formula to obtainStopping when leaves a bounded interval makes the integrand bounded on each finite time interval. Therefore is a continuous local martingale. In fact and the lognormal distribution solution has finite second moments on finite intervals, so here it is square integrable on each such interval as well.
The quadratic covariation of two stochastic integrals against the same Brownian motion is the integral of the product of their integrands. ConsequentlyThis is the quadratic covariation, which agrees with the pathwise quadratic covariation for these continuous local martingales.
Taking the logarithm of the explicit solution gives a linear function of the normal random variable :ThusFor its density isand it is zero for . The factor is the Jacobian of the logarithmic change of variable.
Fix a finite horizon and use the completed natural Brownian filtration. Martingale representation theorem states that every can be writtenwhere is predictable and is unique up to equality for almost every .
The Martingale representation theorem states that every square-integrable martingale in this filtration has a continuous version of the formwith the same integrability and uniqueness condition. The completed natural filtration has only null-set randomness at time zero, so is almost surely constant. The first statement gives the second by representing and taking conditional expectations; the second gives the first by taking .
There is also the local version: every local martingale in the Brownian filtration has a continuous version representable by a predictable, locally square-integrable integrand. The filtration restriction matters; an enlarged filtration with independent additional martingales need not have representation using alone.
For , and . Itô's formula givesSince , this is exactlyThe integrand retains ; replacing it by a fixed sign of would lose information about the phase of .
Condition on the Brownian path up to . The independent normal increment has and zero expected sine. HenceApply Itô's formula to this expression. Its time derivative and second spatial derivative cancel, leavingTherefore the required representation isThe bounded integrand is square integrable, and uniqueness follows from the Itô isometry. The drift-containing decomposition in part (b) alone would not be the required representation as a constant plus one stochastic integral.
Apply Itô's formula to . The quadratic-variation correction cancels the finite-variation term:Localization of the integrand proves that is a nonnegative continuous local martingale.
For completeness, Conditional Fatou lemma says that for nonnegative random variables ,Choose a localizing sequence such that each stopped is a martingale. Fatou first gives . For , its conditional form then givesThus is a supermartingale.
A sufficient condition for it to be a true martingale on is Novikov's conditionUnder this condition the stochastic exponential is a uniformly integrable martingale on that finite interval. Requiring it for every finite gives the martingale property at all finite times; it does not automatically give uniform integrability as .
For , independence and the Gaussian Brownian transition density yield the Chapman-Kolmogorov equationThe numerator is positive and its expectation is , soThese statements hold for every , in particular on the specified closed interval .
The function solves the backward heat equation . Itô's formula therefore givesOn each interval ending before one this adapted continuous integrand is locally square integrable. Thusgives . This also follows by applying Itô's formula to . The source's notation for this density process is restricted by its defining formula to .
A finite-horizon form of Girsanov theorem is as follows. If is predictable, almost surely, and its stochastic exponential is a true martingale of mean one, then under the probability the processis Brownian motion. The same conclusion holds on the completed natural filtration, since a strictly positive density gives equivalent probabilities.
Part (b) establishes precisely the required density martingale and integrand . ThereforeIn particular it is the requested local martingale. Equivalently, under , solves , the Brownian bridge drift coefficient toward at time one. Keeping avoids the singular endpoint in this density change.
Write , with a real Brownian motion started at one. For the nontrivial strip calculation assume , so the starting point is in its interior. The first exit time isFor a continuous Brownian path started inside, this equals the first hitting time of or almost surely: Brownian motion started at a boundary immediately visits the exterior, so using the closed strip in the definition does not change the infimum.
The stopped harmonic coordinate is a martingale bounded between zero and . bounded convergence theorem and optional stopping theorem give . Since the exit coordinate is zero or ,If is the first hit of the real axis, exit through the lower boundary implies , so for every . Letting provesThe strip assumption is worth making explicit: at the initial point is the upper boundary and exit is immediate; for it starts outside the strip and the displayed interior probabilities do not apply.
An analytic function is an entire function when it is holomorphic on the whole complex plane. Thus every finite complex point has a neighborhood on which the function is complex differentiable; there is no finite singularity. polynomials and the exponential are entire, whereas is not.
planar Brownian motion is recurrence of planar Brownian motion when, almost surely, it returns to every nonempty open neighborhood infinitely often, at arbitrarily large times. This does not mean that it hits each specified point; a prescribed point is polar for planar Brownian motion.
recurrence of planar Brownian motion and continuity imply that all the circle-hitting times in the question are finite. Starting on radius , it eventually visits the exterior of radius and must cross that circle; it later visits the interior of radius and must cross back. Each duration is strictly positive by path continuity, because the two radii are separated.
At , the Strong Markov property restarts Brownian motion at its current point on the inner circle. rotational invariance of Brownian motion makes the law of the subsequent first exit time from the radius- disk independent of that starting angle. Its conditional distribution given the past is therefore the same fixed law at every cycle, proving that the are independent and identically distributed.
To prove divergence of the conformal clock for any nonconstant entire , choose a point with . By continuity, there exist such that throughout the closed disk . Use the same recurrence of planar Brownian motion circle cycles centered at , with radii . On each segment from the inner circle to the outer circle, the path remains in that disk, givingThe durations are positive iid variables. If their mean has not been computed, apply the strong law of large numbers to the bounded iid variables : their mean is strictly positive, so their sum, and hence , diverges almost surely. ThereforeCentering the disks at a noncritical point avoids an unjustified positive lower bound on around the original origin.
Write . Harmonicity and Itô's formula make continuous local martingales. The Cauchy-Riemann equations give equal brackets and zero mutual bracket. Consequently Lévy's characterization of Brownian motion after time change of a continuous process makes a planar Brownian motion started at , with no finite clock lifetime because the clock just proved is unbounded. The clock is strictly increasing: otherwise would vanish along a nonconstant path interval, contradicting its isolated zeros.
For the notation in the source, is interpreted as the conformal scale . If it instead means the sum of the squared magnitudes of both complex coordinate derivatives, it is , and the resulting runs at half the usual Brownian speed. This convention does not change divergence of the integral. The mechanism is recurrent disk occupation makes an entire conformal clock infinite.
Take and let be the first time hits . Reflect the horizontal coordinate after , leaving the vertical coordinate unchanged. The Strong Markov property and symmetry preserve the law of planar Brownian motion and leave its real-axis exit time unchanged. On paths with , the reflection swaps the two terminal events and . There is no terminal atom at . Hence the Brownian reflection principle givesHorizontal symmetry gives the same probability for . A union bound therefore yieldsAlso , whose Cauchy distribution is . Thus the maximum tail is bounded above and below by positive constants times for large . The tail integral formula for moments for positive moments givesThe large- integral is finite exactly when ; it diverges for . Near zero its upper bound by is finite.
The vertical coordinate remains nonnegative up to exit and starts at one. The strip calculation, now with upper boundary , givesThus has density on , and in factFor completeness, if the source's includes negative powers, also has all negative moments. Let be the first horizontal exit from . ThenThe first bound follows from the Gaussian reflection bound for the vertical hit of zero; the second follows by splitting time into blocks of length , each having a fixed positive chance of exiting the horizontal interval. This small-value estimate integrates against every negative power. At both moments equal one.
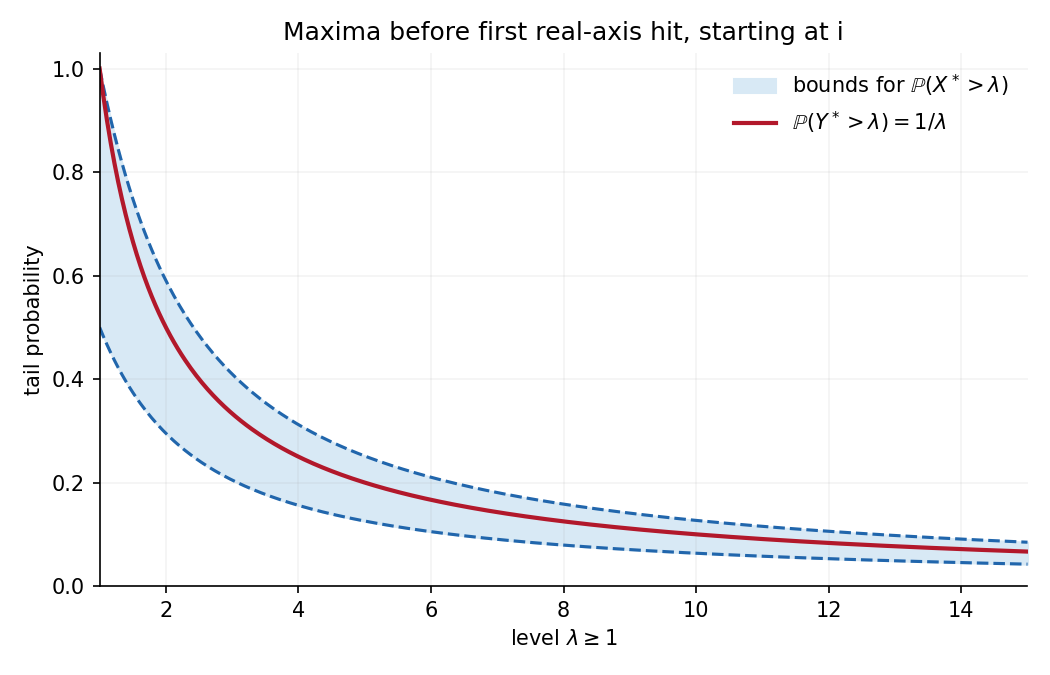
The vertical maximum has an exact inverse-height tail while the horizontal maximum has comparable Cauchy tails
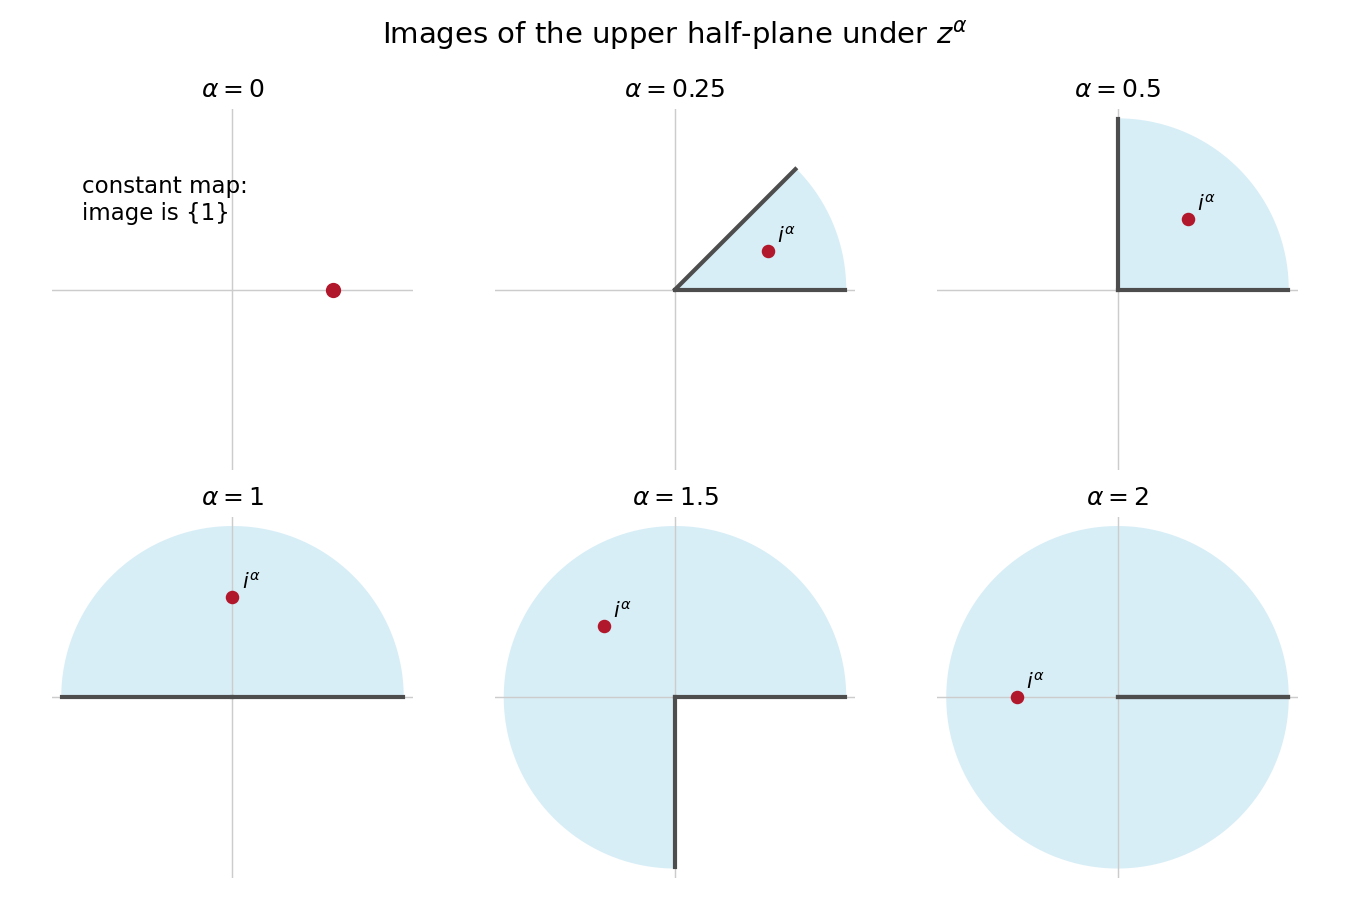
. Details. For , write with . The chosen power map sends this to , soAt this is the plane slit along the nonnegative real axis. For every , the map is conformal on the upper half-plane.
To check finiteness of the physical exit time, start a Brownian motion at and let be its real-axis exit. The time change of a continuous process in conformal invariance of planar Brownian motion isWe know almost surely. The Cauchy exit law from a Brownian half-plane assigns probability zero to . On such a path, throughout the compact interval , because it is in the open upper half-plane before exit and has nonzero endpoint. Its modulus therefore has a positive minimum and finite maximum. The displayed integrand is bounded on that interval, proving . The image Brownian motion exits at this finite changed time.
The endpoint printed in the source is degenerate: , so its image is the singleton , not an open domain, and the map is not conformal. If exit from that set is defined for Brownian motion started at one, its exit infimum is zero. It cannot be included in a nondegenerate conformal-domain argument.
Here is the martingale argument for maximal comparisons, including the starting-value issue. For , the Cauchy-Riemann equations and Itô's formula show thatare orthogonal continuous local martingales with the same quadratic variation. Localize before large disks and before exit. The Burkholder-Davis-Gundy inequalities then givewith a constant depending only on ; Fatou's lemma removes the localization. These are centered martingales. For the uncentered processes this impliessince .
The source normalizes at a boundary point, rather than the value of at the starting point. Consequently its displayed constant cannot be uniform in with only dependence. To see this, take and . Then and . Inside this narrow wedge,Both th moments are finite and the right one is positive; finiteness follows from the wedge radial-maximum tail of order , justified below. The source inequality would force , unbounded as . At , the immediate-exit interpretation gives the direct contradiction for the same polynomial.
For a fixed nondegenerate wedge, an uncentered inequality does hold with a constant allowed to depend on as well as . One rigorous outline for the polynomial class in this question is as follows. Separation of variables in a sector of radius gives, for exit through its circular arc, the expansionThus at the specified starting point the radial-maximum tail is comparable to . Hitting any fixed interior subarc has that same power, with positive leading coefficient. If a nonzero polynomial has degree , its real part has magnitude at least on some fixed interior subarc for sufficiently large . Therefore its maximal real-part th moment is infinite whenever . In that case the desired extended-real inequality is automatic.
The remaining polynomials have , so belong to a finite-dimensional vector space space. On that spaceis a genuine norm: if it is zero, Brownian motion's positive probability of reaching any interior neighborhood forces throughout , so analyticity makes a purely imaginary constant, and makes it zero. The corresponding imaginary-part functional is bounded on this finite-dimensional vector space normed space; its finiteness follows from and the radial tail bound. equivalence of norms in finite dimensions givesThis establishes the fixed-domain interpretation and identifies exactly why the universal centered martingale inequality cannot silently be applied to the printed uncentered boundary normalization. It is the distinction in starting-value obstruction in wedge conjugate maximal inequalities.


Articles by others on the same topic
There are currently no matching articles.