A credible interval is an interval containing a prescribed amount of posterior probability for an unknown scalar statistical parameter . For a continuous posterior distribution with posterior density , its endpoints satisfyThe conditioning includes the chosen statistical model and prior distribution. For a discrete posterior distribution, exact equality may be impossible because of its probability masses; an interval can instead be required to contain at least the requested posterior probability. An interval compresses the full posterior distribution into a range whose uncertainty can be communicated in the parameter's own units. See MIT 18.05, Class 16: probability intervals.
For the eight-head, two-tail example in Bayesian statistics, the posterior density is on . Its cumulative distribution function, obtained by integration of this polynomial, isSolving and by the bisection method givesThese are numerical approximations to the exact quantiles defined by those equations; the endpoints were computed from the cumulative distribution function, rather than read off a plot. The resulting equal-tailed credible interval leaves 2.5% posterior probability on each side. Its shaded area is 95% of the total area under the posterior density.
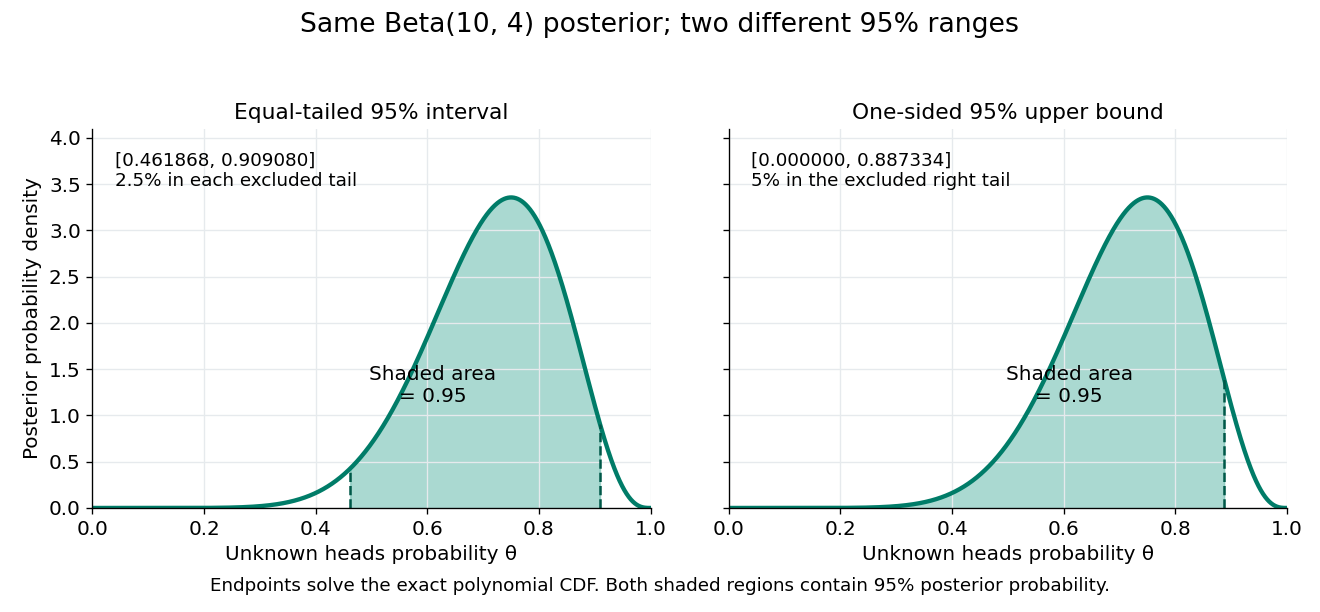

Credible intervals are not unique. The one-sided credible interval also has 95% posterior probability, but leaves all 5% outside it on the right. A highest density region instead selects points above a density threshold; it need not be an equal-tailed credible interval, and when the posterior density has separated peaks it need not be one interval at all. Thus a reported credible interval should specify its construction.
A 95% credible interval makes a statement about the statistical parameter conditional on these observed data and the Bayesian model. A 95% confidence interval instead refers to the coverage probability of a procedure under repeated sampling at a fixed parameter value. These are different conditioning statements: 95% posterior probability does not by itself imply 95% coverage probability for every fixed parameter. The confidence interval article develops that sampling interpretation.
A highest posterior density interval is a credible interval whose included points have at least as high posterior density as excluded points, apart from boundary and null-set choices. It is a highest density region of prescribed posterior probability that happens to be an interval. For a continuous unimodal posterior with two interior endpoints, the endpoint densities agree. A monotone posterior on a half-line instead starts at a support boundary, as in a Pareto highest density interval. For a multimodal posterior distribution, the highest-density region can be disconnected and cannot always be represented by a single interval. Density-level regions use a specified parameter coordinate and reference measure; they are not generally preserved by nonlinear reparametrization.
For a beta distribution with shape parameters , the probability density function vanishes at zero and one and is strictly increasing up to and strictly decreasing afterwards. This follows because the derivative of its logarithm is , whose sign changes at .
For each , the highest posterior density interval when this beta distribution is a posterior distribution has unique endpoints determined byThe second equation gives equal endpoint posterior densities. For every density threshold strictly between zero and the modal height there is precisely one crossing on each side. The enclosed probability is continuous and strictly decreasing from one to zero as the threshold increases, proving existence, uniqueness and the highest posterior density interval property. The restrictions are essential to this two-interior-endpoint characterization; monotone cases use a support boundary instead.
An equal-tailed credible interval uses quantiles of a continuous posterior distribution to leave posterior probability in each tail. It is also called a central credible interval; central refers to equal tail probabilities, not equal distances from the posterior mean. For the beta distribution in credible interval, the 95% endpoints are approximately and , whose midpoint differs from the posterior mean .
A one-sided credible interval puts all excluded posterior probability in one tail. For a continuous posterior distribution, an upper bound satisfies ; a lower bound uses . Intersecting with the parameter's allowed range removes points of zero posterior probability. For the beta distribution , the upper 95% bound is , so is the alternative credible interval shown above.
Articles by others on the same topic
There are currently no matching articles.