
Local isometry from a circular cone to the plane Created 2026-09-24 Updated 2026-09-24
For the conethe first fundamental form isThe local change of polar coordinatesturns this into the Euclidean metric .
Riemannian isometry Created 2026-09-24 Updated 2026-10-03
A Riemannian isometry is a diffeomorphism that preserves the Riemannian metric, and hence lengths, areas, and intrinsic curvature.
Geodesic preservation by a local isometry Created 2026-09-24 Updated 2026-10-05
A local isometry intertwines the Levi--Civita covariant derivatives. It therefore sends every affinely parametrized geodesic to an affinely parametrized geodesic.
Fixed barycentre of the barycentric tetrahedral two-skeleton Created 2026-09-24 Updated 2026-09-24
In the two-skeleton of a barycentrically subdivided tetrahedron, the vertex corresponding to the whole tetrahedron has link equal to the connected 1-skeleton of the subdivided boundary, with 14 vertices and 36 edges. Its local therefore has rank . Every other point has smaller local rank, so every self-homeomorphism fixes this vertex.
Local homology from a link Created 2026-09-24 Updated 2026-09-24
Adjoint transport equation Created 2026-09-24 Updated 2026-11-05
The adjoint transport equation moves a transport equation operator from a solution to a test function by integration by parts. For , its formal space-time adjoint operator isIndeed when both functions have compact support away from the time endpoints. The term is essential for a compressible velocity field. By contrast, the conservative operator has .
For a smooth complete characteristic flow map with compact supports remaining bounded on , solve backward with , for a smooth compactly supported . Integration by parts in time gives for a weak solution of . Thus zero initial condition forces zero pairing with every such , proving uniqueness. The characteristic curves solve this terminal problem with a divergence weight; omitting that weight would test a different equation.
Stable spiral Created 2026-09-24 Updated 2026-10-06
A planar equilibrium is a stable spiral when its Jacobian has a complex-conjugate pair of eigenvalues with negative real part. Nearby nonstationary trajectories spiral toward it.
Stable node Created 2026-09-24 Updated 2026-09-29
A planar equilibrium is a stable node when its two Jacobian eigenvalues are real and negative. Every nearby trajectory approaches it, tangent asymptotically to an eigendirection.
Saddle equilibrium Created 2026-09-24 Updated 2026-11-05
A saddle equilibrium in a smooth planar flow has one attracting and one repelling linearized direction. Its Jacobian determinant is negative, so its two eigenvalues are real and have opposite signs. This produces stable and unstable invariant directions rather than uniform attraction or uniform repulsion.
For , with , the axis approaches the origin in forward time and the axis moves away. A generic nearby initial state has a nonzero component and eventually leaves, even if its distance initially decreases. In a nonlinear system, the corresponding stable manifold and unstable manifold curve away from their tangent eigendirections. Such manifolds can form a separatrix between different kinds of motion, making a saddle important for global outcome selection as well as local instability.
Attenuation bias from classical measurement error Created 2026-09-24 Updated 2026-10-07
If but the predictor is observed as , with independent centred errors, the population regression slope isMeasurement error in the predictor therefore shrinks the slope toward zero, while independent response noise changes its uncertainty but not its population value.
Interaction term Created 2026-09-24 Updated 2026-10-14
An interaction term lets the effect of one predictor depend on another. Inthe slope with respect to is .
Regression coefficient Created 2026-09-24 Updated 2026-10-14
A regression coefficient is a component of measuring the change in the linear predictor associated with its design-matrix column.
These are the parameters of a linear regression predictor, rather than the regression procedure itself.
Design matrix Created 2026-09-24 Updated 2026-09-24
The design matrix has one row for each observation and one column for each regression coefficient, so the linear predictor is .
Jump condition for an impulse Created 2026-09-24 Updated 2026-11-05
A jump condition for an impulse follows by matching the singular terms in a distributional derivative. For the first-order system , with locally bounded nonsingular coefficient and piecewise smooth , integration across givesThe integral of over a shrinking interval vanishes, while the Dirac delta distribution has unit integral.
For with , displacement must be continuous and velocity jumps by . Indeed, a displacement jump would create in the second distributional derivative, with no matching source. After imposing , matching the delta coefficients gives . A derivative-of-delta source would change these conditions; integrating once without checking that more singular term can miss a required continuity constraint. The impulse cancellation of a harmonic oscillator is an application.
Linear system of differential equations Created 2026-09-24 Updated 2026-10-03
Resonance in a differential equation Created 2026-09-24 Updated 2026-11-05
In a linear differential equation, resonance in a differential equation occurs when the forcing belongs to a mode annihilated by the homogeneous operator, so an ordinary trial of the same shape cannot be inverted. For with , a polynomial factor in supplies a resonant exponential particular solution. The root multiplicity determines the required power.
For , is a particular solution. Direct differentiation gives . By contrast, the resonant equation has , which still decays: resonance enhances a mode relative to its natural exponential, without always causing an unbounded physical response. Under logarithmic coordinates in a Cauchy-Euler equation, polynomial factors in transformed time become logarithms of .
Integrating factor Created 2026-09-24 Updated 2026-10-14
An integrating factor is a nonzero multiplier that makes a differential equation directly integrable. For a first-order linear differential equation, it gathers the unknown function and its derivative into one product rule expression. Suppose and are continuous functions on an interval containing , and consider the initial value problemDefine and . The exact solution of a differential equation throughout that interval isThe definite integral fixes , so the initial condition appears without an extra constant to determine. If the equation originally has a coefficient multiplying , first divide by that coefficient on an interval where it is nonzero; a zero of that coefficient needs separate attention. See OpenStax's first-order linear equations chapter for this normalization and the integrating factor procedure.
For a concrete balance, solve with . Here , so multiplying the entire ordinary differential equation gives . Accumulating from zero to givesThe computed values are , and . Its derivative is , which verifies exactly. Interpreting as a steady input and as proportional removal explains the shape: initially all input increases , then removal catches up. The constant particular solution balances input and removal, and the homogeneous solution is the transient response that corrects it to the initial condition. Because this autonomous differential equation has a time-independent right-hand side, is also an equilibrium point.
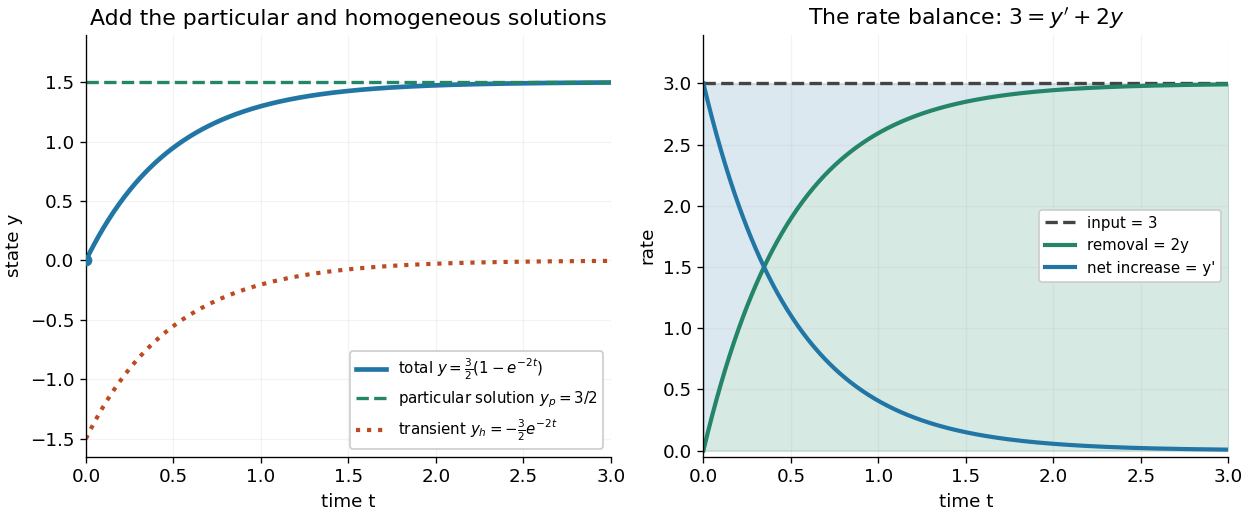

The first panel adds the particular solution and homogeneous solution; the second shows the same balance in rates, . This links the algebra to a physical accounting rule. Newton's law of cooling has this form with and , while an electrical circuit can have a varying input. In both cases the integrating factor systematically handles the input rather than requiring a guess for a particular solution.
Variable coefficients work just as directly. For , , the integrating factor is , andThus , and . The derivative verifies , including at zero, where both coefficient and input vanish. No division by is necessary. The general solution is : is a constant particular solution, and solves the associated homogeneous linear differential equation. Although this special forcing term admits a constant trajectory, this is a nonautonomous differential equation: it depends explicitly on time. Merely setting its right-hand side to zero at one instant would not establish a constant solution of a differential equation; at every state has zero slope.
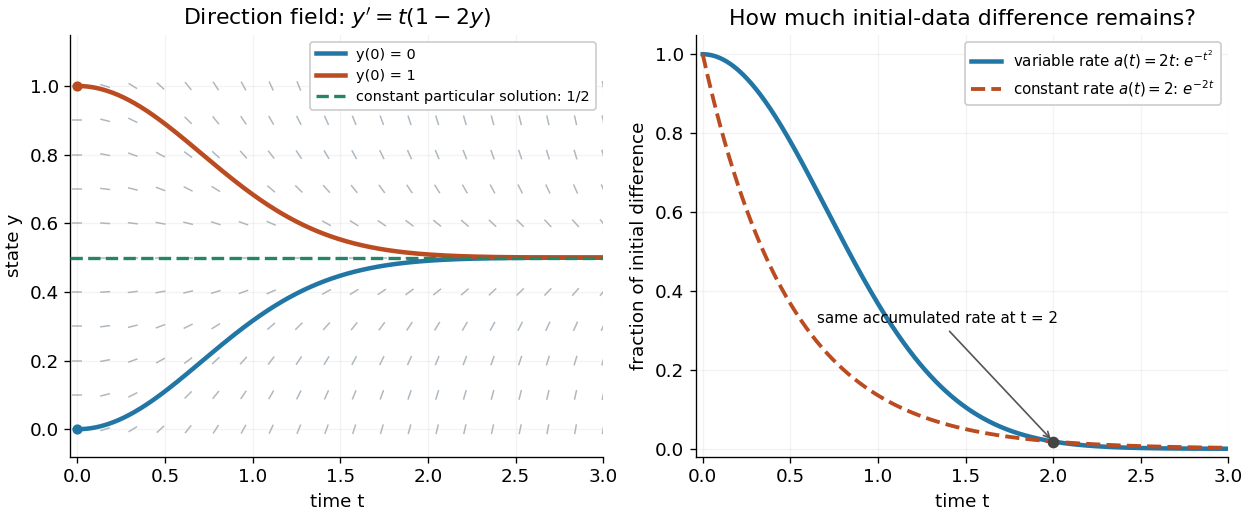
Variable-rate trajectories share a constant particular solution and forget initial data by a factor of exp minus t squared
. Details. 
The direction field shows the selected trajectory leaving its initially horizontal tangent line. For , the difference between any two solutions of a differential equation is multiplied by , rather than in the constant-rate example. This dependence on elapsed history is clearer if the exact formula is rewritten asFor , each contribution from the input at is weighted by the accumulated coefficient between and . The homogeneous solution remembers the initial condition; the particular solution given by the second term accumulates the forcing term with zero initial value. This decomposition differs from choosing a constant particular solution, but gives the same total. Initial-data memory tends to zero when ; a negative accumulated coefficient instead amplifies it. The reciprocal relation between integrating factor and homogeneous solution is developed in MIT's notes on solutions to linear first-order equations.
Why does the trick work? The fundamental theorem of calculus and chain rule give . Consequently the product rule givesIntegrating this identity and dividing by the positive exponential function produces the stated formula. Any nonzero constant multiple of works equally well; normalization is a convenience. This is the beauty of the method: a sum involving an unknown function becomes one exact derivative, leaving only an integral of known functions. See Oregon State's product-rule derivation. The related integrating factor for a differential one-form extends the idea of making an expression exact beyond this linear setting.
Second-order linear differential equation Created 2026-09-24 Updated 2026-11-05
A normalized second-order linear differential equation isLinearity concerns the unknown function and its derivatives; the coefficient functions can vary with . The equation is homogeneous when .
On an interval where are continuous, specifying and determines a unique solution. Two independent homogeneous solutions span the homogeneous solution space, while adding one particular solution gives every inhomogeneous solution. For , the basis makes those two initial degrees of freedom explicit.
Dominant eigenmode in a forced linear system Created 2026-09-24 Updated 2026-11-05
For a constant-coefficient linear ordinary differential equation system , the large-time response contains both homogeneous modes and modes introduced by the forcing. If is diagonalizable, an eigenbasis splits it into independent scalar equations; a Jordan block instead gives polynomial factors multiplying exponentials. Dominance compares their real exponential rates first, and polynomial powers when rates tie, after checking that the relevant coefficients are nonzero.
For , direct integration gives . The forcing creates the dominant decay rate , absent from the homogeneous equation. At resonance, gives : the polynomial enhancement still tends to zero. If a growing eigenmode has zero initial coefficient and is not forced in its direction, it contributes nothing to the solution. Thus the largest real part in the matrix spectrum alone need not describe a particular trajectory; the forcing and its modal projections matter.
Particular solution Created 2026-09-24 Updated 2026-10-14
A particular solution is any one solution of a forced linear differential equation. Every solution is the sum of that particular solution and an arbitrary homogeneous solution.
There are unlisted articles, also show them or only show them.