An integrating factor is a nonzero multiplier that makes a differential equation directly integrable. For a first-order linear differential equation, it gathers the unknown function and its derivative into one product rule expression. Suppose and are continuous functions on an interval containing , and consider the initial value problemDefine and . The exact solution of a differential equation throughout that interval isThe definite integral fixes , so the initial condition appears without an extra constant to determine. If the equation originally has a coefficient multiplying , first divide by that coefficient on an interval where it is nonzero; a zero of that coefficient needs separate attention. See OpenStax's first-order linear equations chapter for this normalization and the integrating factor procedure.
For a concrete balance, solve with . Here , so multiplying the entire ordinary differential equation gives . Accumulating from zero to givesThe computed values are , and . Its derivative is , which verifies exactly. Interpreting as a steady input and as proportional removal explains the shape: initially all input increases , then removal catches up. The constant particular solution balances input and removal, and the homogeneous solution is the transient response that corrects it to the initial condition. Because this autonomous differential equation has a time-independent right-hand side, is also an equilibrium point.
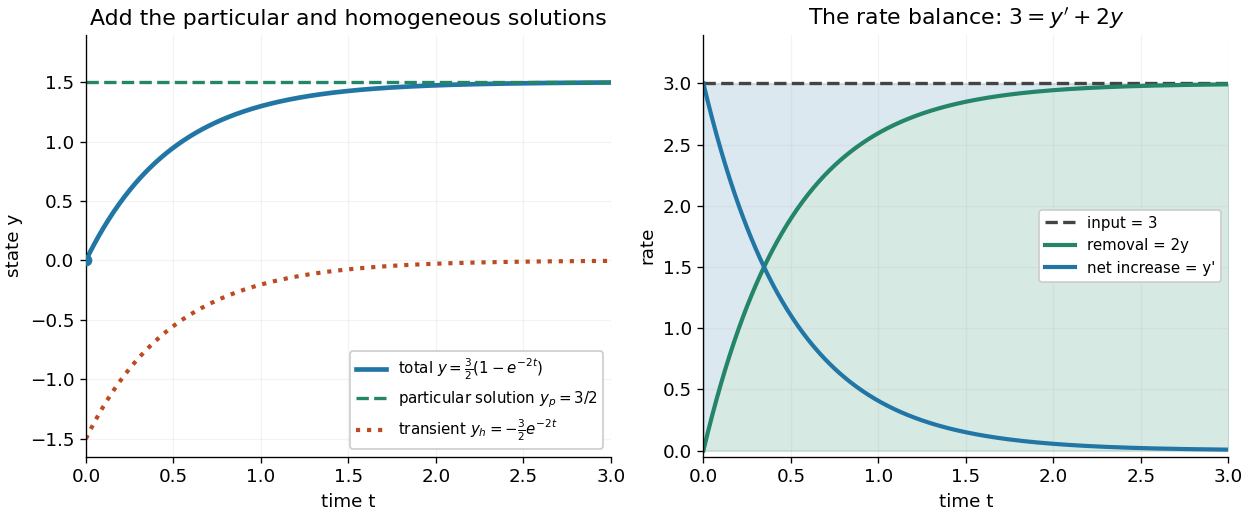

The first panel adds the particular solution and homogeneous solution; the second shows the same balance in rates, . This links the algebra to a physical accounting rule. Newton's law of cooling has this form with and , while an electrical circuit can have a varying input. In both cases the integrating factor systematically handles the input rather than requiring a guess for a particular solution.
Variable coefficients work just as directly. For , , the integrating factor is , andThus , and . The derivative verifies , including at zero, where both coefficient and input vanish. No division by is necessary. The general solution is : is a constant particular solution, and solves the associated homogeneous linear differential equation. Although this special forcing term admits a constant trajectory, this is a nonautonomous differential equation: it depends explicitly on time. Merely setting its right-hand side to zero at one instant would not establish a constant solution of a differential equation; at every state has zero slope.
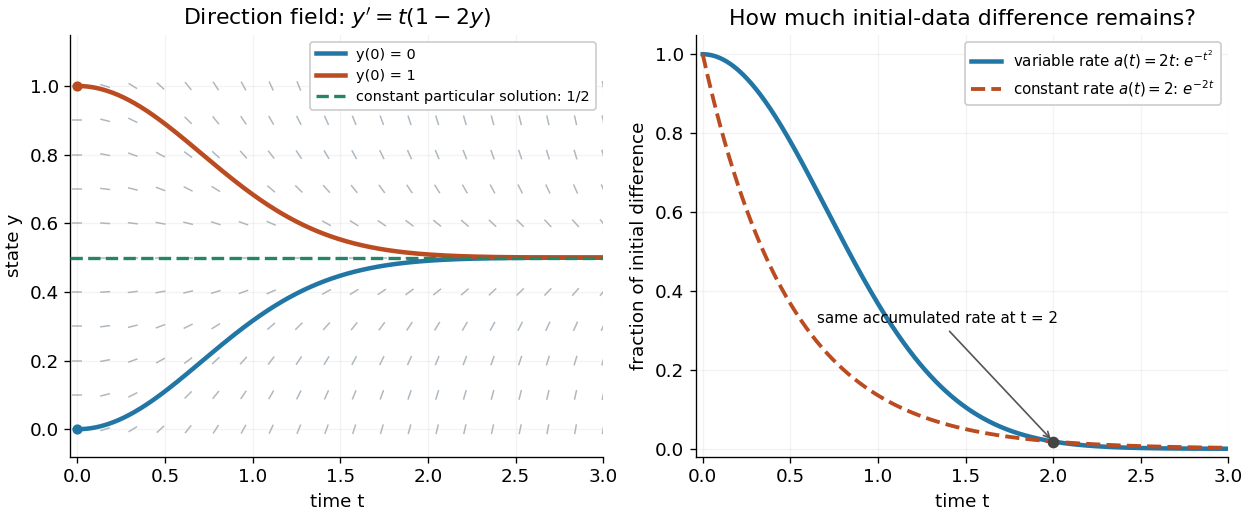
Variable-rate trajectories share a constant particular solution and forget initial data by a factor of exp minus t squared
. Details. 
The direction field shows the selected trajectory leaving its initially horizontal tangent line. For , the difference between any two solutions of a differential equation is multiplied by , rather than in the constant-rate example. This dependence on elapsed history is clearer if the exact formula is rewritten asFor , each contribution from the input at is weighted by the accumulated coefficient between and . The homogeneous solution remembers the initial condition; the particular solution given by the second term accumulates the forcing term with zero initial value. This decomposition differs from choosing a constant particular solution, but gives the same total. Initial-data memory tends to zero when ; a negative accumulated coefficient instead amplifies it. The reciprocal relation between integrating factor and homogeneous solution is developed in MIT's notes on solutions to linear first-order equations.
Why does the trick work? The fundamental theorem of calculus and chain rule give . Consequently the product rule givesIntegrating this identity and dividing by the positive exponential function produces the stated formula. Any nonzero constant multiple of works equally well; normalization is a convenience. This is the beauty of the method: a sum involving an unknown function becomes one exact derivative, leaving only an integral of known functions. See Oregon State's product-rule derivation. The related integrating factor for a differential one-form extends the idea of making an expression exact beyond this linear setting.
On an interval where , the displayed factor givesThis follows from . It gives a useful self-adjoint form but does not solve a general second-order ordinary differential equation, since the term remains. If , it does reduce to one integration for . Another reducible class has , because the original left side is then . These are sufficient special cases, not a classification of all solvable equations.
For with continuous , the integrating factor gives the displayed solution. It is continuous at the step and solves the differential equation classically on each side; the derivative jumps by one. The value assigned to the Heaviside step function at the single point zero does not affect the integral. A discontinuity in would instead produce an unintended delta term in its distributional derivative.
For the differential one-form , a nonzero integrating factor makes an exact differential form locally. If it equals , then , , and equality of mixed partial derivatives gives the displayed compatibility condition. Conversely this condition is local sufficiency for smooth coefficients on a small rectangle; global exactness additionally depends on the domain. Zeros of the multiplying factor can change the solution set, so equivalence is asserted only where the factor is nonzero.
For a differential one-form , seek a nonzero integrating factor . Expanding gives the displayed equation where . Such a factor exists locally when depends only on , and is . Likewise, a factor depending only on obeys where . The resulting product is an exact differential form on a sufficiently small regular domain; singular lines of the factor need separate treatment.
For a differential one-form , a monomial integrating factor exists on a chosen domain away from the axes when constants makeThis follows by expanding the exactness condition . When are sums of monomials, matching their coefficients often reduces the search for to a small linear system. Integrating then gives the implicit solution . Curves excluded by the multiplying factor, especially solutions on coordinate axes, must be tested in the original equation.
Articles by others on the same topic
There are currently no matching articles.