A normalized second-order linear differential equation isLinearity concerns the unknown function and its derivatives; the coefficient functions can vary with . The equation is homogeneous when .
On an interval where are continuous, specifying and determines a unique solution. Two independent homogeneous solutions span the homogeneous solution space, while adding one particular solution gives every inhomogeneous solution. For , the basis makes those two initial degrees of freedom explicit.
A point interaction concentrates a coefficient of a linear differential equation at a single interior point. On an interval , with , consider . The domain consists of continuous functions that are twice differentiable away from , with the required one-sided derivatives. Multiplication of the Dirac delta by means the unambiguous point value . It does not mean an undefined product of a delta with an arbitrary discontinuous function.
The equation is interpreted using distributional derivatives. Smooth forcing gives an ordinary equation on each side, with transmission conditions for a delta coefficient at the interaction. A delta potential in the one-dimensional Schrödinger equation is a physical example after choosing the corresponding sign and constants.
The boundary value problem on with Dirichlet boundary conditions has a unique solution for every continuous forcing and prescribed endpoint values exactly when . The left-normalized homogeneous solution iswhere . Continuity at and the transmission conditions for a delta coefficient give this formula. The final boundary condition fixes the initial slope unless the displayed endpoint value is zero. This is a one-dimensional kernel obstruction, analogous to the Fredholm alternative.
At resonance the normalized null function isFor and , the compatibility condition isIndeed, integrate on both sides of . The internal terms cancel by the matching derivative jumps, leaving . This equals the right-hand side. The initial-slope construction also proves sufficiency: when compatible there is a one-parameter family ; otherwise no solution exists.
For a point interaction in a second-order differential equation, the equation , with nonsingular continuous , requiresThe distributional second derivative across a jump explains both conditions: there is no derivative-of-delta source to balance a value jump, and the coefficients of the delta source must agree. In particular, without a point source, . With a unit point source at the same location, the condition is ; one must combine the two contributions rather than impose two incompatible jump conditions.
This equation has a regular singular point at zero and an irregular singular point at infinity. For a nonnegative integer , the solution analytic at zero with value one is the Laguerre polynomial . Its weighted self-adjoint form is , connecting it to the Laguerre differential operator on polynomials.
A Frobenius solution has the repeated indicial root . Equating coefficients gives the displayed recurrence relation. The resulting analytic solution is an entire function: its consecutive term ratio has magnitude asymptotic to . For an integer, the recurrence terminates and . The second local solution is independent and has a logarithmic term at zero; repeated indicial roots do not supply two independent analytic series.
The chain rule with gives and transforms the equation, away from zero, into . Thus its solution space is spanned by and . Both extend smoothly through the regular singular point at zero. Their even power series allow the independent data and to select the two solutions; every smooth solution has .
The homogeneous equation has linearly independent solutions and , with nonzero Wronskian . Setting converts the forced equation to . For resonant forcing , the particular response is . This substitution explains the extra powers of required by repeated-root resonance.
For a normalized second-order equation, a point is singular when its coefficient functions are not both analytic there. If multiplying them by the first and second powers of distance to the point makes them analytic, it is a regular singular point. This classification concerns the equation; some individual solutions may nevertheless extend analytically through the point.
For , the change of variables and converts into . The chain rule gives and . Thus . The prefactor cancels the derivative term introduced by inverting the independent variable.
A Liouville transformation of a second-order equation combines a change of independent variable with an amplitude factor that removes the induced first derivative. For , let be smooth with , put and . The chain rule givesand substitution of givesThis specifies which quantity receives the inverse-square-root rescaling.
Where , choose , so the principal term is one. The coordinate is and the original amplitude factor is . Neglecting the remaining coefficient-variation terms produces the exponential WKB approximation only when those terms are suitably small in the asymptotic regime. Turning points require a different local scaling; negative gives the corresponding oscillatory formulation.
For and , the change of variables convertsinto , where . The chain rule cancels the first-derivative terms. Thus and form a pair of linearly independent solutions, with Wronskian . This is a variable-speed reparametrization of the harmonic oscillator equation.
The Mathieu equation is the displayed linear differential equation with periodic coefficients. Floquet theory describes its bounded and exponentially growing solutions, while its periodic Mathieu characteristic values mark the edges of parametric resonance gaps. The forcing normalization matters: replacing by rescales both the constant and periodic coefficients.
The Mathieu characteristic values are the parameter values for which the Mathieu equation has the even periodic mode traditionally denoted , or the odd periodic mode . They are eigenvalues of with the corresponding periodic or antiperiodic boundary conditions. Their small- expansions can be derived by projecting onto a Fourier series and perturbing the resulting tridiagonal matrix.
This second-order ordinary differential equation has the independent entire Airy functions and as a standard basis. It is distinct from the dispersive PDE in Airy equation. Its general solution is .
On the unit interval, the weak form is , with on the zero-boundary Sobolev space. The nonnegative potential makes this form coercive in the derivative norm, and the Poincaré inequality makes that norm equivalent to the Sobolev norm. The Lax-Milgram theorem gives a unique solution. A conforming Ritz method minimizes the corresponding strictly convex quadratic energy and produces a symmetric positive-definite tridiagonal matrix for piecewise-linear hats.
For the Airy ordinary differential equation , a power series obeys and . Setting its first two coefficients to or givesEmpty products are one. The ratio test proves convergence on the whole complex plane. Termwise differentiation verifies the equation, and the initial normalization gives Wronskian one. By the Abel identity, the Wronskian remains one everywhere, so these solutions span the whole solution space.
Named after George Biddell Airy, the standard Airy functions solve the Airy ordinary differential equation. Their Wronskian is , so they form a fundamental solution pair, including for complex .
For define and . Both converge by Airy function decay. Integrating its differential equation gives . These moments convert a decaying vorticity profile into its velocity and displacement for three-layer long-wave shear-flow matching.
For a second-order linear differential equationthe substitution eliminates the first-derivative term and gives
For two real self-adjoint equations with continuous coefficients, and , between consecutive zeros of a nontrivial first solution a nontrivial second solution either has a zero or is proportional to the first there. This comparison controls oscillation through the coefficients.
If , then between consecutive zeros of a nontrivial solution ofthere is a zero of every nontrivial solution of , unless the two coefficients agree throughout that interval.
For solutions , the mixed WronskiansatisfiesIts endpoint signs between consecutive zeros of a positive force a zero of unless .
A power-series solution of a differential equation substitutes into the equation and equates coefficients of equal powers. The resulting recurrence relation expresses later coefficients in terms of the free initial coefficients.
For about zero, , so and . For a second-order linear ordinary differential equation with analytic normalized coefficients at , two free coefficients encode and . A formal coefficient calculation must still be accompanied by a convergence argument; at a regular singular point, the Frobenius method allows a leading noninteger power.
The Kummer differential equation isWhen , its solution analytic at zero and normalized to one is the confluent hypergeometric function of the first kindHere is the rising factorial. Substitution gives , explaining both the series and the excluded denominator parameters. For , a second local solution on a chosen logarithm branch is . Integer parameter differences require a separate limiting construction and can introduce logarithms. At excluded , the normalized analytic series is not generally defined; special terminating parameter combinations must be treated explicitly rather than by dividing by a zero denominator.[ref]
Putting in the displayed Kummer differential equation gives . Thus on a chosen branch, yielding . For and , one solution is and a normalized second Frobenius solution is . The analytic factors in both solutions have infinite radius of convergence, since their coefficient ratios tend to zero. The second solution still has a square-root branch at zero; an entire series factor does not remove a nonintegral Frobenius exponent.
Confluent hypergeometric functions solve the Kummer differential equation . The regular solution is the confluent hypergeometric function of the first kind; a second standard solution is conventionally denoted . The family arises by coalescing singular points of the Gauss hypergeometric equation.
For not a nonpositive integer, the regular solution normalized by has the power seriesHere is the rising factorial. Substitution into the Kummer differential equation proves the coefficient recurrence. This normalization agrees with NIST's definitions.
For two differentiable functions on an interval , their Wronskian is the functionThe order matters: exchanging and reverses the sign. For sufficiently differentiable functions, the Wronskian is the determinant .[ref]
1 Algebraic and Analytic Methods. NIST Digital Library of Mathematical Functions; §1.13(i), equation 1.13.4 and the following n-argument definition
The Wronskian measures whether the vectors and supply independent value-and-derivative data at that point. For real-valued functions, its absolute value is the area of the parallelogram they span. If a constant linear combination is zero throughout , then too. A nonzero Wronskian at even one point makes this pair of linear equations invertible and forces . Thus a nonzero Wronskian somewhere always proves linear independence of the functions on .
For an explicit example, the exponential functionssolve the same homogeneous linear differential equation on the whole real line: substitution gives and , respectively. Their Wronskian isFor the initial value problem , , the linear combination requires and . Hence , , and . The nonzero Wronskian makes the two initial conditions independently adjustable.
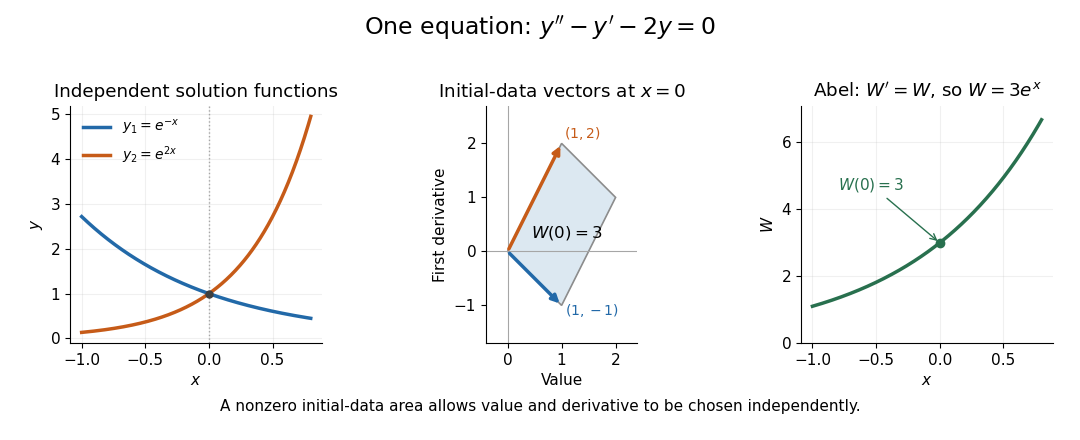
Independent exponential functions supply independent initial data, with Wronskian equal to the oriented parallelogram area
. Details. 
The stronger converse requires a common equation. Suppose solve with continuous functions on one interval . Then the functions are linearly independent if and only if their Wronskian is nonzero at one point, equivalently at every point. If , choose constants , not both zero, making satisfy . The superposition principle makes a solution of a differential equation for the same equation, and the uniqueness theorem for ordinary differential equations forces to be identically zero. This proves linear dependence.[ref]
The Wronskian. 18.03 Supplementary Notes by Haynes Miller; Chapter 15, The Wronskian, printed pp. 72–73: initial-data system (3) and the zero-or-nowhere-zero theorem
For arbitrary differentiable functions, an identically zero Wronskian need not imply linear dependence. Consider, on ,Both functions have three continuous derivatives. On each side of zero, is a constant multiple of , so ; at zero their values and first derivatives are all zero, so the Wronskian is zero there too. Nevertheless evaluated at gives , while evaluation at gives . Hence : these functions are linearly independent on the whole interval. There is no single constant multiplier valid on both sides of the common zero.
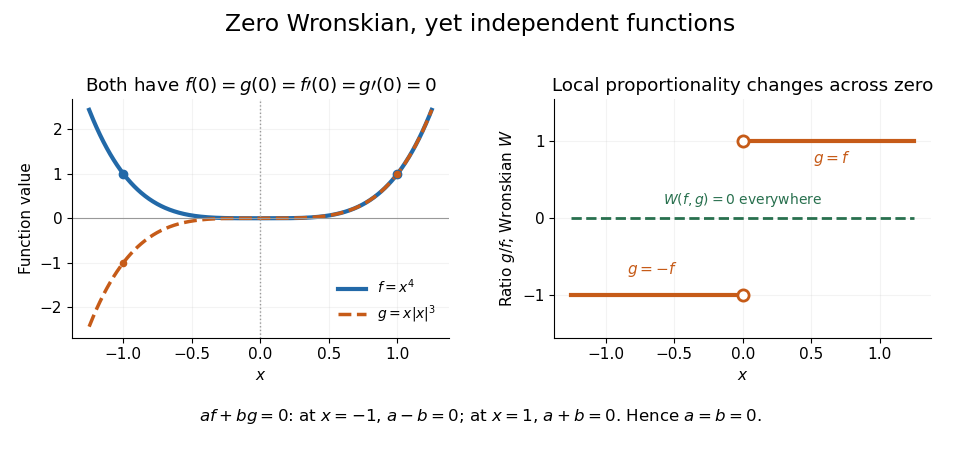
An identically zero Wronskian can coexist with linear independence when the common regular equation hypothesis is absent
. Details. 
These functions cannot both solve any equation with continuous functions throughout : even alone would contradict uniqueness because but is not identically zero. They do solve the singular equation , whose leading coefficient vanishes at zero. Dividing by gives only away from zero; Abel's identity cannot be applied across that point. The example pinpoints why checking the equation and its interval is essential before using a zero Wronskian to infer linear dependence.
Two differentiable functions can be linearly independent on a connected interval while their Wronskian vanishes everywhere. For example, let and . Both have a continuous first derivative, and their values and first derivatives vanish at zero. On either side of zero one of the functions is identically zero, so everywhere. Evaluating a constant linear combination at and forces .
The obstruction is that the two halves supply independent information without simultaneous nonzero value-and-derivative data at any point. For solutions of a common regular second-order linear differential equation, the uniqueness theorem for ordinary differential equations removes this possibility; Abel's identity gives the zero-or-nowhere-zero alternative for their Wronskian.
More precisely, let be solutions of a differential equation for the same homogeneous linear differential equationon an interval where are continuous functions. For any , Abel's identity givesOnly the coefficient of enters the evolution of the Wronskian. In an unnormalized equation , first use on an interval where and the coefficient ratios are continuous functions.[ref]
1 Algebraic and Analytic Methods. NIST Digital Library of Mathematical Functions; §1.13(i), equation 1.13.5 and the following coefficient-ratio explanation; stated there for analytic coefficients
The proof uses cancellation. Differentiating the Wronskian by the product rule and substituting the common equation givesMultiplying this first-order linear differential equation by the integrating factor gives . Since , the constant is , proving Abel's identity. This argument also covers without dividing by .
The exponential function is positive for real , so a real Wronskian either vanishes everywhere or has a fixed nonzero sign throughout . In the preceding example, and give immediately. If , every Wronskian of two solutions of a differential equation for that same equation is constant, regardless of . Thus Abel's identity can certify linear independence and find the denominator used in variation of parameters without explicit formulas for both solutions of a differential equation.
Variation of parameters replaces the constants in a complementary solution by functions to construct a particular solution.
For the inhomogeneous linear differential equation , assume are continuous functions on an interval , and are linearly independent homogeneous solutions there. With and , variation of parameters constructs the particular solutionThe Wronskian has no zeros on , so these quotients are defined. For , normalize first: , not .[ref]
To derive the formula, write and impose . This auxiliary choice removes extra terms from the first derivative. Substitution into the inhomogeneous linear differential equation leaves . The two linear equations for have determinant , and Cramer's rule givesIntegrating from makes . Arbitrary integration constants contribute only homogeneous solutions; adding supplies the general solution.
For a worked example, use the same homogeneous solutions and the forcing term in . With and ,Consequently the particular solution selected by zero initial conditions isIts value and first derivative vanish at zero. Direct substitution confirms the forcing term: the differential operator annihilates the last two terms and maps to . The two integrals therefore build a response from known homogeneous solutions, even when the forcing term has no convenient elementary guess.
Given a known solution of , reduction of order seeks another solution as . On an interval where , substitution cancels the terms containing and givesThis is first order in , soIts Wronskian with is , nonzero, proving independence. An additive constant in the integral merely adds a multiple of .
For and , the formula gives where . Although the integral factor has poles, the actual second solution continues smoothly through them. The reduction of order across a zero of the known solution explains why one continues the solution using the original regular equation rather than declaring the pole of an auxiliary integral a solution singularity.
Suppose has analytic near zero, , and a solution , with a positive integer. The indicial roots are . The Abel identity gives . Dividing by gives . Integrating this reduction of order expression from zero, multiplying by , and choosing proves the displayed normalized expansion. The integral's zero constant eliminates the added multiple of . Its nonzero Wronskian proves independence. In this setting the assumed exponent-zero solution prevents a logarithm in the constructed exponent- solution.
The integral representation is derived where . At a zero, its integral factor may have a pole while the product has a removable singularity. For regular coefficients, continue the actual second solution by its finite initial data and initial-value uniqueness; the Abel identity preserves a nonzero Wronskian. In the degree-one Legendre differential equation, and illustrate this cancellation at zero.
A Cauchy-Euler equation is a linear ordinary differential equation whose coefficient powers match their derivative orders, for exampleWith and , the chain rule gives and . Thus the equation becomes the constant-coefficient differential equation . In the homogeneous case, the power-law ansatz gives the indicial equation .
For , the repeated root yields . The logarithm is the transformed repeated-root factor . Negative real can be handled separately using , while complex powers require a chosen logarithm branch. The singular point at zero is not crossed automatically by the logarithmic coordinate.
For , write and . The chain rule gives , , and thereforeOn with homogeneous Dirichlet boundary conditions, the eigenfunctions are and the eigenvalues are . The weighted inner product with weight becomes , so their squared norms are and their orthogonality is exactly that of the Fourier sine series. The weight is the factor that makes this conjugacy preserve the inner product.
For a Cauchy-Euler equation, logarithmic coordinates turn scale changes in into translations in . With , the chain rule gives and . Consequently the Sturm-Liouville operator becomes . Its natural weighted inner product has measure , so this change of variable also preserves the norm when the transformed problem uses ordinary integration in . On with Dirichlet boundary conditions, the orthonormal eigenfunctions are and the eigenvalues are , for .
For on with zero endpoint values, the natural weighted inner product has measure . Set and . The chain rule gives , so with zero endpoints on . Moreover , so the transformation preserves the norm. The ordinary sine orthonormal eigenbasis therefore gives exactly the displayed spectrum and eigenfunctions for . The factor and the additive distinguish this problem from the operator with measure .
For , the logarithmic change of variable in a Sturm-Liouville problem sends this equation to on . The normalized eigenfunctions are , with eigenvalues . If every is nonzero, the Sturm-Liouville eigenfunction expansion givesIndeed the constant function has sine coefficients ; division by each eigenvalue solves the equation in the operator domain. The series is uniformly convergent, with coefficients , while applying the differential operator is justified in the weighted square-integrable sense. At a zero eigenvalue the solvability condition at a Sturm-Liouville eigenvalue must instead be checked: an odd resonant index makes the constant forcing incompatible, whereas an even resonant index permits solutions with an arbitrary multiple of that zero mode.
Normalize the second-order equation as . If every point other than zero and infinity is ordinary and both exceptions are at worst regular singular points, then and extend holomorphically across zero and stay bounded at infinity. Liouville's theorem makes them constants, yielding the displayed Euler-Cauchy equation. If both exceptions must be genuinely singular, exclude and , which make zero and infinity respectively ordinary.
An Euler-Cauchy equation has powers of the independent variable matching the derivative orders, for example . On , trying gives the algebraic equation . Distinct roots give two power solutions; a repeated root gives and .
The substitution explains the recipe: and , so the equation becomes a constant-coefficient differential equation. For , the repeated root is one and the solution is . Intervals crossing zero require separate attention because zero is a singular point of a differential equation.
Forthe power ansatz gives the indicial equation . Distinct roots give ; a repeated root gives on a chosen logarithm branch.
A power-law ansatz assumes that an unknown function is a monomial . Scale-invariant differential equations then reduce to an algebraic equation for the exponent .
An indicial equation determines candidate leading powers in a Frobenius solution near a regular singular point. Fornear , suppose and extend analytically to zero. Substituting with and collecting the lowest power givesIts roots are the indicial exponents. Subsequent powers determine the coefficient recurrence; the leading polynomial alone does not decide whether the second solution contains a logarithm.
For the Cauchy-Euler equation , . If , its complex roots give real solutions and on , exhibiting log-periodic oscillation.[ref]
An indicial root is a root of the indicial equation for a regular singular point. For a leading term as , its magnitude is , so positive real part gives decay and negative real part gives divergence. At zero real part, logarithmic factors and oscillation must also be checked.
For , the repeated root is zero. Its independent solutions and have the same indicial root but different boundedness. For roots , nonzero real solutions oscillate in with bounded magnitude and usually no limit at zero. Thus the sign of a real root is useful away from the borderline, but is not a complete boundedness rule for all Frobenius solutions.
An indicial exponent is a root of the indicial equation at a regular singular point. It gives the leading local power in a Frobenius method; resonant roots can require logarithmic terms.
A log-periodic oscillation is periodic in the logarithm of its argument, for example . Its successive zeros or extrema therefore occur at radii in a geometric progression.
The Legendre differential equation isFor a nonnegative integer , the polynomial solution normalized by is the Legendre polynomial . For example, , and satisfy their respective equations by substitution.
Its self-adjoint form is . On , regular solutions of distinct integer degrees are orthogonal with weight one; the vanishing endpoint coefficient removes the boundary term when the equations are multiplied crosswise and subtracted. The singular endpoints require care: a second independent solution generally has logarithmic endpoint behavior rather than being another regular polynomial. Rodrigues formula for Legendre polynomials constructs the normalized family explicitly.
For the Legendre differential equation , put . The equation becomes . Its indicial equation is . The exponent-zero power series obeys the displayed linear recurrence relation. For a nonnegative integer , it terminates at degree , giving a Legendre polynomial with . Every analytic solution at the endpoint is proportional to this one, since the recurrence determines all coefficients from .
The second independent solution has the local form , where is analytic near . Indeed, reduction of order gives , whose integrand is plus an analytic function. Rescale the second solution to obtain the unit coefficient of . Reflection gives the corresponding expansion at . This also proves the logarithmic divergence of the independent Legendre function of the second kind at each endpoint.
Substitute , , into the Legendre differential equation. The lowest powers give and ; subsequent powers give the recurrence in the title. Thus exponent zero has independent even and odd coefficients, while exponent one requires and represents the odd solution. Zero is an ordinary point of the equation, so the exponent-one choice simply selects a solution that vanishes there.
The singular points at bound the generic radius of convergence about zero by one. Every nonterminating parity recurrence has successive-coefficient ratio tending to one in the variable , giving radius exactly one. If is a nonnegative integer, choosing the parity of makes the recurrence terminate at degree , producing a Legendre polynomial with infinite radius. These are precisely the nonnegative parameters with a nonzero entire solution: even and odd parts of an entire solution would both have to be entire, so any nonzero nonterminating part is excluded.
For nonnegative integer , a second solution of the Legendre differential equation is obtained by reduction of order from as . Normalize it as and , with the usual Legendre polynomial recurrence relation for higher degrees. Inside , near and near . These follow from , in the integral. Poles in the integral at interior polynomial zeros cancel in the product, by reduction of order across a zero of the known solution. On , the integral from infinity defines the decaying normalization . For all bounded exterior solutions decay this way; for an additional constant solution remains bounded.
This second-order linear differential equation extends the Legendre differential equation by its order parameter . Its solutions are associated Legendre functions. In a degree-one potential problem, with , two explicit solutions are and . Their Wronskian with respect to is , so the two formulas are not a fundamental pair at or .
Associated Legendre functions solve . For integers and , the regular solution is , using a Legendre polynomial. It enters normalized spherical harmonics. Despite the traditional term associated Legendre polynomial, the factor is not a polynomial when is odd. Negative integer orders satisfy .
For orthonormal Legendre polynomials on , the polynomial represents evaluation at zero on polynomials of degree at most : . This follows by expanding in the orthonormal basis, or from the Riesz representation theorem. With and , orthonormality givesThe last identity telescopes using . The norms are unbounded: makes the sum dominate a divergent harmonic series. Thus the evaluation identities hold eventually for every fixed polynomial but cannot extend to convergence for every vector, by the Uniform boundedness principle. Point evaluation is also not defined on equivalence classes.
For normalized Legendre polynomials , parity makes the sign function orthogonal to every even index. Integrating the Legendre differential equation gives . The differentiated generating function gives the derivatives at zero and hence the displayed odd coefficients. The Parseval identity and squared norm two then evaluate .
This instance of Rodrigues' formula constructs the Legendre polynomial for every nonnegative integer . Put ; then . Differentiating times by the Leibniz rule gives for , which is the Legendre differential equation after reversing signs. The leading term of the normalized derivative is , proving its polynomial degree is exactly . At , the product contributes only the term with all derivatives on the second factor, giving . Thus the normalization is .
Differentiating the Legendre differential equation gives for . Multiply the equations for two distinct indices by the opposite polynomial and subtract. The endpoint term vanishes because of , giving the displayed weighted orthogonality. The zero polynomial is not a nonzero eigenfunction.
With , the generating function satisfies . Expanding in Legendre polynomials gives . Boundedness at zero removes , and the value at makes . Orthogonality then gives . The integral is , so . Uniform analyticity on compact subdiscs justifies the generating expansion and termwise calculations.
The three-term recurrenceturns multiplication by into coupling between adjacent Legendre multipoles.
For fixed ,
For fixed ,
The endpoint Laplace method for a Legendre polynomial ceases to localize when . On the scale , its real integral representation givesThe Modified Bessel function of the first kind equals one at and has large- behavior , matching the Hyperbolic Debye asymptotic for Legendre polynomials. This boundary layer resolves an increasingly steep function at an endpoint where its value remains fixed.
Articles by others on the same topic
There are currently no matching articles.