A characteristic exponent is a value for which an exponential mode solves the homogeneous constant-coefficient linear equation or system. Repeated exponents can give polynomial factors multiplying that exponential.
A fundamental system for a homogeneous linear ordinary differential equation of order on an interval is a basis of its vector space of homogeneous solutions. Every solution has a unique expression with constant coefficients. Under the usual continuity assumptions and a nonvanishing leading coefficient, a nonzero Wronskian at one point proves that solutions form such a system: their initial-value vectors are independent and span all possible initial data, and the Picard-Lindelöf theorem supplies uniqueness. For a first-order vector system, the corresponding columns form a fundamental matrix.
For with real and -periodic forcing, comparing Fourier coefficients gives . There is no vanishing denominator, including the constant mode. With real cosine and sine coefficients for and for , the equivalent equations giveWhenever termwise differentiation is justified, these formulas construct a periodic particular solution. For a forcing series with coefficients , the differentiated response coefficients are also summable, which supplies such a justification by uniform convergence. All other solutions add the homogeneous solution . Since this exponential cannot be periodic unless , the periodic solution is unique. This is also a simple example of how a linear equation changes the amplitude and phase of each harmonic independently.
A linear second-order ordinary differential equation with periodic coefficient. For accelerator beam optics, measures distance along the reference orbit and is the local transverse focusing strength.
For real constants with , a nonzero solution of the homogeneous linear differential equation has a sinusoidal factor exactly when the discriminant is negative. Indeed the characteristic polynomial has roots , where , giving . Real or repeated roots instead give real exponential functions, possibly multiplied by a linear polynomial. Oscillatory behaviour and decay are separate: decay requires .
Differentiating twice proves the displayed identity. It converts an exponentially weighted forced equation into a simple harmonic oscillator equation. If , the reduced homogeneous solutions are rather than as an independent pair. If the forcing contains a term at frequency , resonance requires an additional polynomial factor in a particular solution.
A linear ordinary differential equation has constant coefficients when the multipliers of the unknown function and its derivatives do not depend on the independent variable. The forcing may still vary. For the homogeneous equation , its characteristic equation of a constant-coefficient differential equation determines exponential solutions.
On an interval where the substitution is real and , a factor formed by exponentiation can remove inverse powers from the coefficients of a linear ordinary differential equation. Forthe substitution givesIt becomes a constant-coefficient differential equation exactly when , and . Derive this by the product rule; checking only the coefficient of is insufficient.
For pairwise distinct rates , the response isSet . Solving with gives ; solving the remaining first-order equation by an integrating factor gives the formula. Equivalently this is the convolution of with the zero-displacement unit-impulse response on the positive half-line. In the resonant case , the finite limit is . The apparent singularity of the distinct-rate expression is removable, and the limit exhibits the polynomial factor of a resonant exponential particular solution.
Recognizing the displayed product derivative reduces a homogeneous second-order equation to . On any interval where , its general solution is . For , the equation becomes . Data , give , with radius of convergence one. The poles occur at the three cube roots of unity. A solution singularity can disappear for a special numerator that cancels the corresponding factor, so an equation's singular point need not be a singularity of every solution.
For the homogeneous linear ordinary differential equation , substitute . Dividing by the nonzero exponential gives the polynomial equation . A simple root gives an exponential solution; a root of multiplicity gives for . Real equations admit real sine and cosine combinations of conjugate roots. These characteristic roots determine growth, decay and oscillation of the linearized modes.
Choose a finite trial family of polynomial-exponential or trigonometric functions for a particular solution, substitute it into a constant-coefficient linear equation, and solve for its coefficients. If the forcing exponent is a characteristic root of multiplicity , multiply the ordinary trial by to leave the homogeneous kernel. The method is efficient for forcing families preserved by differentiation.
For a real linear differential operator , one has . A forcing term written as the imaginary part of a polynomial times can therefore be handled by solving one complex equation, then taking the imaginary part. For , substituting gives . If the forcing frequency is resonant, the polynomial ansatz must include the appropriate additional power of .
For a constant-coefficient linear differential equation , where denotes differentiation, a simple root forces a resonant trial. Factor ; since , commuting the differential operators gives . Thus the displayed expression is a particular solution. More generally, if the root has multiplicity , the same factorization gives , so . This is the extra polynomial factor required by resonance in a differential equation.
Suppose two complex amplitudes satisfy and , with positive and . Then gives . A positive weighted norm avoids treating two coupling rates of different size as a single arithmetic sum. This is useful for nonautonomous linear ordinary differential equations and the bounded-modulation alpha-Omega growth estimate.
Newton's law of cooling models an object's temperature using a positive constant rate and ambient temperature . The displayed ordinary differential equation assumes one temperature represents the object, the environment remains at , and the proportional rate stays fixed over the modeled range. It also describes warming when . These are modeling assumptions: [ref]
https://ocw.mit.edu/courses/18-03sc-differential-equations-fall-2011/1ce2cf783d5f1d15ee411ec2e5f928ec_MIT18_03SCF11_s1_6text.pdf. MIT's notes on modeling by first-order linear equations
explain the proportional law through a tangent line approximation and caution about large temperature differences.Dimensional analysis requires to have units of inverse time. The product in the exponential function solution is therefore dimensionless. The equilibrium point attracts both warmer and colder starting states: the excess temperature undergoes exponential decay. See initial value problem for computed cooling times, direction field for the family of trajectories, and separable differential equation for a derivation.
For equal initial temperatures and the same Newton's law of cooling coefficient , compare a unit Dirac delta function cooling impulse at time one with unit-rate cooling on the interval from one to two. The impulse produces a temperature jump of minus one. The finite-duration forcing gives a continuous temperature with change while it is active. Relative to the common unforced cooling curve, the impulse contributes . Consequently the temperatures cross at , strictly between one and two. After time two the impulse-cooled body is warmer: the later cooling receives less subsequent exponential attenuation.
In an ideal linear temperature-dependent destruction model with equal warming and cooling durations, normalized temperature is during warming and during cooling. Integrating the destruction rate gives , the logarithm of the surviving-count reduction factor. If the endpoint destruction rate and thermal relaxation constant stay fixed, changing the temperature gap alone leaves this integral unchanged. This is a property of the stipulated model.
Under Newton's law of cooling with fixed ambient temperature and , an instantaneous jump at sets . The subsequent temperature is . Equivalently, for an initial temperature , the full solution isThis piecewise model has the distributional derivative equation , with the Dirac delta distribution representing the added temperature.
A heat transfer coefficient relates heat flux through a boundary to a temperature difference: . Its dimensions are power per area per temperature. In a quasistatic ice layer, atmospheric boundary resistance and conductive resistance add in series, giving effective conductance .
A homogeneous solution solves the associated linear equation with zero forcing. The difference of any two solutions to the same forced linear equation is homogeneous.
A homogeneous solution satisfies the associated homogeneous linear differential equation, obtained by setting the forcing term to zero. Such solutions form the kernel of the differential operator.
A particular solution is any one solution of a forced linear differential equation. Every solution is the sum of that particular solution and an arbitrary homogeneous solution.
The general solution of a differential equation is a family containing every solution, usually parameterized by arbitrary constants or initial data. For a forced linear ordinary differential equation, it is the sum of one particular solution and the general homogeneous solution.
After diagonalising a constant-coefficient system, each eigenmode satisfies a scalar forced equation. The large-time behaviour is determined by the largest exponential rate whose coefficient does not vanish, including rates introduced by the forcing.
A point interaction concentrates a coefficient of a linear differential equation at a single interior point. On an interval , with , consider . The domain consists of continuous functions that are twice differentiable away from , with the required one-sided derivatives. Multiplication of the Dirac delta by means the unambiguous point value . It does not mean an undefined product of a delta with an arbitrary discontinuous function.
The equation is interpreted using distributional derivatives. Smooth forcing gives an ordinary equation on each side, with transmission conditions for a delta coefficient at the interaction. A delta potential in the one-dimensional Schrödinger equation is a physical example after choosing the corresponding sign and constants.
The boundary value problem on with Dirichlet boundary conditions has a unique solution for every continuous forcing and prescribed endpoint values exactly when . The left-normalized homogeneous solution iswhere . Continuity at and the transmission conditions for a delta coefficient give this formula. The final boundary condition fixes the initial slope unless the displayed endpoint value is zero. This is a one-dimensional kernel obstruction, analogous to the Fredholm alternative.
At resonance the normalized null function isFor and , the compatibility condition isIndeed, integrate on both sides of . The internal terms cancel by the matching derivative jumps, leaving . This equals the right-hand side. The initial-slope construction also proves sufficiency: when compatible there is a one-parameter family ; otherwise no solution exists.
For a point interaction in a second-order differential equation, the equation , with nonsingular continuous , requiresThe distributional second derivative across a jump explains both conditions: there is no derivative-of-delta source to balance a value jump, and the coefficients of the delta source must agree. In particular, without a point source, . With a unit point source at the same location, the condition is ; one must combine the two contributions rather than impose two incompatible jump conditions.
This equation has a regular singular point at zero and an irregular singular point at infinity. For a nonnegative integer , the solution analytic at zero with value one is the Laguerre polynomial . Its weighted self-adjoint form is , connecting it to the Laguerre differential operator on polynomials.
A Frobenius solution has the repeated indicial root . Equating coefficients gives the displayed recurrence relation. The resulting analytic solution is an entire function: its consecutive term ratio has magnitude asymptotic to . For an integer, the recurrence terminates and . The second local solution is independent and has a logarithmic term at zero; repeated indicial roots do not supply two independent analytic series.
The chain rule with gives and transforms the equation, away from zero, into . Thus its solution space is spanned by and . Both extend smoothly through the regular singular point at zero. Their even power series allow the independent data and to select the two solutions; every smooth solution has .
The homogeneous equation has linearly independent solutions and , with nonzero Wronskian . Setting converts the forced equation to . For resonant forcing , the particular response is . This substitution explains the extra powers of required by repeated-root resonance.
For a normalized second-order equation, a point is singular when its coefficient functions are not both analytic there. If multiplying them by the first and second powers of distance to the point makes them analytic, it is a regular singular point. This classification concerns the equation; some individual solutions may nevertheless extend analytically through the point.
For , the change of variables and converts into . The chain rule gives and . Thus . The prefactor cancels the derivative term introduced by inverting the independent variable.
A smooth invertible change of variables in introduces a first derivative in time. Rescaling by removes it. Choosing locally for produces the constant leading coefficient used in the WKB approximation; negative requires a complex branch or the corresponding oscillatory real formulation.
For and , the change of variables convertsinto , where . The chain rule cancels the first-derivative terms. Thus and form a pair of linearly independent solutions, with Wronskian . This is a variable-speed reparametrization of the harmonic oscillator equation.
The Mathieu equation is the displayed linear differential equation with periodic coefficients. Floquet theory describes its bounded and exponentially growing solutions, while its periodic Mathieu characteristic values mark the edges of parametric resonance gaps. The forcing normalization matters: replacing by rescales both the constant and periodic coefficients.
The Mathieu characteristic values are the parameter values for which the Mathieu equation has the even periodic mode traditionally denoted , or the odd periodic mode . They are eigenvalues of with the corresponding periodic or antiperiodic boundary conditions. Their small- expansions can be derived by projecting onto a Fourier series and perturbing the resulting tridiagonal matrix.
This second-order ordinary differential equation has the independent entire Airy functions and as a standard basis. It is distinct from the dispersive PDE in Airy equation. Its general solution is .
On the unit interval, the weak form is , with on the zero-boundary Sobolev space. The nonnegative potential makes this form coercive in the derivative norm, and the Poincaré inequality makes that norm equivalent to the Sobolev norm. The Lax-Milgram theorem gives a unique solution. A conforming Ritz method minimizes the corresponding strictly convex quadratic energy and produces a symmetric positive-definite tridiagonal matrix for piecewise-linear hats.
For the Airy ordinary differential equation , a power series obeys and . Setting its first two coefficients to or givesEmpty products are one. The ratio test proves convergence on the whole complex plane. Termwise differentiation verifies the equation, and the initial normalization gives Wronskian one. By the Abel identity, the Wronskian remains one everywhere, so these solutions span the whole solution space.
Named after George Biddell Airy, the standard Airy functions solve the Airy ordinary differential equation. Their Wronskian is , so they form a fundamental solution pair, including for complex .
For define and . Both converge by Airy function decay. Integrating its differential equation gives . These moments convert a decaying vorticity profile into its velocity and displacement for three-layer long-wave shear-flow matching.
For a second-order linear differential equationthe substitution eliminates the first-derivative term and gives
For two real self-adjoint equations with continuous coefficients, and , between consecutive zeros of a nontrivial first solution a nontrivial second solution either has a zero or is proportional to the first there. This comparison controls oscillation through the coefficients.
If , then between consecutive zeros of a nontrivial solution ofthere is a zero of every nontrivial solution of , unless the two coefficients agree throughout that interval.
For solutions , the mixed WronskiansatisfiesIts endpoint signs between consecutive zeros of a positive force a zero of unless .
Kummer's equation isIts solution analytic at zero is the confluent hypergeometric function of the first kindWhen is not an integer, a second local solution is
Putting in the displayed Kummer differential equation gives . Thus on a chosen branch, yielding . For and , one solution is and a normalized second Frobenius solution is . The analytic factors in both solutions have infinite radius of convergence, since their coefficient ratios tend to zero. The second solution still has a square-root branch at zero; an entire series factor does not remove a nonintegral Frobenius exponent.
Confluent hypergeometric functions solve the Kummer differential equation . The regular solution is the confluent hypergeometric function of the first kind; a second standard solution is conventionally denoted . The family arises by coalescing singular points of the Gauss hypergeometric equation.
For not a nonpositive integer, the regular solution normalized by has the power seriesHere is the rising factorial. Substitution into the Kummer differential equation proves the coefficient recurrence. This normalization agrees with NIST's definitions.
For two differentiable functions on an interval , their Wronskian is the functionThe order matters: exchanging and reverses the sign. For sufficiently differentiable functions, the Wronskian is the determinant .[ref]
1 Algebraic and Analytic Methods. NIST Digital Library of Mathematical Functions; §1.13(i), equation 1.13.4 and the following n-argument definition
The Wronskian measures whether the vectors and supply independent value-and-derivative data at that point. For real-valued functions, its absolute value is the area of the parallelogram they span. If a constant linear combination is zero throughout , then too. A nonzero Wronskian at even one point makes this pair of linear equations invertible and forces . Thus a nonzero Wronskian somewhere always proves linear independence of the functions on .
For an explicit example, the exponential functionssolve the same homogeneous linear differential equation on the whole real line: substitution gives and , respectively. Their Wronskian isFor the initial value problem , , the linear combination requires and . Hence , , and . The nonzero Wronskian makes the two initial conditions independently adjustable.
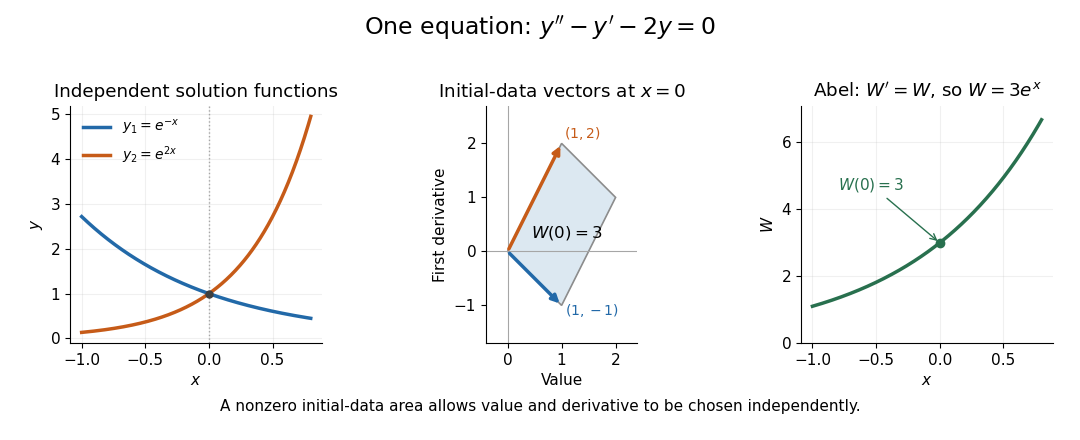
Independent exponential functions supply independent initial data, with Wronskian equal to the oriented parallelogram area
. Details. The stronger converse requires a common equation. Suppose solve with continuous functions on one interval . Then the functions are linearly independent if and only if their Wronskian is nonzero at one point, equivalently at every point. If , choose constants , not both zero, making satisfy . The superposition principle makes a solution of a differential equation for the same equation, and the uniqueness theorem for ordinary differential equations forces to be identically zero. This proves linear dependence.[ref]
The Wronskian. 18.03 Supplementary Notes by Haynes Miller; Chapter 15, The Wronskian, printed pp. 72–73: initial-data system (3) and the zero-or-nowhere-zero theorem
For arbitrary differentiable functions, an identically zero Wronskian need not imply linear dependence. Consider, on ,Both functions have three continuous derivatives. On each side of zero, is a constant multiple of , so ; at zero their values and first derivatives are all zero, so the Wronskian is zero there too. Nevertheless evaluated at gives , while evaluation at gives . Hence : these functions are linearly independent on the whole interval. There is no single constant multiplier valid on both sides of the common zero.
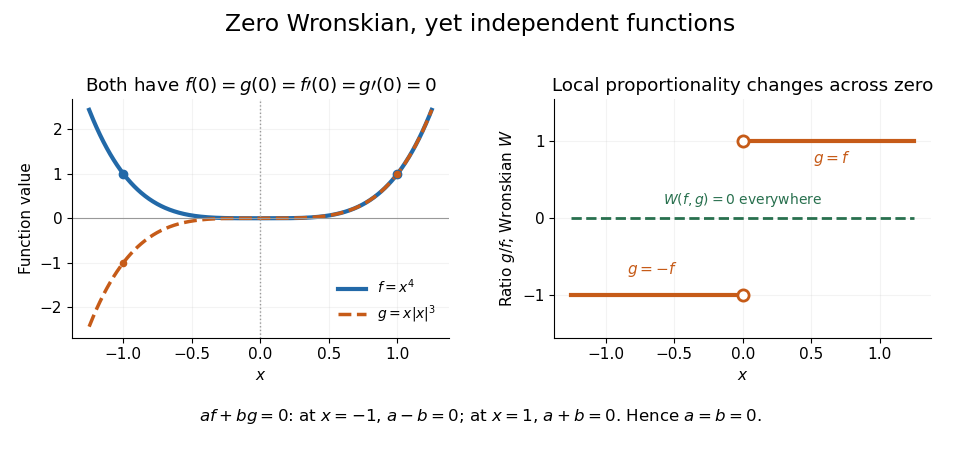
An identically zero Wronskian can coexist with linear independence when the common regular equation hypothesis is absent
. Details. These functions cannot both solve any equation with continuous functions throughout : even alone would contradict uniqueness because but is not identically zero. They do solve the singular equation , whose leading coefficient vanishes at zero. Dividing by gives only away from zero; Abel's identity cannot be applied across that point. The example pinpoints why checking the equation and its interval is essential before using a zero Wronskian to infer linear dependence.
Two differentiable functions can be linearly independent on a connected interval while their Wronskian vanishes everywhere. For example, let and . Both have a continuous first derivative, and their values and first derivatives vanish at zero. On either side of zero one of the functions is identically zero, so everywhere. Evaluating a constant linear combination at and forces .
The obstruction is that the two halves supply independent information without simultaneous nonzero value-and-derivative data at any point. For solutions of a common regular second-order linear differential equation, the uniqueness theorem for ordinary differential equations removes this possibility; Abel's identity gives the zero-or-nowhere-zero alternative for their Wronskian.
More precisely, let be solutions of a differential equation for the same homogeneous linear differential equationon an interval where are continuous functions. For any , Abel's identity givesOnly the coefficient of enters the evolution of the Wronskian. In an unnormalized equation , first use on an interval where and the coefficient ratios are continuous functions.[ref]
1 Algebraic and Analytic Methods. NIST Digital Library of Mathematical Functions; §1.13(i), equation 1.13.5 and the following coefficient-ratio explanation; stated there for analytic coefficients
The proof uses cancellation. Differentiating the Wronskian by the product rule and substituting the common equation givesMultiplying this first-order linear differential equation by the integrating factor gives . Since , the constant is , proving Abel's identity. This argument also covers without dividing by .
The exponential function is positive for real , so a real Wronskian either vanishes everywhere or has a fixed nonzero sign throughout . In the preceding example, and give immediately. If , every Wronskian of two solutions of a differential equation for that same equation is constant, regardless of . Thus Abel's identity can certify linear independence and find the denominator used in variation of parameters without explicit formulas for both solutions of a differential equation.
Variation of parameters replaces the constants in a complementary solution by functions to construct a particular solution.
For the inhomogeneous linear differential equation , assume are continuous functions on an interval , and are linearly independent homogeneous solutions there. With and , variation of parameters constructs the particular solutionThe Wronskian has no zeros on , so these quotients are defined. For , normalize first: , not .[ref]
To derive the formula, write and impose . This auxiliary choice removes extra terms from the first derivative. Substitution into the inhomogeneous linear differential equation leaves . The two linear equations for have determinant , and Cramer's rule givesIntegrating from makes . Arbitrary integration constants contribute only homogeneous solutions; adding supplies the general solution.
For a worked example, use the same homogeneous solutions and the forcing term in . With and ,Consequently the particular solution selected by zero initial conditions isIts value and first derivative vanish at zero. Direct substitution confirms the forcing term: the differential operator annihilates the last two terms and maps to . The two integrals therefore build a response from known homogeneous solutions, even when the forcing term has no convenient elementary guess.
Given one nonzero solution of a homogeneous second-order linear equation, reduction of order constructs a second by writing it as a variable multiple of the first.
Suppose has analytic near zero, , and a solution , with a positive integer. The indicial roots are . The Abel identity gives . Dividing by gives . Integrating this reduction of order expression from zero, multiplying by , and choosing proves the displayed normalized expansion. The integral's zero constant eliminates the added multiple of . Its nonzero Wronskian proves independence. In this setting the assumed exponent-zero solution prevents a logarithm in the constructed exponent- solution.
The integral representation is derived where . At a zero, its integral factor may have a pole while the product has a removable singularity. For regular coefficients, continue the actual second solution by its finite initial data and initial-value uniqueness; the Abel identity preserves a nonzero Wronskian. In the degree-one Legendre differential equation, and illustrate this cancellation at zero.
A Cauchy–Euler equation has powers of the independent variable matched to derivative order and is solved using power laws or a logarithmic change of variable.
For , write and . The chain rule gives , , and thereforeOn with homogeneous Dirichlet boundary conditions, the eigenfunctions are and the eigenvalues are . The weighted inner product with weight becomes , so their squared norms are and their orthogonality is exactly that of the Fourier sine series. The weight is the factor that makes this conjugacy preserve the inner product.
For a Cauchy-Euler equation, logarithmic coordinates turn scale changes in into translations in . With , the chain rule gives and . Consequently the Sturm-Liouville operator becomes . Its natural weighted inner product has measure , so this change of variable also preserves the norm when the transformed problem uses ordinary integration in . On with Dirichlet boundary conditions, the orthonormal eigenfunctions are and the eigenvalues are , for .
For on with zero endpoint values, the natural weighted inner product has measure . Set and . The chain rule gives , so with zero endpoints on . Moreover , so the transformation preserves the norm. The ordinary sine orthonormal eigenbasis therefore gives exactly the displayed spectrum and eigenfunctions for . The factor and the additive distinguish this problem from the operator with measure .
For , the logarithmic change of variable in a Sturm-Liouville problem sends this equation to on . The normalized eigenfunctions are , with eigenvalues . If every is nonzero, the Sturm-Liouville eigenfunction expansion givesIndeed the constant function has sine coefficients ; division by each eigenvalue solves the equation in the operator domain. The series is uniformly convergent, with coefficients , while applying the differential operator is justified in the weighted square-integrable sense. At a zero eigenvalue the solvability condition at a Sturm-Liouville eigenvalue must instead be checked: an odd resonant index makes the constant forcing incompatible, whereas an even resonant index permits solutions with an arbitrary multiple of that zero mode.
Normalize the second-order equation as . If every point other than zero and infinity is ordinary and both exceptions are at worst regular singular points, then and extend holomorphically across zero and stay bounded at infinity. Liouville's theorem makes them constants, yielding the displayed Euler-Cauchy equation. If both exceptions must be genuinely singular, exclude and , which make zero and infinity respectively ordinary.
Forthe power ansatz gives the indicial equation . Distinct roots give ; a repeated root gives on a chosen logarithm branch.
A power-law ansatz assumes that an unknown function is a monomial . Scale-invariant differential equations then reduce to an algebraic equation for the exponent .
An indicial equation is the algebraic equation for the leading exponent of a power-law or Frobenius solution near a regular singular point.
An indicial root is a root of the indicial equation obtained from a power-law ansatz. For a Cauchy-Euler differential equation, such roots give the exponents of its power solutions. Their sign determines which modes remain bounded near a singular endpoint.
An indicial exponent is a root of the indicial equation at a regular singular point. It gives the leading local power in a Frobenius method; resonant roots can require logarithmic terms.
A log-periodic oscillation is periodic in the logarithm of its argument, for example . Its successive zeros or extrema therefore occur at radii in a geometric progression.
The equation has the Legendre polynomial of degree as its normalized regular polynomial solution when is a nonnegative integer.
For the Legendre differential equation , put . The equation becomes . Its indicial equation is . The exponent-zero power series obeys the displayed linear recurrence relation. For a nonnegative integer , it terminates at degree , giving a Legendre polynomial with . Every analytic solution at the endpoint is proportional to this one, since the recurrence determines all coefficients from .
The second independent solution has the local form , where is analytic near . Indeed, reduction of order gives , whose integrand is plus an analytic function. Rescale the second solution to obtain the unit coefficient of . Reflection gives the corresponding expansion at . This also proves the logarithmic divergence of the independent Legendre function of the second kind at each endpoint.
Substitute , , into the Legendre differential equation. The lowest powers give and ; subsequent powers give the recurrence in the title. Thus exponent zero has independent even and odd coefficients, while exponent one requires and represents the odd solution. Zero is an ordinary point of the equation, so the exponent-one choice simply selects a solution that vanishes there.
The singular points at bound the generic radius of convergence about zero by one. Every nonterminating parity recurrence has successive-coefficient ratio tending to one in the variable , giving radius exactly one. If is a nonnegative integer, choosing the parity of makes the recurrence terminate at degree , producing a Legendre polynomial with infinite radius. These are precisely the nonnegative parameters with a nonzero entire solution: even and odd parts of an entire solution would both have to be entire, so any nonzero nonterminating part is excluded.
For nonnegative integer , a second solution of the Legendre differential equation is obtained by reduction of order from as . Normalize it as and , with the usual Legendre polynomial recurrence relation for higher degrees. Inside , near and near . These follow from , in the integral. Poles in the integral at interior polynomial zeros cancel in the product, by reduction of order across a zero of the known solution. On , the integral from infinity defines the decaying normalization . For all bounded exterior solutions decay this way; for an additional constant solution remains bounded.
This second-order linear differential equation extends the Legendre differential equation by its order parameter . Its solutions are associated Legendre functions. In a degree-one potential problem, with , two explicit solutions are and . Their Wronskian with respect to is , so the two formulas are not a fundamental pair at or .
Associated Legendre functions solve . For integers and , the regular solution is , using a Legendre polynomial. It enters normalized spherical harmonics. Despite the traditional term associated Legendre polynomial, the factor is not a polynomial when is odd. Negative integer orders satisfy .
For orthonormal Legendre polynomials on , the polynomial represents evaluation at zero on polynomials of degree at most : . This follows by expanding in the orthonormal basis, or from the Riesz representation theorem. With and , orthonormality givesThe last identity telescopes using . The norms are unbounded: makes the sum dominate a divergent harmonic series. Thus the evaluation identities hold eventually for every fixed polynomial but cannot extend to convergence for every vector, by the Uniform boundedness principle. Point evaluation is also not defined on equivalence classes.
For normalized Legendre polynomials , parity makes the sign function orthogonal to every even index. Integrating the Legendre differential equation gives . The differentiated generating function gives the derivatives at zero and hence the displayed odd coefficients. The Parseval identity and squared norm two then evaluate .
This instance of Rodrigues' formula constructs the Legendre polynomial for every nonnegative integer . Put ; then . Differentiating times by the Leibniz rule gives for , which is the Legendre differential equation after reversing signs. The leading term of the normalized derivative is , proving its polynomial degree is exactly . At , the product contributes only the term with all derivatives on the second factor, giving . Thus the normalization is .
Differentiating the Legendre differential equation gives for . Multiply the equations for two distinct indices by the opposite polynomial and subtract. The endpoint term vanishes because of , giving the displayed weighted orthogonality. The zero polynomial is not a nonzero eigenfunction.
With , the generating function satisfies . Expanding in Legendre polynomials gives . Boundedness at zero removes , and the value at makes . Orthogonality then gives . The integral is , so . Uniform analyticity on compact subdiscs justifies the generating expansion and termwise calculations.
The three-term recurrenceturns multiplication by into coupling between adjacent Legendre multipoles.
For fixed ,
For fixed ,
The endpoint Laplace method for a Legendre polynomial ceases to localize when . On the scale , its real integral representation givesThe Modified Bessel function of the first kind equals one at and has large- behavior , matching the Hyperbolic Debye asymptotic for Legendre polynomials. This boundary layer resolves an increasingly steep function at an endpoint where its value remains fixed.
A first-order linear differential equation has the form . Multiplication by an integrating factor satisfying turns it into .
Let and , with zero initial data. For , the Laplace transform time-shift rule gives the displayed response, since the transform of the input is and the equation supplies the factor . Equivalently, integrate the impulse response over the active pulse. Before the solution is zero; during the pulse it is ; after it is . The solution is continuous at both switching times. At take the limit, giving linear growth during the pulse and the constant afterward. Positive gives growing memory, while negative gives decay after forcing stops.
For , the retarded impulse response of is the displayed function, with the Heaviside step function. The corresponding convolution is the unique solution tending to zero in the remote past whenever the integral exists and has that limit. For example, bounded forcing that tends to zero as satisfies these conditions. A general forcing need not: admits no such solution. A unit-duration pulse with gives before zero, between zero and one, and thereafter.
For , subtracting an appropriate homogeneous solution from the particular solution removes its apparent singularity as . The resulting derivative in the parameter produces the resonant particular solution . The arbitrary constant must be reparametrized before taking the limit.
An integrating factor is a nonzero multiplier that makes a differential equation directly integrable. For a first-order linear differential equation, it gathers the unknown function and its derivative into one product rule expression. Suppose and are continuous functions on an interval containing , and consider the initial value problemDefine and . The exact solution of a differential equation throughout that interval isThe definite integral fixes , so the initial condition appears without an extra constant to determine. If the equation originally has a coefficient multiplying , first divide by that coefficient on an interval where it is nonzero; a zero of that coefficient needs separate attention. See OpenStax's first-order linear equations chapter for this normalization and the integrating factor procedure.
For a concrete balance, solve with . Here , so multiplying the entire ordinary differential equation gives . Accumulating from zero to givesThe computed values are , and . Its derivative is , which verifies exactly. Interpreting as a steady input and as proportional removal explains the shape: initially all input increases , then removal catches up. The constant particular solution balances input and removal, and the homogeneous solution is the transient response that corrects it to the initial condition. Because this autonomous differential equation has a time-independent right-hand side, is also an equilibrium point.
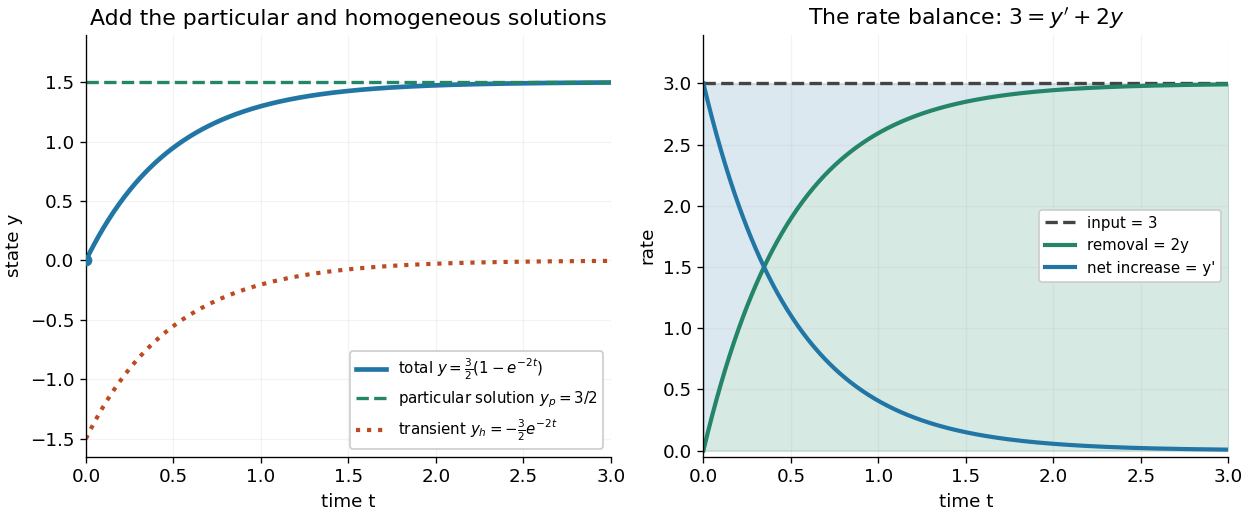


The first panel adds the particular solution and homogeneous solution; the second shows the same balance in rates, . This links the algebra to a physical accounting rule. Newton's law of cooling has this form with and , while an electrical circuit can have a varying input. In both cases the integrating factor systematically handles the input rather than requiring a guess for a particular solution.
Variable coefficients work just as directly. For , , the integrating factor is , andThus , and . The derivative verifies , including at zero, where both coefficient and input vanish. No division by is necessary. The general solution is : is a constant particular solution, and solves the associated homogeneous linear differential equation. Although this special forcing term admits a constant trajectory, this is a nonautonomous differential equation: it depends explicitly on time. Merely setting its right-hand side to zero at one instant would not establish a constant solution of a differential equation; at every state has zero slope.
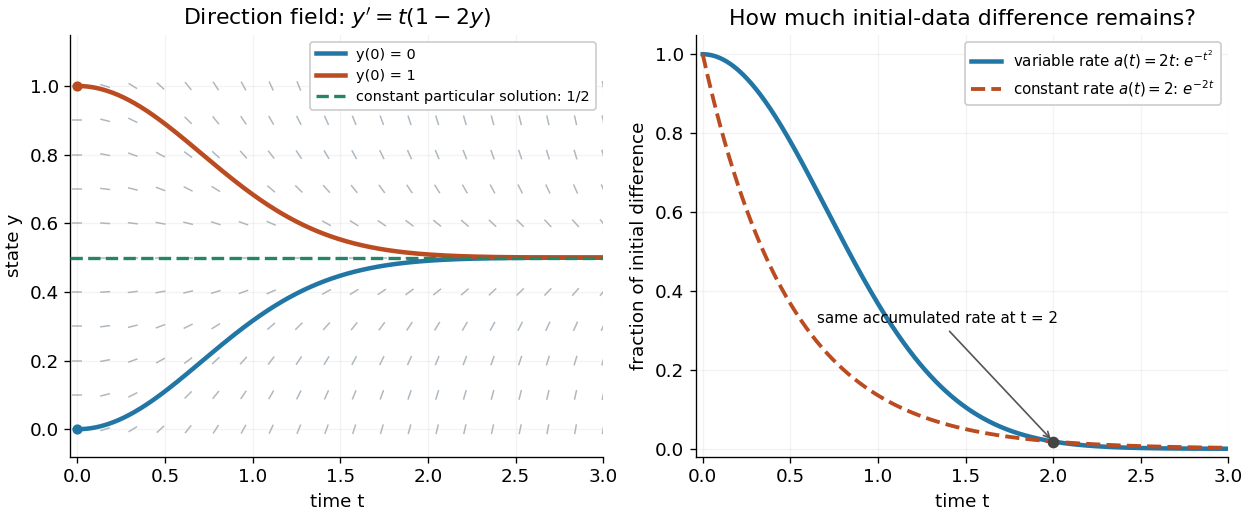
Variable-rate trajectories share a constant particular solution and forget initial data by a factor of exp minus t squared
. Details. 
The direction field shows the selected trajectory leaving its initially horizontal tangent line. For , the difference between any two solutions of a differential equation is multiplied by , rather than in the constant-rate example. This dependence on elapsed history is clearer if the exact formula is rewritten asFor , each contribution from the input at is weighted by the accumulated coefficient between and . The homogeneous solution remembers the initial condition; the particular solution given by the second term accumulates the forcing term with zero initial value. This decomposition differs from choosing a constant particular solution, but gives the same total. Initial-data memory tends to zero when ; a negative accumulated coefficient instead amplifies it. The reciprocal relation between integrating factor and homogeneous solution is developed in MIT's notes on solutions to linear first-order equations.
Why does the trick work? The fundamental theorem of calculus and chain rule give . Consequently the product rule givesIntegrating this identity and dividing by the positive exponential function produces the stated formula. Any nonzero constant multiple of works equally well; normalization is a convenience. This is the beauty of the method: a sum involving an unknown function becomes one exact derivative, leaving only an integral of known functions. See Oregon State's product-rule derivation. The related integrating factor for a differential one-form extends the idea of making an expression exact beyond this linear setting.
On an interval where , the displayed factor givesThis follows from . It gives a useful self-adjoint form but does not solve a general second-order ordinary differential equation, since the term remains. If , it does reduce to one integration for . Another reducible class has , because the original left side is then . These are sufficient special cases, not a classification of all solvable equations.
For with continuous , the integrating factor gives the displayed solution. It is continuous at the step and solves the differential equation classically on each side; the derivative jumps by one. The value assigned to the Heaviside step function at the single point zero does not affect the integral. A discontinuity in would instead produce an unintended delta term in its distributional derivative.
For the differential one-form , a nonzero integrating factor makes an exact differential form locally. If it equals , then , , and equality of mixed partial derivatives gives the displayed compatibility condition. Conversely this condition is local sufficiency for smooth coefficients on a small rectangle; global exactness additionally depends on the domain. Zeros of the multiplying factor can change the solution set, so equivalence is asserted only where the factor is nonzero.
For a differential one-form , seek a nonzero integrating factor . Expanding gives the displayed equation where . Such a factor exists locally when depends only on , and is . Likewise, a factor depending only on obeys where . The resulting product is an exact differential form on a sufficiently small regular domain; singular lines of the factor need separate treatment.
Articles were limited to the first 100 out of 115 total.
Articles by others on the same topic
There are currently no matching articles.