In a finite market, absence of arbitrage is equivalent to the existence of an equivalent martingale measure. If that measure is unique, every contingent claim has a unique no-arbitrage price given by its discounted expectation.
Let be the discounted gains of finitely many financial assets on any probability space. Tilting the physical probability measure by a normalized multiple of makes integrable without changing null events. The positive-weight expectation cone alternative then says either a bounded strictly positive weight makes the weighted gain expectation zero, or a deterministic risky holding gives an arbitrage. Normalizing the weight yields an equivalent martingale measure. Conversely, under such a measure a nonnegative terminal gain with zero initial price has zero expectation, and must vanish almost surely. This proves the one-period fundamental theorem of asset pricing without assuming physical integrability of asset gains.
For a finite-dimensional discounted gain random vector , absence of arbitrage means almost surely only when almost surely. Let and minimize on the orthogonal complement . The Gaussian damping makes finite and differentiable without physical integrability assumptions on . Every nonzero direction in has negative gains on an event of positive probability; compactness of directions proves coercivity. At a minimizer, differentiation gives . Normalizing the positive weight produces an equivalent martingale measure with integrable gains. This is a constructive one-period proof of the fundamental theorem of asset pricing even on an infinite probability space.
For deterministic initial asset values and a finite-dimensional terminal random vector , exactly one possibility holds: a portfolio has nonpositive initial cost and nonnegative payoff with strict gain at at least one date, or there is a strictly positive integrable state-price density pricing as displayed. Apply the strictly positive barycentre cone lemma. Outside the closed support cone, strict separation gives a negative-cost portfolio. On its relative boundary, a supporting functional gives a zero-cost portfolio with positive payoff on a set of positive probability. With a traded positive bank account, normalize its discounted density to obtain an equivalent martingale measure.
A complete market is a financial market in which every contingent claim in the chosen class can be replicated by an admissible self-financing portfolio. In an arbitrage-free finite market, completeness is equivalent to uniqueness of the equivalent martingale measure.
In an arbitrage-free one-period market with finitely many assets and an equivalent martingale measure, market completeness is equivalent to uniqueness of the dominated martingale measure. Completeness prices every indicator function, forcing two measures to agree on every event. Conversely, if the attainable payoff span has dimension but is not the whole payoff space, choose disjoint positive-probability events. Their moment vectors against a basis of attainable payoffs are linearly dependent. A nonzero bounded linear combination of their indicators consequently has zero pricing moments. Multiplying an existing equivalent density by , for sufficiently small positive and negative , constructs distinct equivalent martingale measures. This proves the converse without assuming that the original space was finite. On a general probability space, completeness here means replication of all bounded claims, or equivalently all square-integrable claims when asset payoffs are square-integrable.
In a one-period complete market with a strictly positive numéraire, at most one positive state-price density prices every traded asset. Suppose do so. For each event , replicate the contingent claim . Linearity of the pricing equations givesBoth weighted densities are integrable because they price the numéraire. An integrable random variable whose integral over every event is zero vanishes almost surely: take the events where it is positive and negative. Therefore , and strict positivity of the numéraire gives . This argument avoids assuming that the unweighted densities themselves are integrable.
Two assets with linearly independent payoff vectors across two positive-probability states span all terminal payoffs. The state-price equations have a unique solution. A positive solution gives the state-price density after division by physical state probabilities. Arrow state prices sum to the riskless discount factor, while normalized Arrow state prices are risk-neutral probabilities; these three quantities must not be confused.
In a one-period complete market with deterministic initial holdings, two integrable positive pricing variables assigning the same prices to every traded asset are equal almost surely. Replicate indicator functions to obtain equality of their integrals on every event, then apply this to the event where one density exceeds the other.
With assets and a trivial initial sigma-field, market completeness forces at most positive-probability successors per current atom. Indicators of disjoint successor events are independent payoffs, whereas terminal holdings on a parent atom span at most asset-price functions. Iterating yields at most atoms at time .
Let be the state-by-asset matrix of discounted gains. There exists with exactly whenfor every satisfying . This is the finite-dimensional cone-separation, or Farkas-duality, form of superhedging.
A European call option gives its holder the right, without an obligation, to buy one unit of an underlying financial asset at the strike price on the expiry date . European describes exercise timing, not geography: exercise is allowed only at . Here the underlying is one stock share, is its price at expiry, and the financial payoff is expressed as a cash amount. Physical exercise delivers a share against payment of ; immediate resale gives the same net amount under the assumed frictionless market.
The holder exercises only when buying at the strike price is advantageous. Writing for the positive part, the terminal financial payoff isThe European call option is a reusable building block for claim replication: its financial payoff is zero below the strike price and rises by one unit for each unit of stock price above it. The corner at lets combinations of European call options construct other payoff shapes, as in static replication on a finite terminal support.
For strike price , the following are deterministic calculations conditional on each displayed terminal stock price. They assign no probabilities to the three scenarios. The European put option has the opposite exercise right and the financial payoff .
| Terminal stock price | European call option | European put option | Difference |
|---|---|---|---|
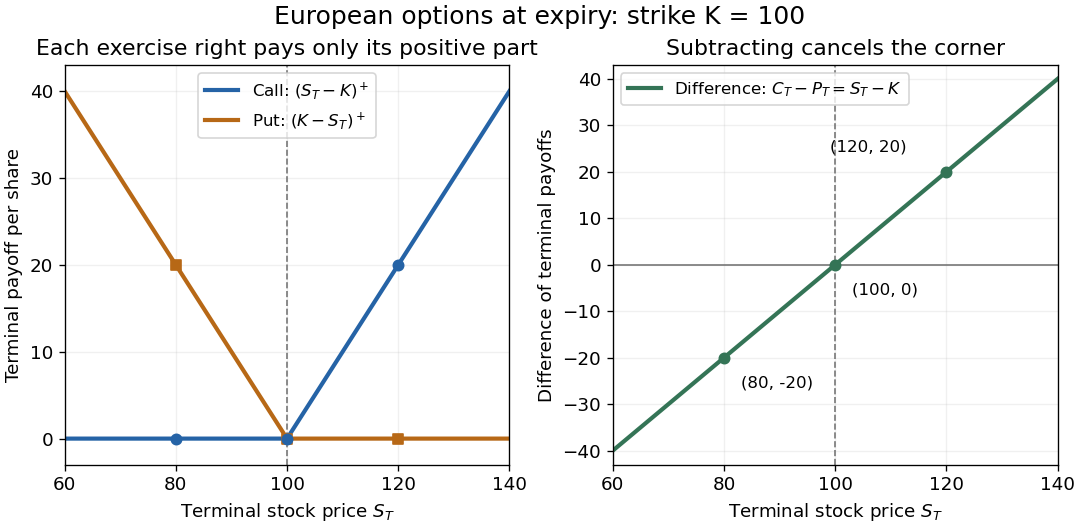
A financial payoff excludes the initial contract price. If the illustrative European call option costs , its financial payoff at is , and subtracting its initial cost gives . If that cost is instead borrowed for one year at the constant continuously compounded interest rate , the terminal net amount is . At or , the corresponding net amount is . Keeping all cash amounts at the same date avoids confusing a financial payoff with a financed gain.
Robert Shiller's Options Markets lecture, Yale ECON 252 (2011) introduces these exercise rights and payoff shapes.
A down-and-out European call pays the usual European call option payoff only if a lower barrier has not been hit before maturity. In the zero-interest, zero-dividend Black-Scholes model, for , its value is . This follows from reflection of the drifted logarithmic price killed at the barrier.
For a down-and-out European call with barrier equal to strike, zero interest and no dividends, hold one share and borrow the strike until barrier hitting or maturity. At continuous hitting the share price is exactly the debt, so liquidating leaves zero; on survival the portfolio pays . Hence the contract has value and delta one before knock-out. The pathwise replication works beyond constant-volatility Black-Scholes model, but can fail through downward jumps or execution gaps, and nonzero carry, transaction costs or discrete monitoring require changes.
For any fixed maturity, a European call option price is convex in its strike because is convex for every terminal stock value . Specifically, for , . Multiplication by the positive discount factor and expectation under the pricing measure preserve this inequality. This also explains why a violation of convexity creates a butterfly-spread arbitrage.
If the bank account is positive and nondecreasing and is a martingale under an equivalent martingale measure , then for the European call price is nondecreasing in . Put . For , and hence . Conditional convexity gives . Taking expectations and multiplying by proves the claim. The result is not generally true for negative strikes: with and , a negative-strike call costs , decreasing in maturity.
For and , integrate over to obtain the displayed identity. Tonelli theorem then expresses the moment of a nonnegative random variable as the same integral of expected call payoffs, even when the moment is infinite. This is a static representation across strikes rather than a dynamic replicating strategy in a restricted finite-asset market.
For and , minimize . Its minimum occurs at , giving the sharp constant. Taking expected values yields a uniform bound on from a finite moment of order .
For and , split the static call integral at a fixed positive strike. The first moment bounds the integrand near zero; polynomial call decay controls the integral at infinity for . The endpoint can fail, as shown by a Pareto distribution with survival exponent .
In a zero-interest one-period market with a continuous terminal stock law under a pricing measure, implies and . Thus a full differentiable call curve determines its pricing density. A finite collection of strikes generally does not. With a deterministic nonunit discount factor, divide the call curve by that factor before recovering the probability density.
Finitely many call prices impose finitely many payoff-moment constraints. They do not require a continuous terminal law or determine prices of arbitrary new claims. For example, , terminal values and , and upper-state probability give , matching the power curve. A payoff vanishing on these two states must cost zero, whereas integration against the power curve's strictly positive density can assign it a positive cost. A pricing density intended for arbitrary claims must be compatible with an equivalent law on the actual state space.
For , the zero-interest curve has positive second derivative . Its mass and first moment are both one, and . It prices an integrable payoff by when this law is equivalent to the physical terminal stock law, or on a canonical model with this pricing law. Finite-strike consistency alone is insufficient for that equivalence.
The midpoint butterfly buys half a call at each outer strike and sells one at the middle strike. Convexity of makes its terminal payoff nonnegative. A violation of the displayed price inequality makes its cost negative and creates arbitrage. The payoff is triangular between the outer strikes and zero elsewhere.
Buying the lower-strike call and selling the higher-strike call gives a strictly negative initial cost and terminal payoff . Hence an arbitrage-free call-price curve is decreasing in strike. The positive initial receipt may be consumed immediately or invested in cash.
A positive one-period martingale deflator applied to gives . If both strict payoff regions and have positive probability, then and , proving the strict lower bound. No normalization of the positive pricing variable is needed.
The Mellin transform of call prices can be inverted along a vertical contour with real part : . A finite exponential moment at and the quadratic denominator give absolute convergence.
For a martingale with increments in , European call option prices satisfy . At positive-probability states, the variance and the upward/downward conditional transitions are determined by this identity; transitions at zero-probability states cannot be recovered.
For an integer-valued underlying with European call option prices , the second strike difference equals . It is the discrete counterpart of recovering a payoff probability distribution from strike derivatives.
At a fixed maturity, no arbitrage makes a European call price nonincreasing in its strike because the lower-strike payoff dominates the higher-strike payoff state by state.
When terminal stock price takes finitely many ordered values, every payoff function of that price can be represented on the support by cash plus a linear combination of adjacent-strike call spreads.
The pathwise identity turns a squared-increment claim into a terminal-square claim and predictable stock gains. On integer terminal support , , so a static call strip plus a dynamic stock hedge replicates the claim.
Put-call parity fixes the price difference between a European call option and a European put option on the same underlying stock, with the same strike price and expiry . Assume no dividends or other payments from the stock before or at expiry, a known constant continuously compounded interest rate , and a frictionless market. Borrowing and lending are available at that same interest rate; short selling of the stock, European call option, European put option, and zero-coupon bond is permitted. Settlement is certain, and the buy-and-hold portfolios below may be held until without interim funding restrictions or forced liquidation. These assumptions exclude transaction costs, taxes, borrowing fees, and execution or settlement risks from the arbitrage argument.
At expiry, the two positive parts cancel their corners:Thus a European call option and a short European put option together have the same terminal financial payoff as one stock share with a debt of . A particularly readable claim replication uses two portfolios with nonnegative terminal amounts: portfolio A holds one European call option and a risk-free zero-coupon bond paying at ; portfolio B holds one European put option and one stock share. The zero-coupon bond costs today, since the discount factor is . There are no intermediate cash flows. For every terminal stock price,For the strike price , even the following very different outcomes leave the two portfolios equal:
| Terminal stock price | A: European call option + zero-coupon bond | B: European put option + stock |
|---|---|---|
The law of one price forces in this setting: otherwise buy the cheaper portfolio and sell the more expensive portfolio using short selling. Their terminal obligations cancel in every scenario, while the initial price difference can grow in the bank account. Hence absence of arbitrage givesWith a constant per-period interest rate over discrete periods, the same reasoning gives . This is a different compounding convention; is not the continuously compounded interest rate .
For an illustrative stock price , strike price , expiry one year away, interest rate per year, and given European call option price , put-call parity requiresBoth portfolios therefore cost approximately . The inputs specify no stock price dynamics: is supplied for illustration, not calculated from the Black-Scholes model. Put-call parity determines the European put option price conditional on that European call option price; it does not determine both prices by itself. At zero interest rate, the same and give the exact result .
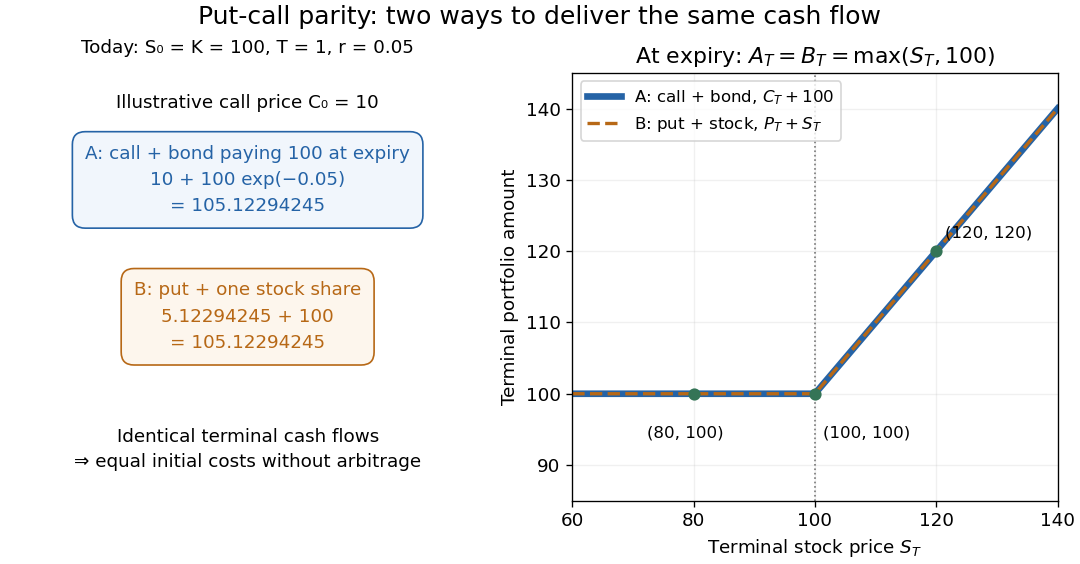
Two portfolios with identical terminal cash flows and equal initial costs under put-call parity
. Details. To compute both directions of arbitrage, keep all the preceding inputs except the quoted European put option price. If it is , portfolio B costs while portfolio A costs . Buy A, sell B, and place the initial surplus in the bank account. At expiry, A and the obligations from selling B cancel exactly, leaving in every scenario. If the European put option instead costs , buy B for and sell A for ; the initial surplus is approximately , growing to . Both constructions start with zero external capital. They are model calculations under the stated frictionless market assumptions.
The beauty of put-call parity is that uncertain individual financial payoffs produce an exact relation between today's prices. No forecast of the terminal stock price and no probability distribution are needed. It provides a consistency check and lets claim replication exchange one contract for a combination of others. Dividends introduce extra cash flows, and American put options can be exercised early, so the displayed European equality cannot simply be transferred to those contracts. K. Foster's [ref]
https://kfoster.ccny.cuny.edu/classes/spring2010/eco275/lecturenotes5.html. CCNY lecture notes on option values (2010), Put-Call Parity section
explain the matching portfolios; Jun Pan's [ref]https://www.mit.edu/~junpan/Jun_Pan_Teaching_Notes.pdf. MIT Financial Markets teaching notes, Arbitrage Pricing and Dynamic Replication section (PDF p. 130)
discuss put-call parity and its dividend adjustment.An original modern research source is Hans R. Stoll's [ref]
https://doi.org/10.1111/j.1540-6261.1969.tb01694.x. The Relationship Between Put and Call Option Prices
, The Journal of Finance 24(5), 801-824 (December 1969). Stoll studied the relation between contract prices and tested it against market data; this was a relation between prices rather than a formula fixing each price individually. Robert C. Merton's [ref]https://doi.org/10.1111/j.1540-6261.1973.tb01357.x. 1973 comment
, 28(1), 183-184, highlighted the importance of excluding premature exercise for an exact arbitrage equality. This distinction explains why the exercise assumption belongs in the statement of put-call parity.The difference of the terminal power-call and power-put payoffs is . Risk-neutral pricing and the geometric Brownian motion moment formula therefore give the displayed parity, with . At this reduces to dividend-adjusted put-call parity.
For the normalized Black-Scholes call function, completing the square gives , with and . The identities and implyFor a stock with risk-neutral drift , maturity difference , and positive strike , put-call parity then givesThe positive sign of in the reciprocal argument is forced by taking the reciprocal of . The identity includes by continuity and requires .
Conditioning on the first binomial move expresses a call with periods as a positive weighted sum of two -period calls with rescaled strikes.
A contingent claim is a future payoff whose value depends on uncertain market outcomes. A replicable claim has the unique no-arbitrage price of its replicating portfolio.
A financial option grants a right, without a corresponding obligation to exercise, to transact at specified terms. A call option is a right to buy and a put option is a right to sell. The contract specifies its permitted exercise times and strike price; the value of that right differs from the exercise payoff at any particular time.
A financial option granting the right to buy its underlying financial asset at a specified strike price . Its exercise payoff on one stock share is the positive part . A European call option permits exercise at expiry, while an American call option also permits earlier exercise. A forward-start call option determines the strike at a future fixing date.
The monetary amount delivered by a contingent claim at its payment time, represented by a random variable measurable with respect to the information then available. For a European call option it is , and for a European put option it is . A payoff is the delivered amount, whereas the claim is the contract and its current price is the cost of acquiring or replicating that contract.
The financial payoff obtained by exercising a financial option at a permitted stopping time . An American option compares this immediate payoff with the value of keeping the exercise right, whereas a European option restricts exercise to expiry.
A contingent claim whose payoff depends on the underlying price history, rather than only its terminal price. Asian options use averages, barrier options use whether a threshold has been crossed, and lookback options use running extrema. In the Black-Scholes model, the Brownian Martingale representation theorem still gives a replicating strategy; its portfolio wealth need not be a function of the current stock price alone. Adding a running integral or extremum can give a finite-dimensional state for pricing.
A path-dependent contingent claim whose payoff depends on the running minimum or maximum of the underlying stock. Floating-strike calls and puts pay and , respectively. Fixed-strike versions use positive parts of the difference between a running extremum and a specified strike. A sufficient pricing state contains the current price and the relevant running extremum.
For running maximum , a smooth price has an Itô formula term . The maximum increases only when . A self-financing portfolio in stock and bank account cannot supply an extra singular finite-variation term there, so the smooth price must satisfy the displayed boundary condition. Inside , it obeys the Black-Scholes equation in the price variable. The condition need only hold before maturity, where terminal corners may destroy differentiability.
A put option gives its holder the right to sell an underlying asset at a specified strike price. A European put option may be exercised only at maturity, whereas an American put option permits earlier exercise.
A power put has financial payoff below the strike price and zero at or above it, where is a positive integer. For this is the ordinary put option. For every the payoff is decreasing and is a convex function of the stock price. A European option permits exercise only at expiry; a perpetual power put option permits exercise at any finite time without a fixed expiry.
For a dividend-free Black-Scholes model with , , and positive integer , the optimal stopping value of the power put option isIn the continuation region the stationary Black-Scholes equation has powers and . Boundedness at infinity removes . Value matching gives the coefficient , maximized at the displayed ; equivalently this is the smooth fit boundary.
For a verification beyond constant-trigger policies, let . The maximum property of gives . For the infinitesimal generator , above . Below , set ; thenThe candidate is continuously differentiable across , so the generalized Itô formula has no derivative-jump local time of a semimartingale term. The discounted candidate is a nonnegative supermartingale, bounding every stopping reward by optional stopping. First hitting of attains the bound; the remainder at infinite time vanishes since and . For this recovers the perpetual put option. At the value is for , approached but not attained at a finite exercise time. At the perpetual value is infinite, because exercise at deterministic times tending to infinity has unbounded discounted expected value.
In the dividend-free Black-Scholes model, let , , , andThen the displayed finite sum prices the European option with power put option payoff. Here is the standard normal distribution function. Indeed, conditionally has a normal distribution with mean and variance . Expand by the binomial theorem on and apply the lower truncated lognormal moment to each term. Equivalently,This expectation representation proves monotonicity and convexity in . It also gives and as by the dominated convergence theorem. For positive the lognormal distribution smoothing makes the price smooth and strictly positive.
A European put option gives its holder the right, without an obligation, to sell one unit of an underlying financial asset at the strike price only on the expiry date . For one stock share, its terminal financial payoff is the positive partFor strike price , terminal stock prices , , and give financial payoffs , , and , respectively. At , selling for rather than the market price supplies the difference ; at , the holder can let the right expire. Equality at gives zero net exercise value. The European call option example plots both financial payoffs on the same axes.
Combining a European put option with the underlying stock share produces the terminal amount . Its floor at the strike price is why a European put option can describe protection against a fall in terminal stock value. The protection has an initial cost and lasts to the specified expiry; the terminal floor alone says nothing about the financial return. Put-call parity replicates this same amount with a European call option and a zero-coupon bond.
Using the put-call parity example's price , the cost financed for one year at interest rate grows to . The terminal net amount is therefore approximately when , and when or . These computations use the unrounded price and distinguish the financial payoff from the financed gain. Unlike an American put option, a European put option supplies no right to exercise before .
An American put has exercise payoff . In a finite binomial market, backward option pricing compares that payoff with the discounted risk-neutral continuation value at every node.
A put with a prescribed exercise rule: exercise at the first touch of , or at expiry if no touch occurs. Its value is bounded above by the American put option, which optimizes over exercise times. With zero interest rate, its value equals the down-and-out put value plus times a cash-at-expiry one-touch option value. At positive interest rate the rebate is paid at touch, so replacing it by an expiry payment would generally be incorrect.
For risk-neutral stock dynamics , with and , let solve . A fixed downward trigger gives continuation value for . Optimizing over the trigger, or imposing smooth fit, gives the displayed boundary. The optimal value equals below and the continuation expression above. A verification argument uses its payoff majorization and nonpositive discounted generator. At and , the perpetual value is for positive spot, approached by triggers tending to zero rather than attained at a positive finite trigger.
Here . Implicit differentiation of the negative-root equation gives . Differentiating gives the displayed negative derivative. A higher proportional dividend yield lowers risk-neutral stock growth and makes waiting for lower stock prices more attractive to the put holder.
A barrier option activates or expires according to whether the underlying price reaches a prescribed level during its lifetime. Its state must include whether the barrier has already been reached; the current price alone generally does not determine its remaining payoff.
A digital put option extinguished if the stock reaches an upper barrier . Under the dividend-free Black-Scholes model, conditional on not having hit the barrier before the current time, let , , , , andThen its price isThe Black-Scholes reflection symmetry proves the pricing equation, and the two terms cancel at . At expiry the reflected argument is above , so its payoff is zero, while is equivalent to inside the alive region. Thus the correct free strike is capped at the barrier. For , the value is the discounted upper-barrier survival probability, independent of , as for a barrier digital put. For its terminal data have a corner discontinuity at the absorbing barrier. Set the price to zero after a hit; the reflected expression on the other side is not a valid contract value.
A contract paying a fixed amount at expiry if specified barriers have not been touched. Its complement, with the same expiry payment convention, is a one-touch option. Paying upon first touch rather than at expiry changes the discounting and gives a different contract.
An up-and-in claim activates when the stock reaches an upper barrier during its lifetime. After activation its terminal payoff is the prescribed function ; without activation it pays zero. Under continuous stock paths the barrier event is described by the displayed running maximum.
For an up-and-in claim in the dividend-free Black-Scholes model, set , and assume finite absolute payoff expectations. Its initial price equals the risk-neutral pricing value of the displayed European option. To prove this, express the log-price as and apply the joint endpoint and maximum law for drifted Brownian motion. Above the logarithmic barrier , use the unrestricted endpoint density. Below it, the density of paths which hit the barrier is . Substitution gives the scaled payoff, the threshold , and the factor . This is an initial-price identity, not a pathwise equality of terminal payoffs.
An up-and-out power claim pays a power of the terminal stock price provided an upper barrier has never been reached. In the Black-Scholes model, set and , where , and . The risk-neutral pricing value isHere is the standard normal distribution function. Weighting the Brownian motion endpoint by changes the logarithmic drift to ; the finite-horizon maximum of Brownian motion with drift then supplies the survival factor.
A down-and-out claim expires worthless if the stock reaches a lower barrier before maturity. A matching down-and-in claim plus a down-and-out claim pays the ordinary terminal claim on every path; this is in-out parity.
A digital call option that pays its terminal indicator only if a lower barrier was avoided. When its strike equals the lower barrier, survival already implies the terminal indicator is one. It is then a no-touch option, with alive price in the dividend-free Black-Scholes model.
A European put option that becomes worthless when its continuously monitored lower barrier is touched. The alive state has and no earlier hit. A terminal building block for the Black-Scholes reflection symmetry is for . Its terminal payoff is . The alive price is and is set to zero after any hit.
A down-and-in claim with lower barrier pays a specified terminal payoff only if the stock reaches before maturity. Before activation its value solves a killed-domain pricing problem; at activation its value equals the ordinary terminal-payoff claim value.
For strike , write for the ordinary European call option value. Before activation the down-and-in claim is , where . Consequently its left-limit option delta at the barrier is , whereas after activation it is . Their difference is strictly positive for : differentiating the killed normal transition density at its boundary gives the integral of a strictly positive function against the positive call payoff. The value is continuous, so changing the bank holding finances the stock rebalance.
For initial spot in the Black-Scholes model, put and . A down-and-in claim with terminal payoff has the same initial price as the terminal claim . Reflection of the log-price endpoint above the lower barrier changes its normal probability density to , where . Substitution gives the payoff identity. This is price equality, not pathwise equality of payments.
A barrier contract paying a specified fixed amount if the underlying touches a specified barrier before expiry. Payment at touch and payment at expiry are different conventions. For payment at touch, valuation uses the truncated discounted Brownian first passage after converting a geometric stock barrier to a log-price level; discounting solely at expiry would price a different contract.
An agreement to exchange an underlying at a fixed delivery price on a specified maturity, without the futures convention of repeated settlement. Its fair delivery quote is . It may differ from a futures contract quote when rates are stochastic.
A prepaid forward pays for delivery of an asset at a future time entirely in advance. In the Black-Scholes model with deterministic continuous dividend yield , one share delivered at costs the displayed amount at . Reinvesting the dividends on shares replicates one terminal share. An ordinary forward contract instead has no initial payment and a delivery payment fixed in advance; at constant interest rate its fair delivery price is .
A standardized maturity-and-quantity agreement whose quote changes generate margin payments as gains and losses are marked to market. A newly settled contract has zero value, while its quoted delivery price is generally nonzero. In the continuous-settlement idealization, futures pricing uses a pricing-measure martingale quote.
With continuous cash settlement and a money-market risk-neutral measure, discounted futures gains have zero drift; under the necessary true-martingale integrability, the futures quote is a martingale ending at the terminal spot price. The forward contract discount-weighted expectation is a different valuation expression.
A futures contract delivery quote below current spot for the maturity considered, or a falling futures curve across maturities. This spot comparison should be distinguished from comparisons with the future physical-measure expected spot.
A futures contract delivery quote above the current spot price for the maturity considered; a rising quoted curve across maturities is also described as contango. This compares delivery prices rather than the current zero value of a newly settled contract.
The payout is a concave stock payoff. Its conditional expected value has a discount-like dependence on future variance. The square-root stock supermartingale explains the negative variance drift.
For a square-root stock claim priced by , the constant-volatility geometric Brownian motion price is . If , and , its unique nonnegative inverse volatility is the displayed . For bounded predictable volatility in , bounds give , without independence from the Brownian motion. At zero stock price the claim price is also zero and no volatility is identified by this equation; a separate convention is needed.
For bounded predictable on , the stochastic exponential is a positive martingale by the Novikov condition. Under , the Bayes formula for conditional expectation givesIndeed, the square-root stock ratio is . This exact identity gives the bounds on square-root stock implied volatility by bounding integrated variance pathwise. The Girsanov theorem gives . The measure is an auxiliary pricing identity for this payoff, not a claim that it is an equivalent martingale measure for the original stock.
If and , the stochastic Fubini theorem and Itô formula give and . The final term comes from the product cross-variation. Continuity extends the drift equality to the specified continuous versions.
In the joint filtration of Brownian history and an independent volatility history, conditioning on the entire volatility path and then using the tower property gives . Removing the outer conditional expectation requires the integrated variance to be known at time . Independence alone does not give this measurability; a volatility parameter disclosed later supplies a counterexample.
A contingent claim is replicated when an admissible self-financing portfolio has exactly its terminal payoff. In the absence of arbitrage, two replicating strategies for the same payoff have the same initial cost.
A one-period quadratic hedge minimizes over deterministic holdings, where is the riskless gross return, , and the covariance matrix is invertible. For a square-integrable claim, the unique solution is and . Centering separates the squared bias from the quadratic error. Completing the square gives the excess error as after the bias is minimized. Unlike claim replication, the residual need not vanish.
For a discounted contingent claim and gain vector , fix initial capital and minimize . Differentiation gives the least-squares normal equations , where is assumed invertible. This gives the displayed hedge. Optimizing capital as well instead centers the gains and uses their covariance matrix: and . Fixing the initial capital is therefore a different quadratic problem.
Let and be an invertible covariance matrix of discounted gains. The displayed signed martingale measure leaves unchanged the mean-zero random variables orthogonal to the martingale part : if and , then . Conversely, preservation of all these orthogonal directions forces the density to lie in the span of , and its pricing constraints give the displayed formula. If it is an equivalent martingale measure; if it is a dominated martingale measure. Positivity is an extra condition, not a consequence of absence of arbitrage alone. In one period this density also minimizes among square-integrable signed pricing densities, because every other such density differs by a vector orthogonal to . The initial capital in the unrestricted one-period quadratic hedge of a discounted payoff is .
Let a discounted gain take values with physical probabilities . Then and , so the minimal martingale measure in a one-period market has signed density . Nevertheless is a strictly positive pricing probability with zero mean gain. Thus absence of arbitrage does not ensure positivity of the minimal density. The minimum-norm identity holds for signed pricing densities; interpretation as a dominated martingale measure requires nonnegativity.
A finite signed measure with total mass one under which discounted asset gains have zero integrals. Its density can be negative, so it need not be a probability measure or give arbitrage-free prices to every nonnegative contingent claim. A square-integrable signed density is useful in one-period least-squares hedging, even when it is not an equivalent martingale measure.
If has a multivariate normal distribution with mean and invertible covariance , and has bounded gradient, Gaussian integration by parts gives . Consequently the risky holdings of its one-period quadratic hedge equal the expected payoff gradient. The initial cost is . Bounded gradient ensures linear growth and square integrability, even if the payoff is not bounded.
The initial cost of the one-period quadratic hedge is . This pricing weight satisfies and . Among square-integrable weights satisfying these equations it has the smallest squared norm:For another admissible weight , its difference from is orthogonal to and all coordinates of , hence to . The Pythagorean theorem in an inner-product space gives . This weight can be signed; positivity, and hence interpretation as a state-price density, requires additional assumptions.
In a one-period complete market, an invertible payoff Gram matrix identifies the unique holdings replicating each claim. The pricing weight is and the random portfolio kernel is . Positive definiteness gives uniqueness of holdings; positivity of requires an additional no-arbitrage condition.
With a constant cash account, holding shares during interval and selling one share at each endpoint replicates . Each sale is retained in cash; the initial cost is . The proof is a pathwise telescoping identity.
An admissible self-financing portfolio superhedges a contingent claim when its terminal wealth is at least the claim payoff almost surely. The least permitted initial cost is the superhedging price. Exact claim replication requires equality.
The infimum of initial costs of admissible superhedging portfolios. Positive pricing kernels supply lower bounds: if and , then whenever these expectations exist.
A replicating strategy is a self-financing portfolio whose terminal wealth equals the prescribed payoff of a contingent claim. Admissibility specifies the permitted wealth bounds and integrability of its holdings.
A European contingent claim pays a specified function of market variables at one fixed maturity. Under an equivalent martingale measure, an attainable claim is priced by the discounted conditional expectation of its payoff.
An exchange option permits delivery of one asset in exchange for another at maturity, producing the positive-part payoff . In a complete finite market its price is the discounted expected value under the unique risk-neutral measure. For a two-period joint binomial model, evaluating this payoff at all four terminal paths and weighting by their risk-neutral path probabilities gives its price directly.
This compound European contingent claim gives the right to buy a later-expiring put option at time for . Its payoff is the positive part of the put value minus this exercise cost. Under the Black-Scholes model the put value decreases strictly with the stock spot, so a nondegenerate positive exercise cost gives a unique upper spot threshold for exercise. With zero exercise cost, the compound claim has exactly the underlying put's price by the tower property.
A financial option whose strike or other exercise terms are fixed at a specified future date, with expiry later still. A forward-start call option pays the positive part of terminal stock price minus that future strike. Specifying the rule for fixing the strike is part of defining the contingent claim.
Let be the Black-Scholes formula value divided by stock price for an at-the-money call of duration . On a discrete set of possible entry dates, homogeneous function and the discounted stock martingale reduce the Snell envelope to , with zero terminal value. Thus the displayed maximum is exact. When and volatility is positive, increases with maturity, so immediate entry is optimal and the initial value equals the ordinary at-the-money European call option. The maximum recursion remains useful if a different parameter regime loses that monotonicity.
A forward start option whose call option strike is fixed at time as , with expiry and . Its terminal financial payoff depends on the intermediate stock price as well as the final price. Two paths ending at the same price can therefore have different payoffs, so a recombining stock tree must retain enough history to value the contract.
In a homogeneous dividend-free Black-Scholes model, let be the European call option price with current stock one and strike over the remaining duration. Homogeneity gives value when the strike is fixed. The discounted stock is a martingale, so risk-neutral pricing before that date givesThe same argument holds in a homogeneous binomial options pricing model with the corresponding remaining-step call value. It depends on the normalized future pricing rule being independent of the stock level at the fixing date.
A European option paying the positive part of the logarithm of terminal stock price divided by a positive strike . In the dividend-free Black-Scholes model, that logarithm has a normal distribution under the risk-neutral measure. The Gaussian positive-part expectation gives , where and . This differs from the untruncated logarithmic payoff and from the payoff .
A maturity- claim is attainable if a predictable self-financing strategy with fixed initial capital has terminal wealth equal to the claim payoff almost surely. In discrete time its wealth is . The strategy replicates the claim; attainability is a statement about exact pathwise replication, not only equality of expectations.
An option whose payoff depends on an average of the underlying stock prices over time. The displayed arithmetic-average call differs from a geometric-average call, which uses the geometric mean. A convex payoff and a nondecreasing positive numéraire give an upper bound by the average costs of same-strike European call options at the averaging dates.
An Asian option whose averaging uses the geometric mean. In the constant-coefficient Black-Scholes model, the logarithm of the continuous geometric average is Gaussian with mean and variance , because . Its forward mean is . The discounted lognormal call formula gives its price. It is strictly cheaper than the terminal European call when and , since both its forward mean and log-variance are no larger, with strictly smaller variance. No unconditional comparison holds for arbitrary negative interest rates: for , sufficiently small positive strikes reverse the inequality.
For and in the Black-Scholes model, the conditional law of under the risk-neutral measure has a normal distribution with mean and variance . The future Brownian integral equals , so the Itô isometry gives the variance. For strike and , the call price is , where and . This follows by completing the square in the truncated normal exponential moment; the known past integral must be included in the mean.
Articles were limited to the first 100 out of 114 total.
Articles by others on the same topic



The Fundamental Theorem of Asset Pricing is a key concept in financial mathematics and economics that establishes a connection between the pricing of financial assets and the existence of arbitrage opportunities in a market. It essentially provides the theoretical foundation for understanding how assets should be priced in a no-arbitrage market. The theorem can be summarized in a few main points: 1. **No Arbitrage Condition**: The first part of the theorem states that if there are no arbitrage opportunities in a market (i.e.