
Boundary value problem Created 2026-09-24 Updated 2026-09-24
A boundary value problem asks for a differential-equation solution satisfying conditions at more than one point or boundary component.
Lie point symmetry of an ordinary differential equation Created 2026-09-24 Updated 2026-10-03
A Lie point symmetry is a local one-parameter transformation of the independent and dependent variables that maps solution graphs of a differential equation to solution graphs.
Singular perturbation Created 2026-09-24 Updated 2026-10-14
A singular perturbation is a parameter-dependent problem whose limiting problem changes qualitatively as the parameter tends to zero. In an ordinary differential equation, a small coefficient of the highest derivative can reduce the order of the limiting differential equation, preventing it from satisfying all the original boundary conditions. Different length or time scales often require different asymptotic expansions.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §1.1.2, p. 2: regular and singular perturbations
Consider the boundary value problemThis second-order differential equation is exactly solvable. Setting gives the first-order linear differential equation , so . One integration and the two boundary conditions giveBoth boundary conditions hold for every positive . For numerical evaluation, write the same ratio as , where evaluates the exponential function minus one without catastrophic cancellation near . Keep the denominator for finite : at it is approximately , rather than exactly one.
Setting gives . The outer solution selected by the right boundary condition is therefore , which fails the left boundary condition. The exact exponential function shows how that mismatch is repaired: the solution rises from zero to almost one within a boundary layer of width , using Big O notation. For each fixed , , while always. This pointwise convergence fails to be uniform convergence to the outer solution on , since for every .
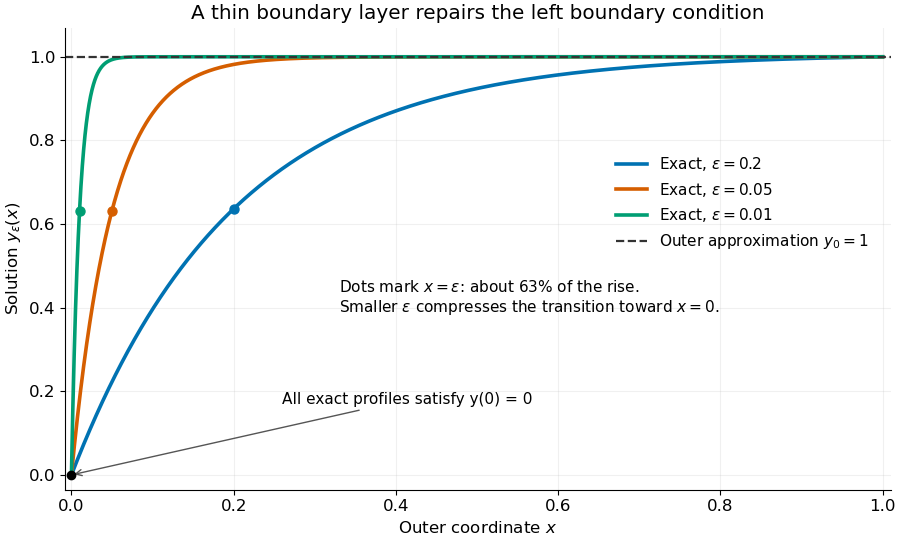
Exact solutions with a shrinking left boundary layer
. The exact normalized profiles at , , and satisfy both boundary conditions. The dashed outer solution misses the left boundary condition. Colored dots mark , where most of the initial rise has already occurred. Details.
The coefficient is small, but its product with the second derivative need not be small. Direct differentiation givesAt with fixed , these derivatives grow as and respectively as . Consequently and have exactly equal magnitudes and opposite signs. Even away from the boundary layer, their magnitudes remain equal in this example; both become exponentially small at each fixed positive . The outer expansion neglects an exponentially small transient there, rather than establishing that one derivative term is smaller than the other everywhere.
To predict the width without knowing the exact solution, suppose an order-one change occurs over distance . The derivative scales are and . The dominant balance gives . The resulting inner variable makes the boundary layer visible at a fixed scale. This is the useful feature of singular perturbation: an apparently disappearing term identifies the missing structure when one measures its derivatives on the appropriate scale.
Local existence for a scalar autonomous ordinary differential equation with continuous vector field Created 2026-09-24 Updated 2026-09-24
Linear differential equation Created 2026-09-24 Updated 2026-10-14
A scalar linear differential equation of order has the formHere the coefficients and the forcing term are prescribed functions of the independent variable . A classical solution of a differential equation is an -times differentiable function satisfying the identity at every point of its interval. The unknown function and its derivatives enter to the first power, without products between them or coefficients depending on . Equivalently, the differential operator is a linear map: for constant scalars ,The forcing term may be zero, giving a homogeneous linear differential equation, or nonzero, giving an inhomogeneous linear differential equation. Linearity of does not mean that every function graph of a solution of a differential equation is a straight line.
To use the usual order- initial value problem theory on an interval , assume that throughout and that all and are continuous functions there. Dividing by normalizes the highest derivative; specifying at then selects one solution of a differential equation throughout . A zero of needs separate analysis: one cannot divide through it and retain these conclusions. The first-order normalization appears in OpenStax's definition and standard form of linear equations; the corresponding system theorem is in MIT's existence and uniqueness notes for linear systems.
The coefficients need not be linear functions of . For example, is a linear differential equation on , although is quadratic. Its solution of a differential equation with initial condition is : its derivative is , so substitution gives , and . The zero of the highest coefficient at explains the domain restriction. In contrast, , and are nonlinear ordinary differential equations because of their dependence on the unknown function. Variable coefficients and nonlinear ordinary differential equations are different issues; see MIT's definitions and examples of first-order linear equations.
The practical benefit of linearity is that it separates the effect of the initial condition from the effect of the forcing term. Once one particular solution satisfies , every solution of a differential equation isHere is the kernel of a linear map, consisting of solutions of a differential equation to the associated homogeneous linear differential equation. Indeed, , and conversely . Thus the family for a fixed forcing term is an affine space obtained by translating . If is not identically zero, the zero function is absent, so this family is not a vector space under the usual operations on functions. This short argument explains why a general solution is a particular solution plus a homogeneous solution.
Finite-time blowup Created 2026-09-24 Updated 2026-10-14
A solution of a differential equation has finite-time blowup in norm when as approaches a finite endpoint of its maximal interval of existence. This is stronger than merely approaching an excluded boundary of an open state domain while staying bounded. The finite-dimensional continuation criterion distinguishes these obstructions; for a locally Lipschitz continuous ordinary differential equation on , a finite maximal endpoint inside necessarily entails finite-time blowup.
A simple example with a smooth right-hand side isThe derivative identity verifies the equation and the initial condition. Also for , giving local Lipschitz continuity and therefore uniqueness. Yet the positive blowup time is . Computed values show the accelerating growth:The right panel under the Picard-Lindelöf theorem deliberately clips its vertical axis at : the trajectory has already left the picture at , before reaching . A plot ceiling is a display limit, not a finite value at blowup.
The tangent function also quantifies the last part of the trajectory. With ,Thus the height is approximately the reciprocal of the remaining time. At remaining times , the heights are approximately . These follow from the sine and cosine limits at zero and explain the steep rise without relying on the appearance of a clipped function graph.
The distinction is useful when interpreting a solution of a differential equation: uniqueness certifies a trajectory while it exists, while growth estimates decide how far it can be followed. For , the Lipschitz constant on a bounded state interval grows with , and the right-hand side grows quadratically. There is no global Lipschitz constant or linear-growth bound of the kind used by the finite-dimensional continuation criterion. Smoothness at every finite state is entirely compatible with finite-time blowup.
Picard-Lindelöf theorem Created 2026-09-24 Updated 2026-10-14
Let be an open set and a continuous function. Suppose is locally Lipschitz in the state , with a Lipschitz constant uniform on a sufficiently small time-state neighborhood of each point. Then each determines a unique local solution of a differential equation to the displayed initial value problem, on an interval around . This is the local theorem in Ordinary Differential Equations and Dynamical Systems by Gerald Teschl.
For example, , , has the solution of a differential equation : its derivative is itself and its starting value is . The Lipschitz constant is , since . Thus uniqueness follows even before computing . Picard iteration below constructs this exponential function one polynomial at a time.
The Lipschitz condition has real content. For the continuous function involving a square root,each waiting time gives a different forward solution of a differential equation:The constant solution of a differential equation is another choice. At , delays give respectively. Before the join, both sides of the ordinary differential equation are zero; afterwards, . Both one-sided derivatives at are zero, so the join is valid. All these trajectories can also be extended by zero to . The failed Lipschitz condition is visible in the quotientFor this quotient is . Continuity still allows local existence by the Peano existence theorem; it cannot choose a waiting time. MIT's 18.034 Lecture 2, Example 2.3 develops the same waiting-time mechanism for a different ordinary differential equation, .
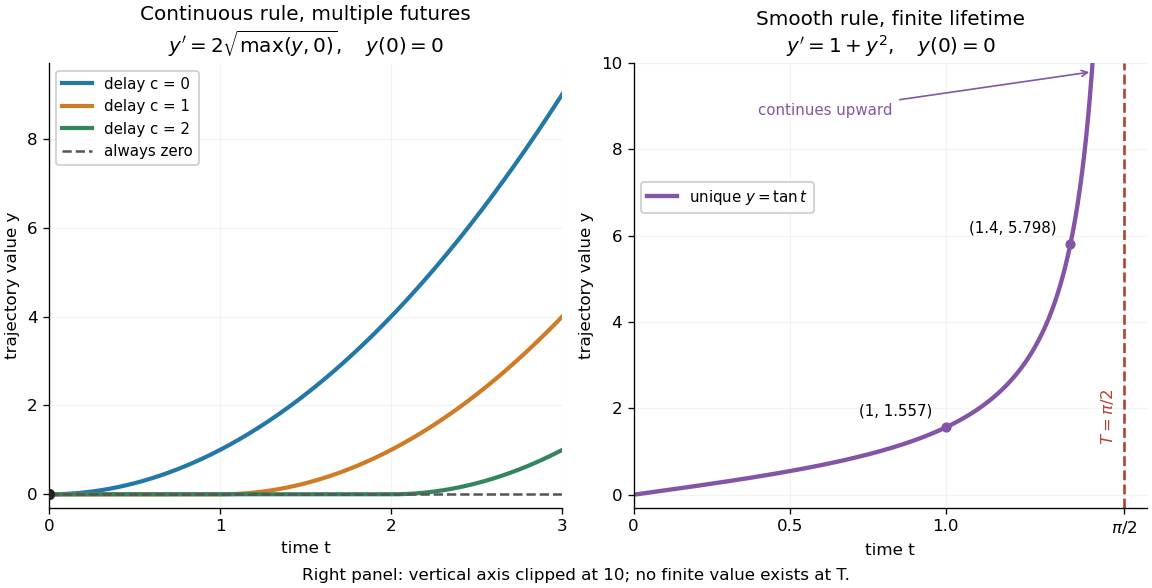
Failure of uniqueness and finite-time blowup are different obstructions
. Left: several delayed solutions of a differential equation of share . Right: the unique solution of a differential equation of , , has finite-time blowup at . The right vertical axis ends at ; the curve continues upward beyond the plot, and there is no finite endpoint value. Details.
The useful promise is that an initial condition and a sufficiently regular local rule select one trajectory. It justifies comparing models and following trajectories without an arbitrary choice at each instant. A locally Lipschitz continuous rule need not keep that trajectory bounded: meets the theorem's hypotheses everywhere but has finite-time blowup. Longer existence is governed by the finite-dimensional continuation criterion.
Hessenberg natural sum Created 2026-09-24 Updated 2026-10-14
The Hessenberg natural sum aligns equal exponents in two Cantor normal forms and adds their finite coefficients; unlike ordinal addition it is commutative.
It is the commutative natural addition operation in ordinal arithmetic.
Cantor normal form Created 2026-09-24 Updated 2026-10-03
Every nonzero ordinal has a unique finite expression with decreasing exponents and positive finite coefficients.
First uncountable ordinal Created 2026-09-24 Updated 2026-09-24
Ordinal interval Created 2026-09-24 Updated 2026-09-24
Derived-set iteration of a well-order Created 2026-09-24 Updated 2026-09-24
For a well-ordered set , let contain the points whose strict initial segments are nonempty and have no greatest element, and iterate this operation transfinitely, taking intersections at limit stages. Every nonempty derivative loses at least its least element. If no derivative became empty, choosing one point from each successive difference would inject the ordinal supplied by Hartogs theorem for into , a contradiction.
Ordinal exponentiation Created 2026-09-24 Updated 2026-09-24
Ordinal multiplication Created 2026-09-24 Updated 2026-09-24
Ordinal multiplication is defined recursively byfor nonzero limit ordinal . It is associative and left-distributive over ordinal addition, but generally neither commutative nor right-distributive.
Ordinal addition Created 2026-09-24 Updated 2026-09-24
Ordinal addition is ordered concatenation and is associative but generally not commutative.
Transfinite induction Created 2026-09-24 Updated 2026-09-24
Transfinite recursion Created 2026-09-24 Updated 2026-09-24
Limit ordinal Created 2026-09-24 Updated 2026-09-24
A nonzero ordinal is a limit ordinal when it is not a successor ordinal. Equivalently, it is the supremum of all smaller ordinals.
Order type Created 2026-09-24 Updated 2026-09-24
Countable ordinal Created 2026-09-24 Updated 2026-10-14
These are the ordinals strictly below the first uncountable ordinal.
There are unlisted articles, also show them or only show them.