An asymptotic expansion describes a function near a specified limit by successively smaller scales. Each fixed finite truncation has a remainder smaller than its last retained scale. The central question is how the approximation improves as the parameter approaches the limit; convergence of the entire infinite series at a fixed parameter is a separate question. For the inverse-power scale ,means that, for every fixed nonnegative integer ,The little o notation makes the accuracy requirement precise. With expansions to all orders, this is also equivalent to an remainder after the th term; the implied bound may depend on .[ref]
For a quick convergent example, the finite geometric series identity givesFor , both the asymptotic expansion as and the ordinary convergent geometric series describe this function. The exact remainder displays the required extra inverse power.
The more surprising example under a divergent factorial series can approximate a convergent integral has a convergent integral but a divergent series at every fixed positive :A few terms can estimate well, even though adding sufficiently many terms eventually destroys the approximation. Optimal truncation explains where to stop.
This makes asymptotic expansions useful when an exact expression is a complicated integral or differential equation solution, but a parameter is very large or very small. The leading term reveals the scale; corrections reveal which effects matter next. The asymptotic sequence must be specified: integer powers, fractional powers, logarithms, and exponential functions can encode different kinds of behavior. A good finite approximation includes a remainder estimate or an independently checked range of use.
For , put . Taking a logarithm gives , first implying . Substitution of gives at first correction order. Hence ; substituting back and using the derivative of bounds the remaining root error by .
The real roots of , with , can be counted by solving for the parameter: . Positive values occur only on and . Direct differentiation and the half-angle identities give the derivative in the title. It is negative except at isolated points, so is strictly decreasing on both intervals, with limits and zero. There are exactly two real roots for each positive parameter. As , dominant balance gives and . The exact root count supplements the local asymptotic expansions: a small-root expansion alone would omit the root escaping to infinity.
An approximation is uniform on a specified domain when its error bound holds throughout that domain as the small parameter tends to zero. In a matched asymptotic expansion, adding the inner and outer approximations and subtracting their common overlap produces a composite approximation. Checking only a fixed point away from a boundary layer does not establish uniformity.
When and , the change resolves a truncated Cauchy distribution. Its leading contribution is . It matches the nonresonant endpoint integral on one side and the full interior peak on the other. An interior peak at has width ; proximity to an endpoint must be measured against this width, not against alone.
An asymptotic power series uses powers as its asymptotic sequence. Near a finite point , the condition in the title applies along the specified domain for every fixed ; at infinity, inverse powers are convenient. It need not be a convergent power series. Its coefficients record the successive limiting responses, as the integral example below demonstrates.
The finite-order Taylor theorem supplies an asymptotic power series for a smooth function near a point, but smoothness does not imply that its Taylor series converges to the function. Define for and for . Every right-hand derivative is an exponential function times a polynomial in , tending to zero as . Consequently is a smooth function with every derivative zero at the origin. Its all-zero Taylor series misses to the right. Zero and also have the same all-zero asymptotic power series on that side, despite being different functions. An asymptotic expansion can determine all its own coefficients without determining the represented function uniquely.
For real , defineThe integrand is positive and at most , so and the improper integral converges. Substituting also gives in terms of the exponential integral; the original representation makes positivity and the large- behavior transparent.
Apply the exact finite geometric series identity inside the integral, without assuming that an infinite series can be integrated term by term:The Gamma integral gives . Therefore, with retained terms,This remainder formula proves the asymptotic expansion at every fixed order: as . Its sign also gives alternating bounds: an odd overestimates , and an even underestimates it.
At , an independent evaluation of the integral gives . Three retained terms giveFive retained terms give with error bounded by . The actual errors are about and , respectively. The error bound is conservative, but established without relying on the numerical integral evaluation.
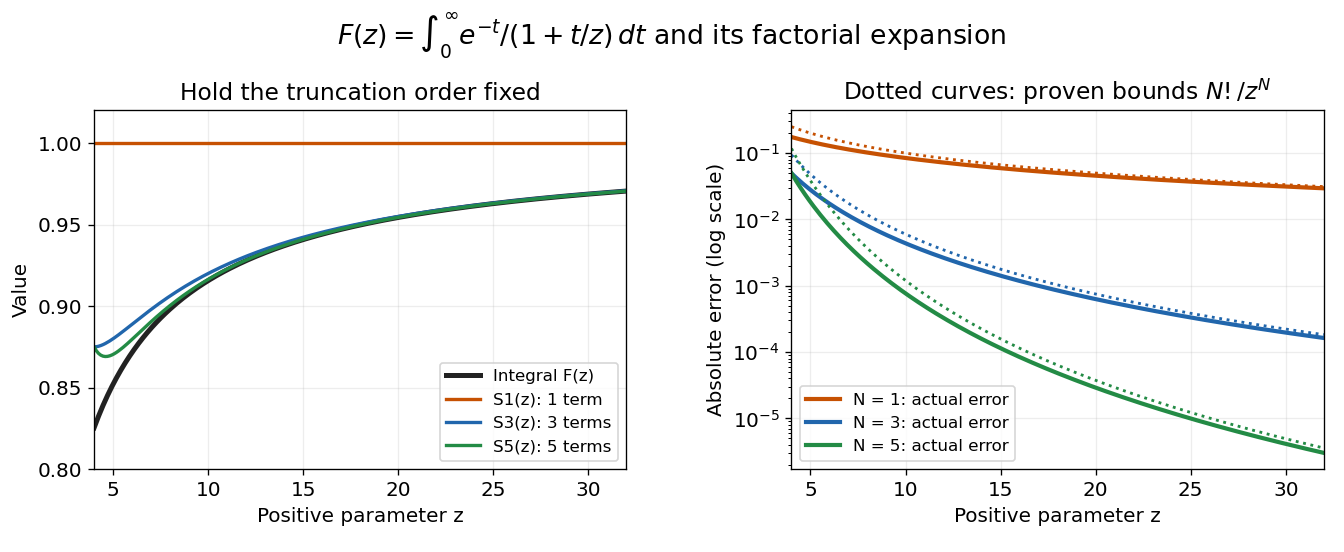
Nevertheless, the formal infinite series diverges at every fixed . The magnitudes satisfy , so they eventually increase without bound. In particular, the terms fail the necessary zero-term condition for a convergent series. The finite remainder identity remains valid after convergence has failed; this is precisely what makes the example useful.
Suppose a continuous function on has a known power-law tail . Put and . When extends continuously to , polynomial approximation on gives a global approximation using only elementary operations. Taylor series at zero and the tail asymptotic expansion can constrain endpoint coefficients. Agreement at the two endpoints alone does not guarantee accuracy in the intervening interval; uniform error control or intermediate calibration is needed.
Perturbation theory develops approximate solutions in a small parameter around a simpler reference problem. A power-series asymptotic expansion gives equations for successive correction coefficients; a matched asymptotic expansion handles cases where one expansion is not uniformly valid.
A perturbation is a small change in a model, operator, state or parameter. It can be organized as a family in a specified norm. If and is invertible, differentiating at zero gives . The implicit function theorem justifies this continued solution locally. Singular derivatives at a bifurcation instead require an unfolding or reduced equation; smallness of the change alone does not preserve a degenerate bifurcation.
For smooth on and positive integer , repeatedly integrating twice eliminates the sine endpoint terms and yields only even inverse powers of . The exact remainder after pairs is , which is by the Riemann-Lebesgue lemma. Without integer frequencies an sine endpoint term generally remains.
Rescale variables so that the terms responsible for the leading behaviour have comparable size. The resulting distinguished limit exposes a governing equation that may differ from the naive zero-parameter equation. Examples are dominant balance for algebraic roots and the derivative balance in a square-root boundary layer at a vanishing drift.
A regular perturbation admits an asymptotic expansion about the limiting problem without changing its relevant scale or losing solutions or conditions. A regular perturbation of a simple algebraic root follows from the implicit function theorem. A full problem can still be a singular perturbation even when some individual solution branches are regular.
For and , expand all three quantities in powers of . The order- problem has and , with . In particular, Taylor series boundary coefficients are generally nonzero even when the differential operator depends linearly on the parameter. If the homogeneous realization of is invertible and boundary data admit smooth lifts, the same inverse solves each successive inhomogeneous boundary value problem. Induction establishes unique coefficients at every order. This formal conclusion does not alone assert convergence of the full power series; convergence needs additional bounds on the inverse and the perturbation.
For fixed real , roots of tending to positive infinity approach tangent poles . Expanding givesThe expansion works for either sign of when , but is nonuniform at , where the roots lie at instead. The pole labeling need not equal the ordered root index at small .
For positive rates , the mean value theorem in the rate gives a bound by . Its maximum is . Combining this estimate with coefficient errors bounds a finite spectral sum uniformly on a half-line, including slow scales much longer than one. Positivity of both rates is essential: unstable exponentials need a different time-window or relative-error analysis.
For a formal inverse-power series , divide its coefficients by to form a Borel transform and integrate it against . Singularities on the integration ray require a specified contour prescription. Different lateral contours can produce exponentially small differences and the Stokes phenomenon.
Removing factorial growth from the coefficients of a formal inverse-power series produces its Borel transform. When continuation and exponential growth bounds allow it, reconstructs the series by Laplace transform. A singularity on the integration direction requires a lateral contour prescription. A simple pole contributes a residue when that prescription is changed, explaining how Stokes phenomenon arises from otherwise identical algebraic expansions.
If a Borel summation contour meets a simple pole, an upper or lower indentation fixes the exponentially small contribution. For the transform on the positive ray, the relevant pole is . A lower indentation gives the Cauchy principal value minus . Finite geometric expansion gives an exact remainder integral, which enables optimal truncation and error-function smoothing of a Stokes multiplier.
Optimal truncation chooses how many terms to retain for a useful finite approximation. In a divergent asymptotic expansion, increasing the truncation order eventually makes the terms larger rather than smaller. Stopping near a smallest term often gives the best direct approximation, but the actual remainder must be checked. A small last term alone is not a universal error bound.[ref]
2.11 Remainder Terms; Stokes Phenomenon. NIST Digital Library of Mathematical Functions, §2.11(i), discussion of finite-parameter accuracy and independently checking remainders; §2.11(iii), exponentially improved expansions
For a divergent factorial series can approximate a convergent integral, decreases while and increases while . Thus the useful cutoff is near , rather than at arbitrarily large order. At , are the two smallest terms. Retaining terms givesThe actual error is about . Retaining twenty terms instead gives , with error about : more work produces a worse answer.
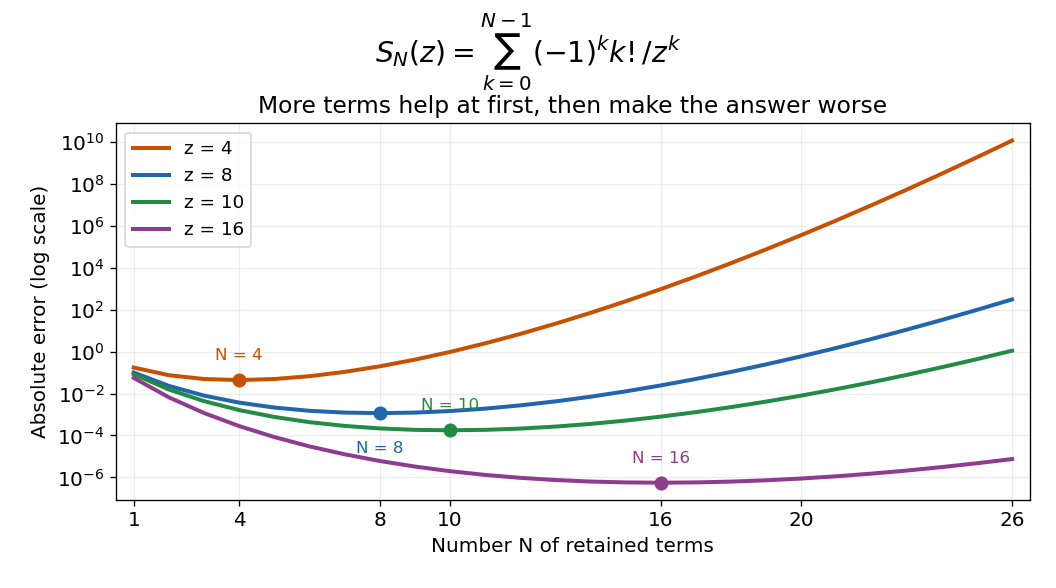
For this example the bound is explicit, so a requested tolerance can be tested before using a truncation. For a different integral, a nearby saddle point or simple pole can change the relevant remainder scale. This is why the smallest-term rule is a useful guide, rather than a replacement for remainder analysis.
The cutoff for factorial terms has . Better analysis can expose contributions smaller than every retained inverse power, linking optimal truncation to the Stokes phenomenon. Such contributions can be important even when many asymptotic coefficients agree. Directly summing ever more terms does not automatically recover them.
For a polynomial depending on a small parameter, substitute and compare the exponents of the parameter. Candidate root scales arise when two or more lowest exponents balance. Solve the leading scaled equation and expand about each of its nonzero roots. Different balances can reveal different families of roots; real-root counts must be checked separately.
A polynomial whose degree decreases when its parameter vanishes may have roots escaping to infinity. Such a singular perturbation root is found by balancing powers after rescaling . If the root enters an exponential, even a lower-order additive root correction can matter on a fixed interval when its leading exponential grows. This phenomenon is different from a repeated root of a fixed polynomial.
If and , the implicit function theorem gives a local root branch. For analytic coefficients it has an ordinary power series in the perturbation parameter. Its corrections follow by substituting that series into the polynomial and comparing coefficients. A vanishing leading root may require its first nonzero correction to capture a slow exponential mode.
Suppose , is smooth and positive near zero with , and as . The leading contribution tois obtained by scaling and replacing by . Integration of the resulting reciprocal quadratic gives the displayed formula. For constant the exact expression isThis proves the half-peak value at and the transition between an interior peak and a pole outside the interval. If varies, smoothness and positivity on the contributing neighborhood justify its leading replacement; other zeros or singular contributions elsewhere must be excluded.
If has a simple interior zero and , the inner variable turns the local integral into . Thus a peak with vanishing width can retain finite area. Slowly varying positive regularization factors cancel between peak height and width when the numerator has the matching factor. An ordinary outer expansion can miss this contribution even though the peak is exponentially narrow.
Exponentially small contributions can change their asymptotic representation when a complex parameter crosses a Stokes direction. An all-orders asymptotic expansion in inverse powers alone does not resolve these terms.
At an unramified irregular singular point with distinct leading eigenvalues, a sectorial fundamental solution is a fundamental matrix whose entries are holomorphic functions asymptotic to a prescribed formal matrix on a sector of the logarithm cover. For competing cubic exponentials, the usual construction uses six overlapping sectors with basic angle . A formal power series need not converge, and two sectorial realizations may differ by exponentially small terms across a sector boundary.
Two sectorial fundamental solutions of the same linear system differ on their overlap by a constant invertible right factor, since . With a common formal normalization these factors encode the exponentially small ambiguities invisible to the asymptotic expansion. They are called Stokes matrices. Equivalently their inverses act on column vectors of solution coefficients; the convention must be specified when ordering products.
The saddle and endpoint asymptotic expansions of this entire function have algebraic coefficients in sectors , where and . Deforming the contour onto the decay ray gives its complete integral . The endpoint contribution is . The algebraic coefficient switches at ; the equal-exponential-magnitude anti-Stokes lines are the intervening rays .
Near , set on the branch with argument near zero and truncate the endpoint expansion at terms. Its remaining factorial series, indexed by , is times the Borel summation of . The upper-pole contour fixes the stated remainder and its continuation from the sector below the switching line. With , the Gaussian pole transition for a large gamma parameter smooths the algebraic coefficient from to .
The integral in the lower half-plane extends to the displayed entire function. In the upper half-plane the continued function differs from the directly evaluated real-contour integral by . Its algebraic expansion is . The real axes are switching lines for the exponentially small term under the Stokes-multiplier convention; the diagonal rays are equal-magnitude boundaries for the exponential and algebraic mechanisms. Stating both the residue jump and the sector domains prevents confusion between switching and dominance conventions.
For , the factor has saddle scale and becomes . If the amplitude has a simple pole there, its leading local integral contains . Differentiating its Cauchy principal value with respect to reduces it to a Gaussian integral, producing an error function. The nonsingular amplitude gives .
The pole contour in a Gaussian saddle coalescing with a simple pole changes the multiplier smoothly. For the lower contour, . This follows by integrating and adding the indentation contribution . The transition width is inverse square root of the large parameter; on a Stokes line the multiplier takes half its switched-on value.
For the upper-pole integral , let and . Scaling gives at leading order. At its indentation is . Differentiation with respect to gives , so integration gives the displayed error function. This is an optimal truncation transition; the underlying analytic integral has no literal discontinuity. The general mechanism is discussed in the DLMF account of Stokes smoothing.
With the equal-magnitude convention, an anti-Stokes line has for competing exponentials. For , its rays are . Crossing one interchanges which exponential grows. Some literature interchanges the names, so the action-based convention should always be specified.
With the convention used here, a Stokes line is a ray where competing exponential actions have the same imaginary part. A subdominant exponential can acquire a rapidly changing multiplier there. For , these rays have . The anti-Stokes lines instead have equal exponential magnitudes.
Series reversion constructs the local inverse of a power series. Substituting an ansatz for the inverse and matching successive powers determines its coefficients recursively.
Suppose with . Substitute and compare coefficients. The three equations are , , and . Solving them proves the title formula. This is series reversion for a local inverse function; analyticity guarantees a convergent inverse series sufficiently near the origin.
The divide-and-conquer method splits an integral at an intermediate scale, expands each part in the regime where its approximation is uniform, and cancels the artificial splitting parameter after the pieces are recombined.
An asymptotic sequence orders the scales against which successive errors are compared. On a specified domain approaching , suppose each is nonzero sufficiently close to the limit andEquivalently, in little o notation. The notationmeans that for every ,Each stays fixed while the parameter tends to its limit.[ref]
2.1 Definitions and Elementary Properties. NIST Digital Library of Mathematical Functions, §2.1(v), generalized asymptotic scales and expansions
As , is an asymptotic sequence, because each adjacent ratio is . Fractional scales work too, with ratio . By contrast, fails at its first pair: the second scale is not smaller than the first. Ordering by written position alone does not create a hierarchy of sizes.
Successive division of the remainder by uniquely recovers every coefficient:If two proposed expansions first differ at order , subtracting them and dividing by would give a nonzero constant tending to zero, a contradiction. This is uniqueness of the coefficients in a fixed scale, not uniqueness of the represented function.
For the factorial integral example, the first three limiting responses are , , and . They extract exactly the coefficients . Choosing an asymptotic sequence therefore turns “the next small correction” into a precise and reusable operation.
For a positive asymptotic sequence , define andThen term by term and is again an asymptotic sequence.
Even if for every , an expansion in the scale need not induce one in . A perturbation of that is smaller than but larger than supplies a counterexample.
If a smooth real phase has a unique nondegenerate interior maximum at , thenFor a maximum at an endpoint with , the leading factor is .
If a nonnegative smooth phase has an isolated cubic zero at one endpoint and an isolated quadratic zero at the other, their leading Laplace's method contributions scale respectively as and . The first two global terms therefore come from different endpoints, rather than from the first two terms at the dominant endpoint. When the cubic endpoint has no quartic phase term and constant amplitude, its next local term starts at ; cubic corrections at the quadratic endpoint also start at that order.
At a unique interior maximum with positive-definite negative Hessian matrix, a quadratic expansion and rescaling by give the displayed Gaussian integral, provided the tails are negligible. In a regular Bayesian inference it approximates the integrated likelihood by the likelihood at its dominant point times the prior density and inverse square root of local curvature. Boundary modes, singular Hessians, and multiple equally dominant modes need modified formulas.
A unique nondegenerate interior minimum does not by itself ensure that a integral treated by Laplace's method is localized there. A sufficient condition is a positive gap above the minimum outside every sufficiently small fixed neighbourhood, together with finiteness of the integral for some positive exponent. The exterior contribution is then exponentially negligible. Without localization, on has its unique interior minimum at zero with , but its boundary contribution is at least and dominates the nominal interior Gaussian contribution.
For a smooth real phase decreasing away from its endpoint maximum, put and write the transformed amplitude as . Its first two Taylor coefficients are and . Applying Watson lemma gives the displayed two-term Laplace integral expansion. Localization and a Taylor remainder estimate justify termwise integration.
If an odd amplitude multiplies an even Gaussian phase on an interval asymmetric about its interior minimum, the symmetric central integral cancels exactly. The surviving leading term can be exponentially small and comes from the nearer unmatched endpoint. For example,An interior Laplace method expansion alone yields zero to every algebraic order and does not capture this term.
If a real smooth phase has its strict maximum at the upper endpoint and , then . The endpoint coordinate has scale . At a nondegenerate stationary endpoint the scale is instead and the leading contribution is half a Gaussian integral.
A Laplace integral contains a large parameter in an exponential weight, typically in the form or . Its asymptotic behavior is controlled by the points where the real part of the phase is largest.
For a contour integral with factor , the quartic term dominates the linear term on rays at large radius. Writing gives real part for the leading exponent. There are four decay sectors, centered at and each of angular width . On a closed subsector the integrand and all its derivatives decay faster than any exponential in , locally uniformly in . Contours joining two such sectors therefore allow differentiation under the integral sign and have vanishing infinite endpoint terms. Distinct geometric contours still need an independence proof; their initial moments often give a Vandermonde matrix calculation.
A linear differential-equation solution may be sought as . Integration by parts transfers the factor to derivatives of , giving an equation for the amplitude and boundary terms. Admissible contours must cancel those terms and make the integral converge.
A null weight contributes zero to a Laplace integral on its domain of convergence. It can be added to a weight without changing the represented function, so an integration-by-parts differential equation for the weight is not an unconditional uniqueness theorem.
For example, let enter along angle from infinity to zero and leave along angle to infinity. The entire weight is null for every complex . Throughout the wedge between those rays, ; the factor is dominated by this quadratic decay. Closing the contour by a large circular arc and applying the Cauchy integral theorem therefore proves the zero integral. All derivatives with respect to converge locally uniformly as well.
On the same contour, the quartic weight gives a nontrivial entire solution. Its rays can be deformed within the quartic decay sectors for a contour integral to angles and , where the value at is . Adding the null weight changes neither this integral nor its vanishing endpoint terms, but the sum does not satisfy . Thus the usual Laplace method selects a convenient weight by cancelling the interior integrand separately; a necessity claim needs additional injectivity assumptions.
If the maximum of the smooth real phase is an endpoint, , and , the local Gaussian is integrated over only one side of its peak. Consequentlywith the analogous formula for a right endpoint.
If a Laplace integral has finitely many separated nondegenerate global maxima with the same phase value, its leading term is the sum of their local Gaussian contributions. An interior maximum contributes a full Gaussian integral, while a stationary endpoint maximum contributes half of one.
Suppose a real phase has its unique minimum at the left endpoint and , with and integer . For a continuous amplitude with , localization followed by givesThis uses the Gamma integral. It assumes sufficient decay away from the minimum to make the remaining integral negligible. A cubic endpoint has width ; an ordinary quadratic endpoint has width .
For a Laplace integral with local phase , , an interior minimum approaches the endpoint as . The distinguished limit is , . With , its leading local integral isThe cubic Laplace transition integral joins the ordinary endpoint estimate for positive , the cubic endpoint estimate at zero, and the interior Laplace's method estimate for negative . Separate fixed-parameter formulas fail to be uniform when the minimum is within its own width of the endpoint.
The discrete Laplace method estimates a sum whose positive terms concentrate near the maximum of a smooth exponent. When the Gaussian concentration width contains asymptotically many lattice points, the sum is a Riemann-sum version of Laplace's method with the corresponding lattice-spacing factor.
A contour integral with a large exponential parameter is deformed through saddle points along curves on which the real part of the phase decreases most rapidly and the imaginary part is locally constant.
For an exponential integral with phase , a constant-phase contour holds the imaginary part of fixed. Along it, decreasing real part of gives steepest descent, while increasing real part gives steepest ascent. At a cubic stationary point, six rays alternate between descent and ascent.
For an integrand , a contour along which is constant and decreases away from the contributing endpoint or saddle. This suppresses oscillation while localizing the large-parameter integral.
For , the saddle point descent is the real axis and ascent is the imaginary axis. A descent path from a nonzero endpoint has , , with the continuous square-root branch from . It ends at positive or negative real infinity according to the sign of . The oriented outward endpoint contribution in steepest descent is .
For a Gaussian integral from to , a saddle point contribution dominates for . The moving endpoint contribution in steepest descent dominates for . At the two endpoints have equal exponential rates and both are needed; for larger angles the fixed endpoint dominates. Saddle connectivity switches at , but that change is subdominant in the leading endpoint regime.
If a deformed contour starts at an endpoint with and initially enters a decaying sector, local integration gives the leading contribution , with the sign adjusted to the contour orientation.


