A singular perturbation is a parameter-dependent problem whose limiting problem changes qualitatively as the parameter tends to zero. In an ordinary differential equation, a small coefficient of the highest derivative can reduce the order of the limiting differential equation, preventing it from satisfying all the original boundary conditions. Different length or time scales often require different asymptotic expansions.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §1.1.2, p. 2: regular and singular perturbations
Consider the boundary value problemThis second-order differential equation is exactly solvable. Setting gives the first-order linear differential equation , so . One integration and the two boundary conditions giveBoth boundary conditions hold for every positive . For numerical evaluation, write the same ratio as , where evaluates the exponential function minus one without catastrophic cancellation near . Keep the denominator for finite : at it is approximately , rather than exactly one.
Setting gives . The outer solution selected by the right boundary condition is therefore , which fails the left boundary condition. The exact exponential function shows how that mismatch is repaired: the solution rises from zero to almost one within a boundary layer of width , using Big O notation. For each fixed , , while always. This pointwise convergence fails to be uniform convergence to the outer solution on , since for every .
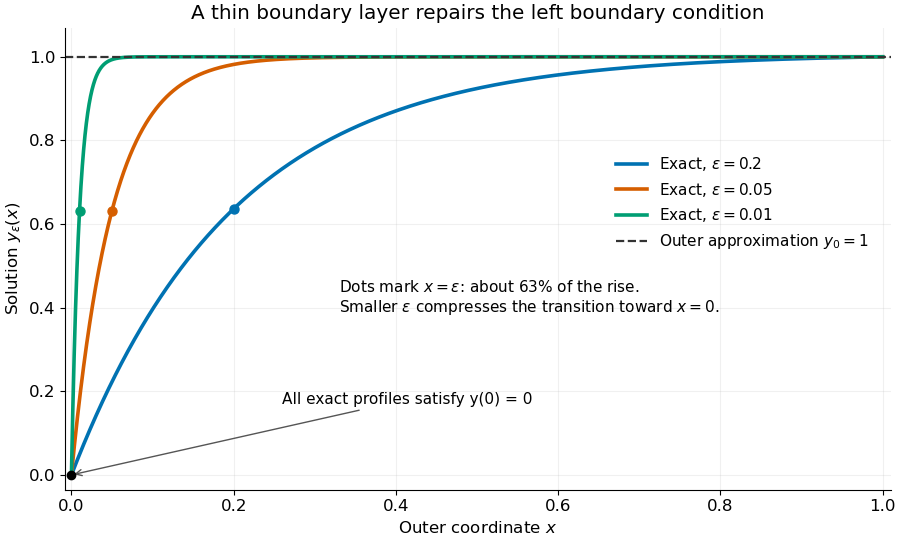
Exact solutions with a shrinking left boundary layer
. The exact normalized profiles at , , and satisfy both boundary conditions. The dashed outer solution misses the left boundary condition. Colored dots mark , where most of the initial rise has already occurred. Details.The coefficient is small, but its product with the second derivative need not be small. Direct differentiation givesAt with fixed , these derivatives grow as and respectively as . Consequently and have exactly equal magnitudes and opposite signs. Even away from the boundary layer, their magnitudes remain equal in this example; both become exponentially small at each fixed positive . The outer expansion neglects an exponentially small transient there, rather than establishing that one derivative term is smaller than the other everywhere.
To predict the width without knowing the exact solution, suppose an order-one change occurs over distance . The derivative scales are and . The dominant balance gives . The resulting inner variable makes the boundary layer visible at a fixed scale. This is the useful feature of singular perturbation: an apparently disappearing term identifies the missing structure when one measures its derivatives on the appropriate scale.
For , with fixed and , the Liénard coordinate has fast horizontal jumps and slow motion on . The slow time is . Integrating along and gives the displayed period. The two jumps take negligible time at this scale. For fixed , the right attracting branch contains the stable equilibrium and the large relaxation cycle disappears.
For a fast-slow system , with , the rescaled time gives , . Away from zeros of , an order-one change of takes order-one fast time but only order- original time, while changes little. Setting in these rescaled equations freezes and produces the leading fast subsystem. This limit differs from the slow reduction in the original time; matching the two describes a relaxation oscillation.
In a fast-slow singular perturbation , , the critical manifold is . A slow manifold for positive is a nearby locally invariant manifold on which the rapid transient has relaxed and the remaining motion occurs on the original slow time. These two manifolds generally differ: invariance must account for motion of , not just set its instantaneous fast equilibrium.
For example, consider , . A graph is invariant only ifFor , satisfies this identity, whereas the critical manifold does not. The transverse displacement obeys and decays rapidly. Thus the slow graph is displaced by on bounded intervals and attracts with an explicitly separated time scale.
Persistence of a smooth slow graph requires suitable smoothness and uniform normal hyperbolicity on the region considered, usually a compact piece of the critical manifold. Negative real parts of the fast linearization give attraction; near a fold point of a critical manifold, this spectral condition fails and the simple reduction can break down.
An initial layer is a short transient needed when the reduced outer solution cannot satisfy the original initial condition. On an inner time scale, terms multiplied by a small parameter remain comparable to the retained dynamics. For , , the inner solution matches the outer value while retaining the initial datum.
For , the two terms in are equal at . Their ratio is larger than one for and smaller than one for . As it tends to infinity at fixed and to zero at fixed . Comparable contributions require , equivalently .
To resolve this region exactly, introduce the inner variable . Then for bounded . At fixed , the first term is smaller than every positive integer power of , so a regular perturbation in powers of misses it. At fixed , that same term diverges. This explains why a power series approximation valid on one side need not be a uniform approximation across the crossover.
For a system , with fast variable and slow variable , the critical manifold is the set of equilibria of the fast problem with frozen. It is attracting where the fast Jacobian matrix has eigenvalues with negative real parts and repelling where those real parts are positive. A smooth graph can cease to be attracting at a fold point of a critical manifold.
For a critical manifold of a fast-slow system , , normal hyperbolicity means that the fast linearization has no eigenvalue with zero real part along the manifold. The slow variables are frozen for this fast subsystem. Uniform estimates on a compact portion require the real parts to remain bounded away from zero.
For , the critical manifold is and the fast derivative is . Its positive- branch is attracting and its negative- branch repelling. At the fold the fast eigenvalue is zero, so normal hyperbolicity fails and the usual fast relaxation can break down.
In the broader dynamical-systems definition, contraction or expansion transverse to an invariant manifold must dominate the tangent dynamics. For a critical manifold of the limiting fast problem, tangent directions are equilibria, giving the stated nonzero-real-part test. A nonzero purely imaginary eigenvalue fails this test even though the Jacobian is invertible.
For one fast and one slow variable, a nondegenerate fold point of a critical manifold satisfies and . An attracting and a repelling branch of fast equilibria meet there. A slow trajectory reaching the fold generally leaves by a rapid jump when its slow drift crosses the fold transversely. The fold is defined relative to the fast direction: if fast trajectories are slanted in the plotted coordinates, their tangency to the critical manifold need not be an extremum of its plotted height.
Near a nondegenerate fold point of a critical manifold crossed with nonzero slow speed, the local balance can be written , up to nonzero scalings and higher-order terms. A time interval gives ; balancing with gives , and balancing with gives , . This layer delays departure from the fold relative to an instantaneous singular jump. It differs from the order- fast motion away from the fold.
A singular limit is a parameter limit in which the governing problem loses an order, changes type, or otherwise changes its qualitative solution structure. For , setting produces the algebraic constraint and can omit fast transients required by the initial data.
In the rigid-backed shear-wave dispersion equation , take fixed and let . The highest intersection approaches the endpoint . Setting and using gives the displayed asymptotic expansion. At the appropriate balance is instead . Near that transition, with , the leading equation is , where now and .
For a weakly perturbed harmonic oscillator, expand both its periodic solution and its angular frequency, using the stretched time . At each order, choose the frequency correction to remove fundamental-harmonic forcing that would produce a secular term. For a self-excited periodic orbit, cancellation of the independent sine and cosine terms can determine both the leading amplitude and the frequency correction. Actual existence follows when the associated Poincaré return map has a simple displacement zero, by the implicit function theorem.
A homogeneous mode can be order one inside an interval and exponentially small at an endpoint. Adjusting an endpoint value beyond all algebraic orders can then change the interior solution by order one. In the nested layers at an essential singular endpoint example, the mode has this behavior: prescribed exact endpoint values give a unique solution for each fixed positive , but leading asymptotic endpoint data do not select a unique bounded family.
Adiabatic elimination replaces a rapidly relaxing variable by its instantaneous stable quasistatic value. If with , write , . Then . After the transient, when coefficients vary slowly compared with . This gives both the leading reduction and its time-scale error; rapid relaxation alone does not justify an additional Taylor expansion in another parameter.
A matched asymptotic expansion constructs approximations in regions with different distinguished limits and fixes their free constants by requiring agreement in an overlap region. The inner expansion resolves rapid variation; the outer expansion describes the surrounding region. Matching compares their common limiting behavior, rather than imposing distant boundary conditions directly on a local approximation.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §§4.3.3–4.3.4, pp. 57–58: inner expansion and matching
For the singular perturbation problem , , , the leading outer solution is . The inner variable gives and , hence . In the overlap region , the inner variable tends to infinity while the outer coordinate tends to zero. The asymptotic matching condition isso . One concrete path through the overlap region is : then and . Matching selects the free constant that the left boundary condition alone could not determine.
Why choose the right boundary condition for the outer solution? If instead one selects from the left, a proposed right boundary layer with satisfies . Its general solution is . Matching to zero as forces , contradicting . The direction in which the exponential function decays determines which endpoint can carry the boundary layer; endpoint selection is part of the calculation.
An interior layer is a narrow region of rapid variation lying inside a singular perturbation domain, separated from its boundary. Away from it, a slowly varying outer approximation is valid; a stretched inner variable resolves the transition near the layer location.
For example,has the exact solution . As , it approaches for fixed negative and for fixed positive . Neither constant outer branch describes the transition at zero. The inner coordinate gives and .
Thus the transition has width proportional to and central slope . Matching requires as and as . The same principle can describe thin internal fronts in differential equations; boundary layers instead lie near boundary data or a domain edge.
Split the integral at . Replacing the numerator by one below the cutoff gives , with an error bounded by . Above the cutoff, replacing the denominator by has relative error , and integration by parts gives . The inner cancels the outer , and all errors are , proving the leading constant independently of the intermediate cutoff.
For near zero, dominant balance gives a diffusion-drift layer of thickness for , with the reaction term negligible. At , all three terms survive on the scale . For , diffusion and reaction first balance on wavelength , while the drift damps the oscillation on the larger envelope scale . Removing the first derivative gives the envelope factor . For , no shrinking algebraic diffusion layer of this regular bounded type is obtained.
For a positive small parameter , an order-one mismatch between the reduced solution and a prescribed right endpoint value creates a right boundary layer. Balancing against the order-one reaction term gives width . In the inner variable , the leading equation is . Its boundary and matching conditions are and as , soThe leading additive composite expansion is , obtained by subtracting the common overlap value. For the nonlinear perturbation with zero endpoint values, the first two outer expansion terms are , and the leading right-layer term is .
For , , , the exact outer solution is and the mismatch is at the right endpoint. In , matching gives and . Differentiation at gives the displayed endpoint slope. The order-one term requires the first inner correction; differentiating only the leading boundary layer loses it.
A growing linear mode can make a formally small derivative nonlinearity order one at large distance. After the crossover scaling, the equation reduces to a logistic differential equation in for . Matching at small gives and the displayed primitive with . It changes from quadratic growth to linear growth without a finite turning singularity.
When the early growing solution is and the nonlinear coefficient depends on , its crossover occurs at the displayed scale. If is order one this is ; if the initial slope suppresses the leading mode and , it is delayed to . The first nonzero perturbative seed must therefore be computed before constructing the global leading approximation; setting the small parameter to zero can erase the mode that ultimately dominates.
For , matching , fixes the first integral to . Hence endpoint values above cannot match this outer branch. The upper family is . An endpoint value strictly between and admits two translations, one initially approaching and one initially moving towards the turning value . Values below give the unique lower family with . Matching to zero instead gives , which forbids a nonconstant real approach to zero. These are leading boundary layer classifications, not exact multiplicity theorems at degenerate endpoint data.
In , balancing all three terms where the outer branches and meet gives the displayed dominant balance and the inner equation . Matching to and writing gives . Its linearized decaying correction is an Airy function; the growing correction is excluded. Matching to zero instead gives , whose nonzero Airy function combinations oscillate. Thus the acceptable matching branches differ qualitatively at the turning endpoint.
An asymptotic matching condition requires the inner expansion and outer expansion, re-expressed in a common overlap region, to agree to the retained order. Both function values and slopes may constrain the free constants. In the square-root reaction problem with nested boundary layers, the shared small plateau sets the first integral of a square-root reaction layer, while its large-field fourth-power tail fixes the neighboring broad layer.
For fixed and endpoint values , , the outer solution is . The left boundary layer has width . At the right, a layer of width carries the order-one rise, and a translated layer of width connects its inner edge to the small plateau. The dominant balance depends on both amplitude and derivative scale; using the same scale at both ends loses a necessary match.
After and or a translated version, the layer equation is . Multiplying by and matching , fixes the energy constant to and gives the displayed factorization. The increasing branch below approaches it at positive infinity; the increasing branch above it leaves it at negative infinity and grows like . This supplies both interfaces of the square-root reaction problem with nested boundary layers.
Multiplication by makes this example exactly integrable once: . Its homogeneous solution is . A solution with that remains uniformly bounded needs , hence . The scales and connect the small outer solution to the order-one endpoint value. Bounded homogeneous contributions remain invisible to algebraic matching at the right boundary.
A decaying algebraic tail in an inner asymptotic expansion can become a fractional-order outer correction after rescaling. For an inner tail proportional to and outer variable , the outer correction is proportional to . If the next outer correction contains , expressing it in the inner variable produces both and . Omitting the latter loses a term larger than a plain correction. Matching must include all these scales and constants, rather than only the leading algebraic powers.
In a singular first-order equation with coefficient , an outer correction proportional to cannot be evaluated at the endpoint. The inner scale changes it to . Matching retains the logarithmic constant, which is larger than a plain order-epsilon correction. For , , the exact solution verifies the displayed endpoint asymptotic and its remainder.
The equation integrates to . Equal endpoint data force and give the unique Gaussian solution above. Its central width is , with amplitude . The exponentially large central mode is missed by an assumed bounded algebraic outer expansion . Changes of order one relative to either endpoint value occur over distance from that endpoint.
For on , removing the drift by givesThe transformed potential changes sign at . WKB approximation is oscillatory inside and exponential outside this turning region; an Airy turning-point connection formula applies over width . At the endpoint the wavelength is , while the physical exponential prefactor changes on the envelope scale . Balancing only diffusion and drift and declaring a single layer misses the zeroth-order term and the turning region. Matching constants may be singular at homogeneous boundary-value resonances.
For with smooth bounded positively away from zero, the first-order equation for the outer expansion is selected by the right boundary condition. The left mismatch is repaired on the scale . If , the leading inner transient is . Its next equation is . Matching its constant and linear large- terms to the outer expansion permits an order- composite approximation. A sign reversal of the drift places the transient at the opposite endpoint.
If a leading outer expansion diverges as and a derivative coefficient contains , balancing that nonlinear correction gives a layer larger than . Write with and subtract the large negative constant from . Matching often introduces a correction and yields an endpoint slope of order . The balance must be derived from the actual equation; logarithmic divergence alone does not fix a universal layer width.
For with left endpoint , diffusion there is of size . The distinguished coordinate is , giving . Matching to one with zero left value gives . The layer width is different from the endpoint's distance from zero.
In , the drift vanishes at the endpoint . Balancing diffusion against drift gives the inner expansion coordinate . The leading layer equation is , with a bounded error function profile. A regular outer first-order calculation alone cannot impose both endpoint values.
If an outer expansion contains and the layer coordinate is , its overlap contains . Matching forces an inner expansion term when that homogeneous profile tends to one in the overlap and vanishes at the boundary. The logarithm multiplies the matching profile, rather than an arbitrary constant.
An overlap region is a parameter-dependent range in which two neighboring asymptotic expansions have simultaneously ordered common limits. Between scales and , it is : the narrow coordinate tends to infinity while the wider coordinate tends to zero. Matching uses these limiting descriptions, not an assertion that either expansion is uniform at all values of the other's scaled variable.
An intermediate asymptotic region has a scale between two other scales and provides their connecting matched asymptotic expansion. It can be needed because a coefficient changes its dominant form before the narrowest region's highest-derivative balance is reached. For example, a coefficient changes near even when the fast inner expansion has width . The intermediate solution must be matched at both ends rather than assigned an independent boundary value.
A simple zero of an advection coefficient can support an interior layer. For the specific homogeneous equationset . The two derivative terms then have the same order, giving . Hence andconnects and . Its physical width is . More generally, , in gives the same width, while the sign of determines whether the nonconstant Gaussian derivative decays.
An order-one reaction term cannot be hidden in this balance: adding gives the leading inner equation . An arbitrary pair of constants need not match that equation. The error function connection above requires the extra terms to vanish or be negligible at leading order; reversing diffusion also changes the bounded matching structure.
Reversing the diffusion sign changes which rapid modes remain bounded. In the explicit modelintegration gives . ThusThe numerator and denominator are dominated by endpoints. Away from both endpoints, the limit is , since the two endpoint contributions in the denominator are equal. The leading boundary layer factors are and , of width .
On the interior scale , has , so a bounded leading inner solution cannot connect unequal constants at both infinities. For equations with extra reaction or forcing, the selected bulk value and smaller interior corrections depend on those terms and their solvability condition; the simple-zero drift alone does not determine them.
A distinguished limit rescales a parameter-dependent problem so that competing terms contribute together to its leading dominant balance. It identifies a transition regime rather than merely setting the small parameter to zero. For with an order-one change across width , the two terms scale as and . Their ratio stays order one precisely when is proportional to .
With , the leading equation is . A much broader scale discards diffusion; a much narrower one discards drift. Neither alone captures a bounded nonconstant transition from the endpoint value to the outer solution. The amplitude scale matters as well as the length scale, as the one-third-power scaling at a nonlinear turning endpoint illustrates.
An inner expansion is an asymptotic expansion in a stretched variable that resolves a region of rapid variation. If its width is near , write and expand with fixed. The chain rule makes , so even a small coefficient of a high derivative can contribute at leading order.
For at a left endpoint, dominant balance gives . The leading inner equation is , and , give . Its nonconstant profile supplies the endpoint information lost by the constant outer solution. The condition at infinity is an asymptotic matching condition in an overlap region; it is not a claim that a truncated inner formula is uniformly accurate arbitrarily far from the layer.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §4.3.3, inner expansion; §4.3.4, matching
The singular perturbation equation balances its derivatives on the width . The inner equation is , so . Its solution with and is the displayed , since . Near zero , so the first derivative is finite while the second is singular. Treat the differential equation on the open interval and impose the endpoint value by continuous extension.
An inner variable is a stretched coordinate such as that remains order one inside a thin region of width . Its scale is chosen by a dominant balance, rather than by the size of a coefficient alone.
For the singular perturbation problem with , , set and . The chain rule givesThus both derivative terms survive in the inner differential equation . The exact domain is , withFor bounded , as : the inner expansion has a nonconstant limiting profile even though the outer solution is constant. The finite- profiles nearly collapse onto after rescaling, with their remaining difference coming from the normalization at the distant right endpoint.
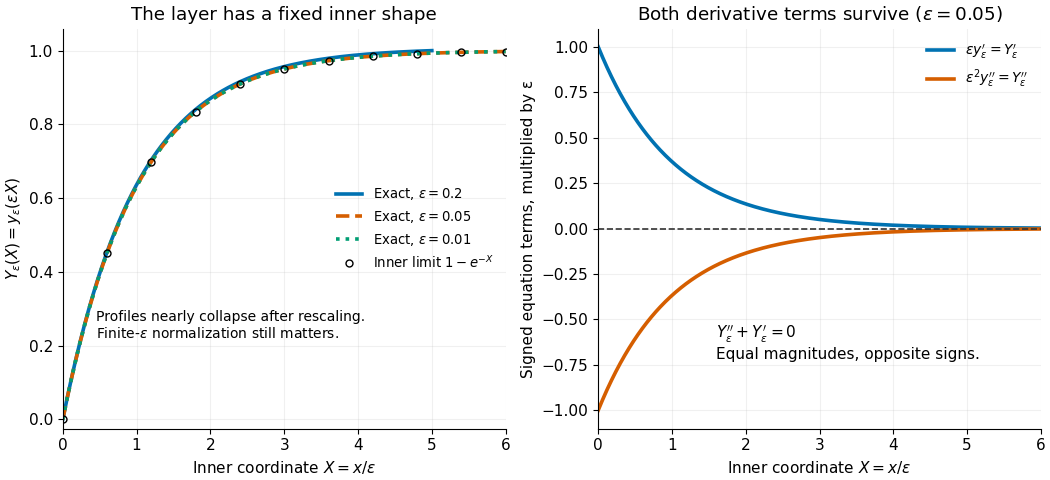
Inner rescaling reveals the common profile and derivative balance
. Left: the exact normalized profiles nearly coincide as functions of the inner variable ; the curve ends at , its actual right boundary. Right: multiplication of the original differential equation by gives the signed terms and , which cancel exactly. Details.An outer expansion describes the solution away from a thin or distant region resolved by an inner expansion. It is matched to that inner expansion in their common overlap region. Its range of validity must be specified: an approximation at each fixed positive need not have uniform convergence down to an endpoint.
For the singular perturbation problem , , , try the asymptotic expansion at fixed . Substitution gives and for . Expanding the right boundary condition gives and for . Therefore and every higher coefficient vanishes. The missing boundary layer is exponentially small at each fixed positive , invisible to all these powers of .
The exact solution supplies a quantitative limit. For every fixed ,This is uniform convergence on . On the same supremum norm of the error is exactly one. The inner expansion supplies the endpoint information that this outer expansion cannot encode.
An additive composite expansion combines an inner expansion and an outer expansion by subtracting their common behavior in the overlap region:The subtraction removes the part counted twice. Near the boundary layer, the outer expansion cancels the overlap contribution; away from the boundary layer, the inner expansion cancels it. An error estimate is needed to establish accuracy across the whole domain.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §4.3.5, p. 58: uniform solution and overlap subtraction
For the singular perturbation problem , , , the outer solution is one, the leading inner expansion is , and their overlap is one. Thus . With , comparison with the exact normalized solution givesThe supremum norm error is therefore exponentially small on the entire interval, even though the outer solution alone has error one. This is an error bound for function values; errors in derivatives have additional powers of .
The composite satisfies the differential equation exactly but has right boundary condition . Dividing it by restores that boundary condition and recovers the exact solution. This example makes both the strength and the limit of matching explicit: it gives a global approximation, while finite- normalization can still carry information beyond every algebraic order.
When inner and outer approximations share a nonzero multiplicative overlap, a multiplicative composite divides their product by that common part. It is especially convenient when different regions contribute separate exponential or boundary-layer factors.
An outflow boundary layer repairs a boundary value discarded by a reduced convection equation at the end where the physical convection leaves the interval. Signs must be read from the full operator. Formultiplication by minus one puts the equation in the conventional form with . Flow is toward the left, so the right endpoint is inflow and the left endpoint is outflow. The outer solution takes its right boundary condition, while a left transient proportional to supplies the missing value.
For , , , , the exact solution is . It approaches the right-selected bulk value one and has a left boundary layer. Reversing the convection sign reverses the endpoint carrying the decaying transient.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §4.3.6, Why is the boundary layer at x=0?
For with and , the outer solution is . The right-end boundary layer has width and leading correction . This follows by setting , solving , and matching its constant part. The leading correction changes sign at .
A switchback term such as is forced into a matched expansion when logarithms of a stretched coordinate split into parameter-dependent and local pieces in the overlap region.
If a stretched variable is and an outer expansion contains , its expression in the fixed- region is . The parameter logarithm must therefore be present in the inner expansion, often multiplying a homogeneous solution selected by a boundary condition. An ansatz containing only integer powers with parameter-independent coefficients misses this switchback term. The same reasoning applies to other powers of and other stretched-coordinate scalings.
The method of multiple scales describes motion with widely separated time or length scales by treating them as independent variables during an asymptotic expansion. With fast time and slow time , write and useAt each order, a solvability condition in the method of multiple scales removes resonant forcing forcing that would generate a secular term. The resulting amplitude-phase equations describe accumulated changes over many fast periods.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. Chapter5, introduction; §5.3, two-time expansion and averaged equation
For , put . The first correction obeysIts cosine and sine coefficients vanish precisely when and . For , , the leading result is with bounded corrections. A fixed-time expansion instead contains , which becomes order one when . This explains the slow variable's purpose; eliminating resonances is a construction step, while an error estimate is needed to establish uniform accuracy on a stated time interval.
For and with leading oscillation , , averaging the auxiliary equation gives . Cancellation of resonant forcing in the oscillator gives . With and , and the displayed amplitude follows. Bounded oscillatory corrections repair the instantaneous auxiliary equation; secular terms in a fixed-time expansion show why the slow scale is needed.
For , the method of multiple scales gives no first-order phase drift. If is odd, the amplitude obeys the displayed damping law with . If is even, the average is zero and the amplitude is unchanged on the first slow time . The odd case dissipates mechanical energy, whereas the even case is reversible and its force is not damping of both velocity signs.
Two fundamental harmonics of frequency one multiply into only a constant and second harmonics. The first-order solvability condition in the method of multiple scales therefore has no amplitude-changing resonant coupling. Their first-order particular corrections can mix back into the fundamental at second order, selecting the possible scale . Detuning may suppress the resulting resonance, so identifying this scale alone does not prove instability for every initial state.
For , a leading oscillation has slow time . The first-order forcing contains only zero and double frequencies. At second order the fundamental forcing is ; eliminating resonance gives the displayed equation. Its modulus is constant and its phase drifts. A leading real amplitude therefore has frequency . This replaces a secular phase term by a uniformly modulated oscillation.
For , write and . Removing secular terms gives and , where the brackets mean a period average. This is the first-order solvability condition in the method of multiple scales, with a slowly evolving amplitude and no first-order frequency correction.
For and unit initial amplitude, averaging uses . Thus and the displayed algebraic envelope follows. The leading phase has no first-order drift. The dissipation is amplitude dependent, so an exponential envelope with a constant decay rate would give the wrong long-time scale.
For , the averaged amplitude for position-dependent damping has the displayed logistic-type equation. With , its positive solution is . Small amplitudes grow and large ones decay toward the stable value two; the leading oscillation is .
For , use and . Removal of secular terms gives and the displayed amplitude equation. With , , which is explicitly integrable. If is replaced by a slowly varying coefficient , the same solution uses the accumulated time . The method of multiple scales is uniform on bounded slow-time intervals only while its amplitude and correction estimates remain bounded.
If is odd, its average vanishes under a half-period shift. Hence the averaged amplitude for position-dependent damping is constant at first order. Odd-power damping creates only even harmonics when multiplied by the leading oscillator velocity; these do not resonate with the fundamental harmonic. Higher-order drift is still possible.
A secular term is a perturbative correction whose growth makes an initially ordered asymptotic expansion fail on a longer scale. A forcing at the natural frequency of a harmonic oscillator gives the simplest example:is a particular solution, as direct differentiation verifies. Although is small at fixed , it can be order one at .
Such growth need not mean the exact solution grows. The exact bounded oscillation expands as at fixed time: its secular term represents accumulating phase error. The Poincaré-Lindstedt method absorbs this into a corrected angular frequency, while the method of multiple scales evolves a slow phase or amplitude.
Whitham modulation theory describes a wave train whose amplitude, wavenumber and angular frequency change slowly compared with its wavelength and period. For a variational principle, insert a locally periodic profile into the Lagrangian, average over the fast phase and vary the resulting averaged Lagrangian. This replaces detailed oscillations by equations for their slowly changing parameters, as developed by Gerald Beresford Whitham.[ref]
A general approach to linear and non-linear dispersive waves using a Lagrangian by Gerald Beresford Whitham. abstract, nonuniform wave trains and variational formulation
With slow variables and phase , define and . Equality of mixed partial derivatives gives the independent wave-compatibility lawVariation of the slow phase gives the Whitham modulation equation, while profile or amplitude variations give other closure relations. These equations are leading-order asymptotic expansions under scale separation; a change of modulation type or crossing of its characteristic curves can invalidate the smooth slow description even while the original oscillatory wave remains meaningful.
The averaged Lagrangian is the mean over one fast phase of a Lagrangian evaluated on a locally periodic wave profile. Holding its slow parameters fixed during this average yields a function of those parameters, the wavenumber and the angular frequency. A simple explicit example starts fromSince the average of is , one obtainsFor , variation with respect to gives the dispersion relation . Variation of the slow phase instead gives the wave-action conservation law. The distinction matters: substituting the dispersion relation into before differentiating would set it to zero and erase the nonzero derivatives encoding the conserved wave quantity. General nonlinear waves require averaging their full periodic profile and retaining its shape parameters.
For a periodic travelling profile , an autonomous fast-phase Euler-Lagrange equation has a first integral. For example, the field Lagrangian and phase giveMultiplication by yieldsThus the bracketed profile energy is constant during one fast cycle. In a wave described by Whitham modulation theory, its parameters also vary on slow scales. The fast identity alone does not determine that slow evolution: one must retain the next-order terms and impose their averaged solvability condition, or vary the averaged Lagrangian. A periodic total phase derivative averages to zero, which is the useful simplification in either route.
Fix the phase convention , . If the averaged action is , a compactly supported phase variation gives , . Integration by parts then yieldsDefining the wave-action density and its flux puts the same equation in the conservative form . This sign follows from the declared negative time derivative of phase. It must be combined with and any profile-parameter equations to close a modulation problem.
With phase convention , , the wave-action density associated with an averaged Lagrangian is ; the matching flux is . These derivatives are taken before substituting any dispersion relation.
For , one finds and . The averaged energy density of the corresponding linear wave equation is . On a nonzero-frequency dispersion branch, , so . The sign of depends on the frequency and phase convention; it is not independently specified by calling it an energy-like quantity.
The Whitham modulation equation gives with and . For a linear wave family with and simple dispersion relation , assume . Implicit differentiation gives the group velocityHence . In several space dimensions this becomes for the corresponding slowly varying conservative linear-wave branch. A ray tube can therefore change local wave-action density by spreading or compression while conserving its transported integral when boundary fluxes vanish.
The relation between flux and group velocity uses the linear dispersion branch. General nonlinear averaged systems still have , but this need not equal one scalar group speed times . Dissipation, external forcing or interactions can also add source terms, so the homogeneous law requires its conservative, scale-separated setting.
For and , the method of multiple scales gives the displayed amplitude-phase equations, together with constant leading phase. For , is constant and changes exponentially. For and positive amplitude, the integrable phase average is . Thus obeys with . The identically zero oscillator is inadmissible for logarithmic feedback, whose force is undefined there.
When the weak force depends only on velocity, the phase average is a periodic total derivative and vanishes. The leading phase is constant, while the amplitude evolves according to the remaining average. The sign of that drift determines damping or growth and must be checked from the force, rather than inferred from its velocity dependence alone.
For initial amplitude one, the method of multiple scales gives with , hence . Positive damping causes algebraic decay. Negative damping yields a formal finite-time amplitude pole, but the weak-damping assumption fails before it because becomes order one. A leading approximation has order- displacement error on fixed slow-time intervals away from that pole.
For with positive , the oscillator energy increases at rate . The amplitude-phase equations give . The weakly nonlinear expansion fails when the growing amplitude makes large, so its formal finite-time divergence does not itself control the exact late-time trajectory.
For a weak force depending only on position, the amplitude average is a periodic total derivative and vanishes. The leading harmonic amplitude is constant, while the phase may drift. The method of multiple scales agrees with the exact conservation of energy for bounded orbits in the effective potential. A cubic position force on the right side of the oscillator equation lowers the frequency at first order when its coefficient is positive.
A slow time resolves evolution occurring over many periods of a faster process. It is treated as an independent variable in the method of multiple scales.
A weakly nonlinear expansion writes a small disturbance as powers of an amplitude parameter while resolving its evolution on a slow time. Near a critical eigenvalue, linear detuning and nonlinear interactions enter the same perturbation order. The Fredholm solvability condition for a self-adjoint operator, or its adjoint form for a general operator, yields an amplitude equation without requiring the full higher-order correction.
A quadratic product of plane waves generates sums and differences of their wavenumbers and angular frequencies. A component drives a secular term when its generated pair also satisfies the linear dispersion relation. A solvability condition in the method of multiple scales then determines the coupled amplitude equations on a slow time.
Three Fourier modes form a spatial resonance when their wavevectors sum to zero. Products of the conjugate second and third modes then force the first mode, with cyclic counterparts. Such terms couple both amplitudes and phases, unlike self-saturation terms proportional only to squared magnitudes. For three equal wavenumbers, the vectors are separated by degrees and support hexagonal pattern interactions.
Detuning measures the small mismatch from a resonance condition. When the mismatch and nonlinear forcing are both , they enter the same slow time equation. A small shift of the wavenumber can therefore balance a quadratic interaction and permit a locked periodic travelling wave.
A resonant interaction requires matching both wavenumber and angular frequency: and for a sum interaction, with corresponding sign changes for differences. A common phase velocity alone does not guarantee that a generated harmonic lies on the dispersion relation.
A fundamental wave and its second harmonic satisfy phase matching for a quadratic wave interaction when . The square of the fundamental drives the second harmonic, while its product with the conjugate second harmonic drives the fundamental. Projecting these terms onto the resonant modes gives coupled amplitude equations rather than a uniformly valid correction at fixed amplitude.
For and , write , and . The polar equations areWhere the polar phases are defined, direct differentiation gives the first integrals and . In particular and are constant. If and , then , a Riccati equation whose positive solution develops a finite-time pole. This is finite-time blowup of the reduced amplitude system; it does not establish blowup of the full wave equation beyond the domain of the weakly nonlinear expansion.
Harmonic balance substitutes a finite Fourier series into a differential equation and projects the residual onto the retained harmonics. It determines their amplitudes and phases. A nonlinear equation generally generates additional harmonics, so vanishing of the projected residual alone does not make the finite series an exact solution. In a weakly nonlinear expansion, nonresonant generated harmonics can be found at the next order by solving their linear equations.
A solvability condition in the method of multiple scales is the compatibility requirement allowing a bounded periodic correction at a given perturbation order. Forwith -periodic in the fast variable, the Fredholm solvability condition for a self-adjoint operator requiresNecessity follows by integration by parts against the two periodic homogeneous solutions. For smooth periodic , sufficiency follows by Fourier series: all coefficients outside modes can be divided by . The forbidden modes would instead generate linearly growing secular terms.
The forcing contains slow derivatives of lower-order amplitudes, so these two conditions become amplitude-phase equations. For a general non-self-adjoint operator, project onto its adjoint null space instead of assuming the same homogeneous modes work.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §5.1.2, sine/cosine orthogonality conditions; §5.3, Proposition5.4 and averaged compatibility
Parametric resonance is growth caused by periodic variation of a system coefficient, rather than an additive forcing term. In the Mathieu equationthe stiffness varies near twice the natural angular frequency. Put and . The order- correction has resonant coefficients in the cosine component and in the sine component. Eliminating them givesThe slow eigenvalues are , so an initial component in the growing direction is amplified as at leading order. The exactly zero solution remains zero. Detuning competes with this coupling and produces an instability tongue, while Floquet theory gives the exact periodic-coefficient stability criterion. A weak-parameter growth approximation needs a stated time interval and can fail once neglected nonlinearities become important.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. §5.2, parametrically forced Mathieu oscillator
An instability tongue is a tongue-shaped region in parameter space where a periodically forced linear system has an exponentially growing mode. In the Mathieu equationFloquet theory detects instability through a Floquet multiplier of modulus greater than one. The exactly zero solution remains zero, and initial data on a decaying mode need not grow.
Near the principal resonance with small , multiple-scale analysis gives the leading growth rateIt is real and nonzero inside the leading region . The exact boundary has corrections beyond this approximation. The width therefore opens from zero at the resonance point, giving the tongue shape.
Unlike additive resonance, the drive here changes a coefficient of the equation. Detuning competes with that parametric coupling; damping and nonlinear saturation can further change the instability region and long-time behavior.[ref]
Asymptotic Analysis and Singular Perturbation Theory by John K. Hunter. Section5.2, parametrically forced Mathieu oscillator and detuning
For , use the method of multiple scales with and . Removing secular terms gives and . The slow eigenvalues satisfy , so an exponentially growing mode exists inside the displayed leading instability interval. At its leading endpoints the slow matrix is nilpotent; higher-order corrections are needed to determine the exact edges. Floquet theory distinguishes this exponential instability from algebraic growth at a repeated multiplier.
For weak quadratic coupling between frequencies one and two, the first oscillator's complex amplitude can obey with a constant real second-oscillator amplitude . In real coordinates this is a linear slow system with squared growth rate . Exponential amplification occurs when the modulation amplitude exceeds detuning, . The method of multiple scales is valid over bounded slow time while the physical amplitudes remain in the weak-coupling regime. At equality the slow matrix can have a Jordan block and produce linear growth for some initial phases.
For , the second parametric-instability tongue is to leading order. Outside its closure every leading slow amplitude is oscillatory.
For , let and . First-order forcing produces a constant and second harmonics, not a resonant harmonic. Their feedback at second order gives the displayed solvability condition in the method of multiple scales. The slow squared growth rate is . Consequently the leading instability interval is ; outside its closure the slow amplitudes oscillate. The endpoints are degenerate and require the fourth-order edges of the second Mathieu instability tongue for exact small-parameter stability.
For , set . The Mathieu equation has and . Near the value , the orthonormal even Fourier series basis gives diagonal entries and adjacent couplings . The odd basis gives diagonal entries and adjacent couplings . Higher modes require at least six coupling steps to affect the root near , so these truncations determine its coefficients through .
Substituting into the two characteristic polynomials and equating coefficients yieldsConverting back gives the displayed gap edges with remainders in . In a fixed bounded neighborhood of this parametric resonance, the true unstable gap is . The leading slow-amplitude calculation cannot decide exact stability at or ; the fourth-order shifts put those fixed values just outside the gap for sufficiently small positive . This does not provide a bound uniform in for their transient amplification.
Articles by others on the same topic



Singular perturbation refers to a situation in mathematical analysis, particularly in the study of differential equations, where a small parameter multiplies the highest derivative in the equation. This small parameter can lead to significant changes in the behavior of the solution, resulting in phenomena that cannot be understood by analyzing the equation without this parameter. In this context, singular perturbations typically give rise to boundary layers — regions where the solution changes rapidly compared to other regions.