A scalar linear differential equation of order has the formHere the coefficients and the forcing term are prescribed functions of the independent variable . A classical solution of a differential equation is an -times differentiable function satisfying the identity at every point of its interval. The unknown function and its derivatives enter to the first power, without products between them or coefficients depending on . Equivalently, the differential operator is a linear map: for constant scalars ,The forcing term may be zero, giving a homogeneous linear differential equation, or nonzero, giving an inhomogeneous linear differential equation. Linearity of does not mean that every function graph of a solution of a differential equation is a straight line.
To use the usual order- initial value problem theory on an interval , assume that throughout and that all and are continuous functions there. Dividing by normalizes the highest derivative; specifying at then selects one solution of a differential equation throughout . A zero of needs separate analysis: one cannot divide through it and retain these conclusions. The first-order normalization appears in OpenStax's definition and standard form of linear equations; the corresponding system theorem is in MIT's existence and uniqueness notes for linear systems.
The coefficients need not be linear functions of . For example, is a linear differential equation on , although is quadratic. Its solution of a differential equation with initial condition is : its derivative is , so substitution gives , and . The zero of the highest coefficient at explains the domain restriction. In contrast, , and are nonlinear ordinary differential equations because of their dependence on the unknown function. Variable coefficients and nonlinear ordinary differential equations are different issues; see MIT's definitions and examples of first-order linear equations.
The practical benefit of linearity is that it separates the effect of the initial condition from the effect of the forcing term. Once one particular solution satisfies , every solution of a differential equation isHere is the kernel of a linear map, consisting of solutions of a differential equation to the associated homogeneous linear differential equation. Indeed, , and conversely . Thus the family for a fixed forcing term is an affine space obtained by translating . If is not identically zero, the zero function is absent, so this family is not a vector space under the usual operations on functions. This short argument explains why a general solution is a particular solution plus a homogeneous solution.
A vanishing highest-derivative coefficient can make the two initial values of a second-order differential equation dependent. Suppose is continuous at zero, is constant, and a solution of has finite continuous at zero. Integration givesRegularity forces . Dividing by and taking the limit gives , since the integral average tends to . The remaining equation is first order and therefore has only one free regular initial value. For and , it yields and . This explains the reduced constant count without treating the singular endpoint as an ordinary second-order initial point.
In a fixed frame, a first-order linear differential equation is Fuchsian at a finite point when its coefficient matrix has at most a simple pole there. Its residue is . The global object is the matrix-valued one-form : in the coordinate its coefficient is . A Fuchsian system has intrinsic regular singular points, but an intrinsically regular singular system may have higher-order coefficient poles in a different meromorphic frame.
Suppose the matrix is holomorphic at zero and is an eigenvalue of . Let be the largest nonnegative integer for which is an eigenvalue of . Seek , with nonzero. The Frobenius method gives for , where scalar terms multiply the identity. Every left-hand matrix is invertible by the choice of . Its inverse is , so a scalar convergent majorant proves convergence of the series. This yields a nonzero analytic solution; it is necessarily nonconstant when , but can be constant when . For the displayed sign convention, indicial exponents are eigenvalues of .
A fundamental matrix for on a chosen logarithm branch is . A counterclockwise circuit changes the logarithm by , giving the displayed monodromy matrix and the cyclic group it generates. Changing the solution basis conjugates the matrix. The residue eigenvalues exponentiate to the monodromy eigenvalues; the latter do not determine the former uniquely.
For a system of linear differential equations , a fundamental matrix has columns forming a basis of its solution space. It solves and is invertible at every time in its interval. Every solution is for a constant vector : differentiating gives zero. Invertibility at one time implies invertibility throughout the interval by uniqueness of the initial value problem. This notion is distinct from a Markov-chain fundamental matrix or the projective-geometric matrix used in stereo vision.
Writing with an invertible matrix-valued function gives exactly when . For a formal power series transformation at an irregular singular point, coefficient comparison recursively removes off-diagonal terms when leading diagonal eigenvalues are distinct. This is a differential-system change of frame, not specifically an electromagnetic gauge transformation.
For , , the formal diagonal exponent has and . Matching the gauge equation gives the off-diagonal first coefficient and the diagonal one , where . The second coefficient has diagonal entries and off-diagonal entries . With and negative-index coefficients zero, the coefficient comparison isIts diagonal equations at give and the second diagonal coefficient respectively. Its off-diagonal equations determine the next coefficients because the commutator with multiplies the upper and lower entries by and . This proves the expansion and supplies the recursion for all higher orders. The generally nonzero supplies formal monodromy.
If and , differentiation of the determinant gives . For a planar periodic orbit this gives the nontrivial Floquet multiplier, since the tangent multiplier is one.
For a continuous periodic coefficient matrix , a fundamental matrix for , normalized by , obeys . The invertible matrix has a complex matrix logarithm; set and . Since commutes with , direct substitution gives and proves the factorization. A real logarithm is not required for this complex representation.
The eigenvalues of are Floquet multipliers. All solutions are bounded for forward time when every multiplier has modulus at most one and those on the unit circle have no nontrivial Jordan blocks. In a real undamped second-order scalar equation with no first-derivative term, the monodromy determinant is one. Distinct conjugate unit-modulus multipliers give bounded solutions; a nontrivial Jordan block at multiplier or gives an unbounded second solution even when one periodic or antiperiodic solution exists.
For a Floquet multiplier of a period- linear variational equation, a Floquet exponent is any logarithmic rate satisfying the displayed relation. Its real part is uniquely , while its imaginary part is defined modulo . Negative transverse real parts give local attraction to a periodic orbit; the autonomous phase direction has multiplier one and exponent zero. Constant-coefficient amplitude equations supply exponents directly as the eigenvalues of their Jacobian matrix.
The Floquet growth rate measures the exponential trend of a periodic linear differential equation over many coefficient periods. A Floquet multiplier measures the factor per period ; the corresponding rate per unit time iswhere is a Floquet exponent. Taking the real part removes the ambiguity in the complex logarithm.
For the scalar example under periodic solution, and the Floquet growth rate is , independently of . Indeed,The instantaneous logarithmic derivative keeps oscillating even though its average over complete periods is exactly . Sampling at the same phase in each period removes the modulation altogether: .
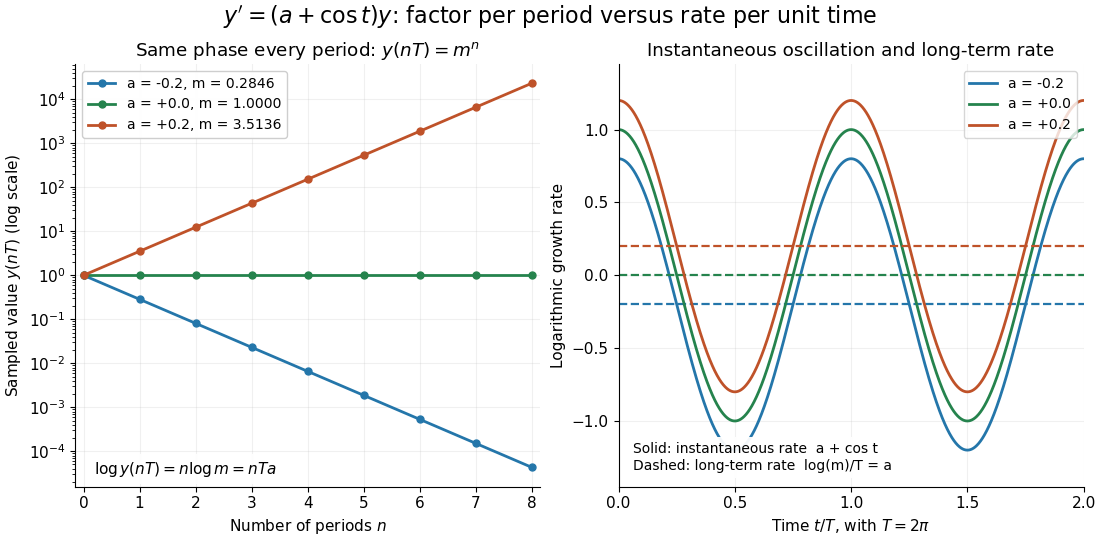
For the general finite-dimensional homogeneous linear differential equation , assume that is continuous on the real line and -periodic, with . Normalize its fundamental matrix by and set . The maximal asymptotic exponential rate, using any induced matrix norm, isHere is the spectral radius, are the Floquet multipliers, and invertibility gives . This concerns growth of the solution operator; it does not say that every initial condition attains the maximum.[ref]
To prove the formula, write with . Periodicity and uniqueness giveBoth and have uniformly bounded matrix norms on a period. Consequently differs from by at most fixed multiplicative factors. The spectral radius formula gives , proving the claimed limit without choosing a matrix logarithm.
For a particular nonzero initial condition , decompose into the generalized eigenspaces of over the complex numbers. The rate of is the largest among components that are nonzero. Generic data have a component in the dominant generalized eigenspaces and attain ; data contained in the sum of the subdominant generalized eigenspaces have a smaller rate. For example, with , the maximal rate is , while decays at rate . These invariant subspaces describe initial data at phase zero. Their transported versions can vary with time and satisfy .
A negative Floquet growth rate allows temporary amplification. For the constant non-normal matrixthe initial condition has Euclidean norm , which rises from to about at before eventually decaying. Its exponential rate is still : the Jordan block contributes a polynomial factor, whose logarithm divided by tends to zero. At a unit-modulus Floquet multiplier, such polynomial growth can even be unbounded with zero exponential rate; gives . Thus zero Floquet growth rate alone proves neither boundedness nor a periodic solution.
For the homogeneous linear differential equation with continuous coefficient matrix of period , the monodromy matrix of a periodic linear system is the one-period map from to . If is any fundamental matrix,Its eigenvalues are the Floquet multipliers. Multipliers are nonzero, since a fundamental matrix is invertible. Changing the starting phase conjugates , so the Floquet multipliers and Jordan blocks are independent of that choice.[ref]
This turns a continuous-time problem into repeated matrix multiplication:If , the associated solution of a differential equation obeys at every time, not merely at the sampled times. In particular, gives a nonzero -periodic solution, and every nonzero -periodic solution arises this way. If , the state changes sign after one period and repeats after two. A unit-modulus Floquet multiplier different from need not give repetition after one period, and a generalized eigenvector in a nontrivial Jordan block need not even give bounded motion.
For the scalar example under periodic solution, is the one-by-one matrix . Numerically solving a matrix problem uses the same idea: integrate one initial value problem for each column of through one period, then compute the eigenvalues of . This is useful when an explicit solution of a differential equation is unavailable: one period determines the Floquet growth rate over arbitrarily many periods.
For piecewise constant coefficients, which are also covered by the one-period construction, is the time-ordered product of the segment matrix exponentials, with the earliest segment on the right. For example, take period and alternateSince ,Replacing the coefficient by its mean would instead give and the incorrect rate . The matrices do not commute. The scalar mean-coefficient formula therefore cannot simply be transferred to matrix systems. Nevertheless the Liouville formula for a fundamental matrix gives the correct determinant even in the noncommuting case:In the example, this is ; it fixes the product of the Floquet multipliers, rather than either multiplier separately.
In Sur les équations différentielles linéaires à coefficients périodiques (1883), Gaston Floquet calls a function satisfying periodic of the second kind, and distinguishes the genuinely periodic function obtained when . This historical terminology captures precisely the difference between repetition of the coefficient and repetition of the state.[ref]
Sur les équations différentielles linéaires à coefficients périodiques by Gaston Floquet (1883). Printed p. 48, definition of a function periodic of the second kind and its multiplier; p. 49, transformation of a fundamental solution system after one period
For the homogeneous linear differential equation , a characteristic root is a root of a polynomial . A simple root supplies an exponential solution ; a root of multiplicity supplies for . The sign of the real part of determines spatial growth or decay.
The Laplace contour-integral method seeks a solution in the formReplacing multiplication by with differentiation of in and integrating by parts turns the differential equation for into a first-order equation for . The contour must make the resulting endpoint term vanish; finite endpoints are often branch points of , while infinite ends must enter sectors where the exponential decays.
A homogeneous linear differential equation is a linear differential equation with identically zero forcing term, . On a common interval, its solutions of a differential equation form the vector space , the kernel of a linear map. They include the zero function and are closed under addition and scalar multiplication. For any two solutions of a differential equation and constant scalars , linearity gives : this is the superposition principle. The scalars must be constant; variable multipliers introduce extra derivatives.
For example, has general solution , where is any constant real number. A short verification uses the product rule: , so is constant. For and , the sum is and also solves the same homogeneous linear differential equation. At , their values are approximately , and . Every curve is a multiple of one exponential function; the solution space of a homogeneous linear differential equation has dimension one. Both and in this example and the following diagram are dimensionless mathematical variables.
Now keep the same differential operator but prescribe the forcing term . The inhomogeneous linear differential equation has particular solution and general solution . The initial conditions select, respectively,At , their values are approximately , and . The midpoint solves the same inhomogeneous linear differential equation, because . The sum instead satisfies , so it fails the equation with forcing term . More generally, a linear combination of solutions of a differential equation for the same fixed nonzero forcing term retains that forcing term precisely when its scalar weights add to one. This is the affine space structure, rather than unrestricted superposition within that fixed family.
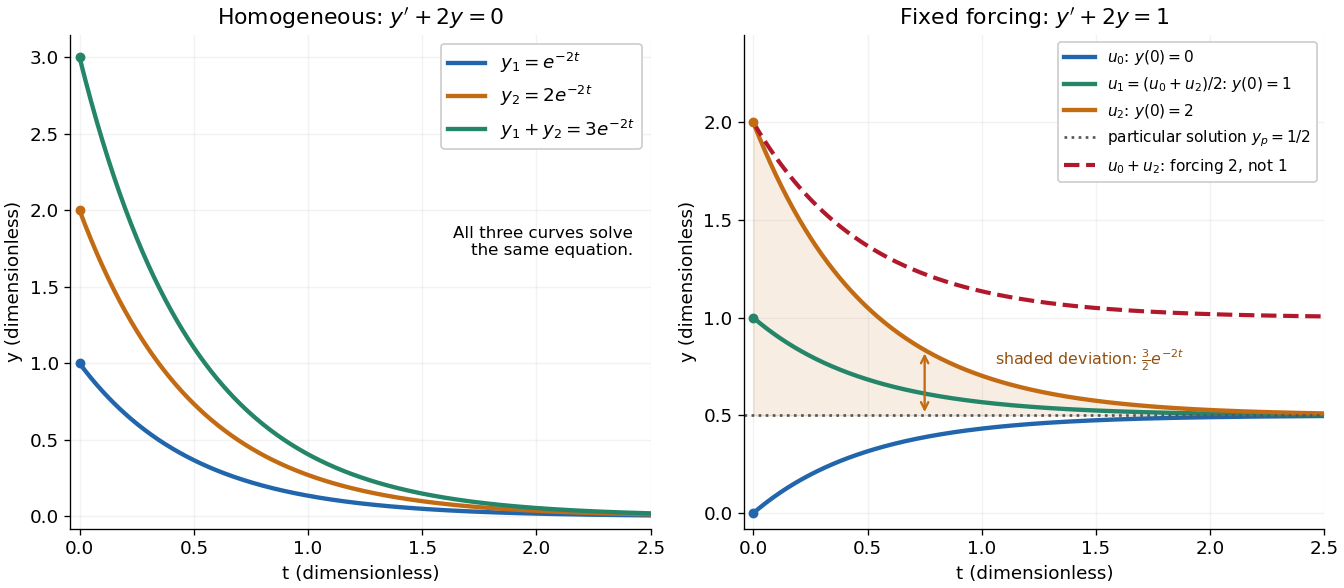
Homogeneous solutions obey superposition, while a fixed forcing term gives a particular solution plus homogeneous solutions
. Details. On the left, all three curves solve the same homogeneous linear differential equation. On the right, share the particular solution , and the shaded difference is the homogeneous solution . The dashed sum has twice the forcing term, even though its starting value coincides with that of . Adding the two initial conditions also adds their inputs; taking their midpoint averages both. This distinction makes the superposition principle useful for assembling responses to different inputs without mistaking that assembly for a solution of a differential equation with the original input. See MIT's superposition notes, including the particular solution one half.
The solutions of a homogeneous linear differential equation on a common domain form a vector space. For a regular scalar equation of order , prescribing the first initial data at an ordinary point gives an isomorphism of this solution space with the scalar field to the power .
A linearized equation retains terms first order in a perturbation about a reference solution. Its coefficients are determined by derivatives of the original nonlinear equation evaluated on that reference solution.
An inhomogeneous linear differential equation has a nonzero forcing term. Its general solution is one particular solution plus the general solution of the associated homogeneous linear differential equation.
For a linear differential equation written , the prescribed right-hand side is the forcing term. It may represent an external input or source, and can be constant or time dependent. Setting gives the associated homogeneous linear differential equation.
Articles by others on the same topic



The name is a bit obscure if you don't think in very generalized terms right out of the gate. It refers to a linear polynomial of multiple variables, which by definition must have the super simple form of:and then we just put the unknown and each derivative into that simple polynomial:except that now the are not just constants, but they can also depend on the argument (but not on or its derivatives).
Explicit solutions exist for the very specific cases of:
- constant coefficients, any degree. These were known for a long time, and are were studied when Ciro was at university in the University of São Paulo.
- degree 1 and any coefficient