Optimization of a linear function subject to affine constraints and membership in a closed convex cone. Choosing the positive semidefinite cone gives semidefinite programming; other choices include copositive optimization and completely positive optimization. Dual cones produce scalar-product bounds on feasible objectives.
For a real matrix and a vector , exactly one of the following systems has a solution:The linear inequalities here are componentwise. In the first system is nonnegative; in the second system is unrestricted in sign. The second system is a certificate that the first has no feasible point. This nonnegative-equations alternative is developed in Boyd and Vandenberghe, Convex Optimization slides, §5.34.
Build the target, or separate it. Write the columns of as . Then is a conic combination: its coefficients must be nonnegative, but need not sum to one. The obtainable targets form the finitely generated coneA solution explains how to build from those columns. A certificate instead defines a linear functional . The condition says that its dot product with every generating column is nonnegative, and hence with every point of . But places the target strictly on the other side of the hyperplane . Thus belongs to the dual cone of and rules out every allowed conic combination at once.
A certificate that can be checked by eye. Take the identity matrixHere is the nonnegative orthant. The equation forces , violating . The certificate givesThe linear functional simply reads the first coordinate: all allowed column combinations have a nonnegative first coordinate, while has first coordinate . For comparison, the target is obtained with .
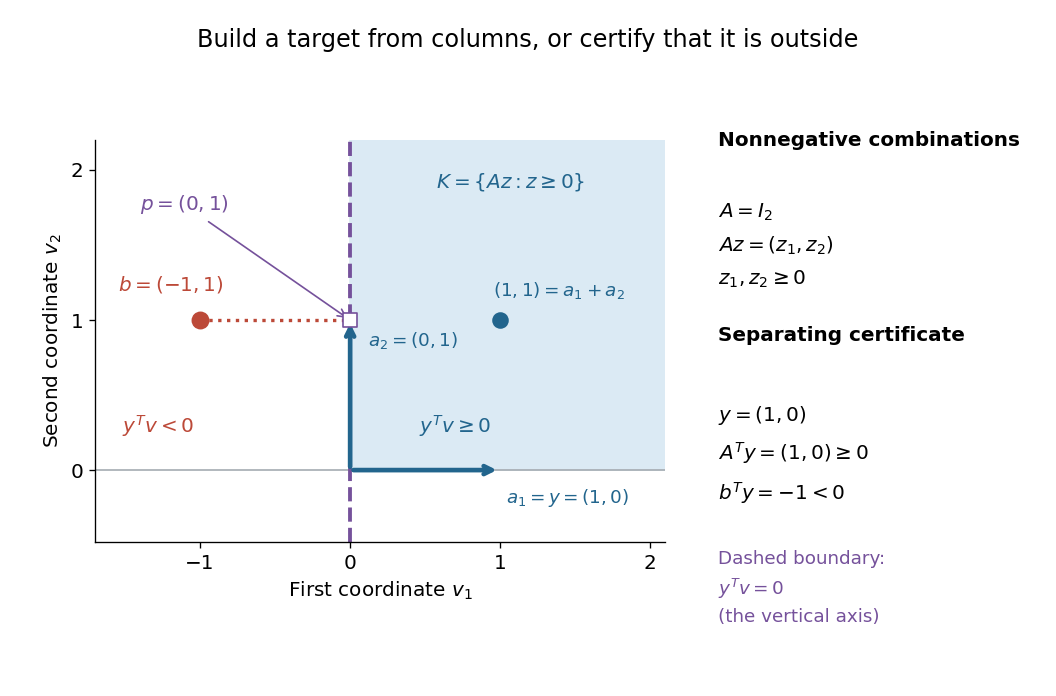

Why this is useful and striking. A successful search can exhibit one feasible point; an unsuccessful search alone cannot explain why every candidate fails. Farkas' lemma guarantees an equally concrete witness of impossibility for this finite linear problem. Once is supplied, verification needs only matrix multiplication, sign tests and one dot product. The same idea gives a Farkas certificate for linear inequalities and underlies linear programming duality.
Brief geometric proof. The two systems cannot both hold, because they would implyFor existence of a certificate when , closedness of finitely generated cones makes a closed convex cone, so separation from a closed convex cone supplies and for every . Testing each column gives . Concretely, let be the Euclidean projection onto a convex set of onto and set . The projection inequality gives for . Testing and gives , whence . In the example, and . Alternatively, the Fenchel-Moreau theorem applied to the cone's indicator functional proves the same separation through its polar cone.
An original historical source is Julius Farkas's [ref]
https://geodesic.mathdoc.fr/item/JRAM_1902__124_149129/. Theorie der einfachen Ungleichungen, Journal für die reine und angewandte Mathematik 124 (1902), pp. 1–27
. The linked archival record verifies the author, title and publication details.Suppose a linear program has a Farkas' lemma certificate , , . A purported feasible point of , would imply . Hence every relaxation below the displayed positive threshold remains infeasible. For rational inputs, bounds on the encoding length of a certificate supply the precision gap used by the ellipsoid method.
Let and . For unrestricted , the system of linear inequalities has no feasible point if and only if there is a vector withThe entries are nonnegative Lagrange multipliers for the rows. Multiplying inequalities by them preserves their direction; the condition cancels every variable, leaving the contradictionThis is a Farkas' lemma alternative for non-strict inequalities; no strict-feasibility assumption is needed. See Boyd and Vandenberghe, Convex Optimization (2004), §5.8.3, pp. 261–262.
Three individually possible requirements, jointly impossible. Suppose two unrestricted real coordinates , drawn as in the diagram, must satisfyWrite every row in the same direction:Then and . The nonnegative weighted sum, with Lagrange multipliers , is visiblyEach individual requirement defines a half-space in the plane. Even every pair has a feasible point: satisfies the first two, the first and third, and the second and third. Their common intersection is empty, because the first two force , while the third demands at most .
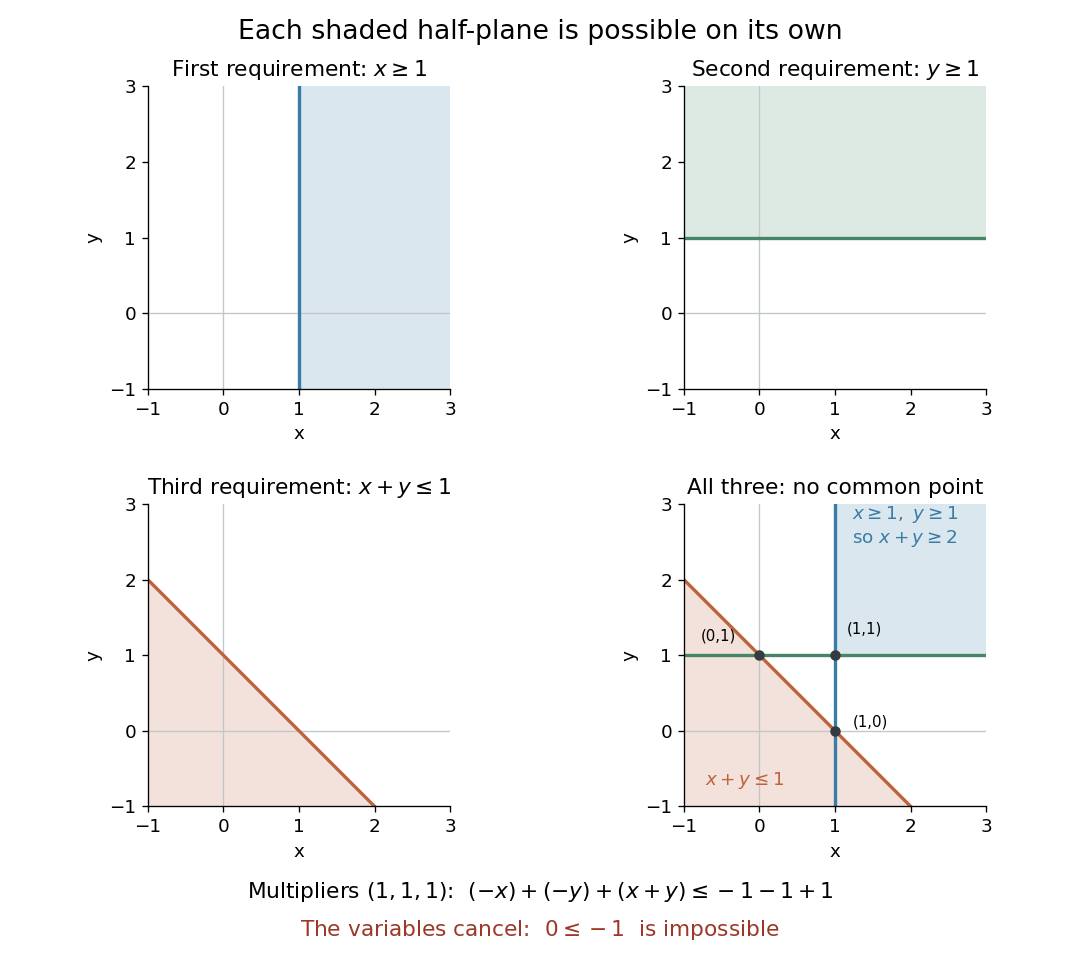

Why cancellation is necessary for unrestricted variables. A nonzero linear functional can be made arbitrarily positive or negative by varying unrestricted , so alone would not yield a contradiction. Equality is essential here. If is also imposed, the sufficient certificate becomes , , , because then . This is the sign convention used in robust infeasibility under uniform constraint relaxation. One can instead append the rows and use the equality certificate on the enlarged system. Reversing all constraints to reverses the scalar sign to , as in the normalized integer Farkas infeasibility gap.
Checking a solver's infeasibility claim. A returned Farkas certificate for linear inequalities gives a short verification procedure: compute and , and check the three displayed conditions against the original constraints. Any positive multiple is another certificate; division by normalizes to . With rational numbers as data and certificate, the tests can be exact. With floating-point arithmetic, a small residual is a diagnostic rather than an exact cancellation: unrestricted can amplify a nonzero residual without bound. A rigorous certificate therefore needs exact cancellation or justified error bounds and additional bounds on the variables. The strict negative scalar is the margin of contradiction.
The same weighted sums give dual bounds. For the linear program maximizing over unrestricted with , any satisfying givesfor every feasible point. Minimizing over these multipliers is the dual linear program; the bound itself is weak duality. For example, maximize subject to , , . The multipliers give the upper bound , attained at . The infeasibility example above uses the same row directions, but lower bounds of on both coordinates. Its multipliers cancel the objective function as well as the variables: with would bound zero by a negative number. Thus impossibility and linear programming optimality certificates use the same arithmetic. See Boyd and Vandenberghe, Convex Optimization slides, §§5.32–5.35 for infeasibility as a dual alternative.
Why every inconsistent system has such a certificate. Introduce a slack variable vector and write . Split the unrestricted vector as with . Applying Farkas' lemma to the column matrix gives , , and . The first two conditions together are exactly . This reduction explains both the equality and the nonnegative row multipliers.
Suppose have integer entries of absolute value at most , has columns, and is infeasible. A Farkas certificate for linear inequalities can be chosen with , , and the displayed lower bound. Normalize an infeasibility certificate to obtain the last equality, then maximize over the resulting compact linear polyhedron. A maximizing extreme point has at most positive entries: otherwise the augmented columns on its support would be dependent, allowing feasible perturbations in both directions. For its independent supported columns, select independent equations. Cramer's rule expresses the supported entries with a common nonzero integer determinant denominator. That determinant has absolute value at most . The positive value therefore has a positive integer numerator over a denominator of at most this size, proving the bound.
An interior-point method solves constrained mathematical optimization problems by maintaining variables in the interiors of their feasible cones or inequality domains. Barrier derivatives are defined there, and damped Newton methods keep subsequent iterates in their domains. A central path gives a family of barrier-regularized optima whose duality gap approaches zero; a conic phase-I problem can supply a strict feasible starting point.
A barrier function penalizes approaching the boundary of a feasible set from its interior, typically diverging to there. An interior-point method minimizes the original objective function plus a positive multiple of this penalty, then reduces that multiple. The logarithmic barrier is the basic example for smooth inequality optimization constraints.
For optimization constraints and , the logarithmic barrier objective is on . Its derivatives are defined only on this strictly feasible open subset. One may extend its value to off to formulate an extended-real convex function. The penalty alone is , while includes the original objective function.
When is convex and each is concave, is a convex set andEvery term of this Hessian matrix is a positive semidefinite matrix, so is convex. Its critical point satisfies the stationarity part of the Karush-Kuhn-Tucker conditions with estimates and perturbed complementary slackness .
Let be concave and continuously differentiable, and let a strict feasible point satisfy . Suppose , , , and the logarithmic barrier residuals tend to zero, where . By concavity,The right-hand side is bounded when is continuous near . Thus the nonnegative Lagrange multiplier estimates are bounded. A convergent subsequence gives ; passing to the limit in stationarity and proves the Karush-Kuhn-Tucker conditions at . An inactive optimization constraint has and hence even without selecting a subsequence. With a convex objective function, these conditions certify a global minimum. This result is conditional on the stated residual and primal convergence assumptions; it does not assert that every barrier subproblem has a minimizer.
Near an active constraint with limiting Lagrange multiplier , a convergent barrier sequence has . Its Hessian matrix therefore contains the termFor a nonzero constraint gradient, this gives large curvature in a direction normal to the boundary. If a nonzero common tangent direction retains positive curvature of order one, while the remaining terms stay bounded, the condition number typically grows like . This is a mechanism rather than a universal rate: there may be no tangent direction, all curvatures may grow together, or an active constraint may have zero limiting Lagrange multiplier.
For a linear program and its dual linear program, write , , , and . Introduce , , and a free multiplier satisfyingThe point , , is strictly positive in all constrained coordinates. Multiplying the first three equations by respectively and adding gives the displayed identity. Minimizing has value zero: primal-dual optimal solutions or certificates from Farkas' lemma give zero- solutions after selecting positive and scaling. At , gives an optimal primal-dual pair by division by , while gives a primal infeasibility or dual infeasibility certificate. A point with is not decisive; choosing a relative interior point of the optimal face of a linear program avoids that degeneracy because the face contains a point with .
An auxiliary conic optimization problem searches for strict feasibility before following a central path. Given , minimizing subject to and has a strict feasible start for sufficiently large . Any feasible solution with certifies . If the original problem is strictly feasible, a small negative is feasible. Equality constraints and dual feasibility require their corresponding auxiliary procedures.
A convex three-times differentiable barrier is self-concordant whenA barrier of parameter additionally satisfies and diverges at the domain boundary. Logarithmically homogeneous cone barriers satisfy . The orthant barrier has parameter equal to the dimension, while the Lorentz-cone barrier on has parameter two. Their Hessians define Dikin ellipsoids and control interior Newton steps.
A cone barrier with this scaling law satisfies and . Therefore a central path with has primal-dual gap . A product of orthant and Lorentz cone canonical barriers adds their parameters.
For a logarithmically homogeneous barrier on a proper cone, the convex conjugate with reversed argument defines a barrier on the interior dual cone. The inverse gradient relation makes equivalent to . This gives a joint primal-dual central path without assuming the barrier is identical on a self-dual cone.
For a nondegenerate self-concordant barrier, the open local Hessian ballis contained in its barrier domain. This is the Dikin ellipsoid. It supplies a quantitative way to ensure that a damped Newton method stays interior, without relying on Euclidean distance to a possibly curved boundary.
For a strictly feasible primal-dual conic optimization problem and a logarithmically homogeneous barrier, the central path consists of solutionsThe primal-dual gap is . Existence requires appropriate feasibility and boundedness hypotheses, rather than merely a full-rank constraint matrix. Linearizing these equations gives a central-path Newton system.
At a target barrier parameter , let , , . The Newton direction solvesFull column rank of and a positive-definite barrier Hessian give a positive-definite reduced matrix. Backtracking must keep both cone variables interior; solving the linear equations alone does not guarantee that a full step stays inside the cones.
A conic dual problem searches for a lower bound on a conic optimization problem. A feasible point exhibits an attainable cost; a feasible dual variable explains why every allowed decision costs at least a specified amount. If the two costs agree, the pair certifies a global minimum without relying on how the points were found.
Fix a real matrix , vectors , , and a closed convex cone . With unrestricted , use the conventionwhere the dual cone is . The conic dual problem uses because it must turn every allowed slack variable into a nonnegative dot product. Taking gives componentwise linear inequalities; taking a second-order cone gives a Euclidean norm constraint. A self-dual cone has , but this equality does not guarantee a feasible point or strong duality.
The Lagrangian supplies a short derivation. For ,Its infimum over unrestricted is when , and otherwise. Maximizing the resulting Lagrange dual function gives the stated conic dual problem. The minus sign matches the convention .
Consider the original linear programOne unit of costs twice as much as one unit of , so is a plausible answer. To certify it, multiply the three linear inequalities by , respectively, and add:The proposed feasible point attains , so its cost is the global minimum.
In the conic dual problem convention, the data and certificate areDirect matrix multiplication gives and . At , the slack variable is , so . The first linear inequality has positive slack and zero multiplier; the two positively weighted linear inequalities are tight. This is complementary slackness.
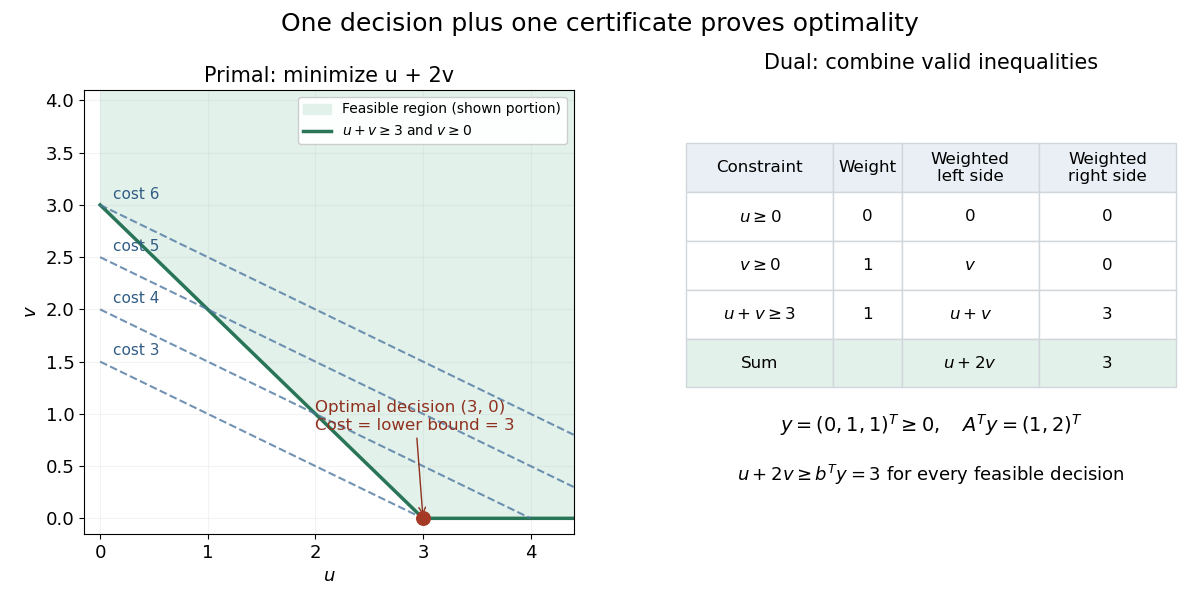

The entire dual feasible set can also be read off: write with . Then and . Maximizing this lower bound gives . A point such as is still a valid certificate of the weaker bound .
A curved feasible set can have the same certificate structure. ConsiderWrite and use the second-order cone . In this coordinate ordering,Self-duality of a second-order cone makes . The equality forces and , leaving . Its dual objective function is , maximized at . Thus every feasible point satisfies , and attains that bound: .
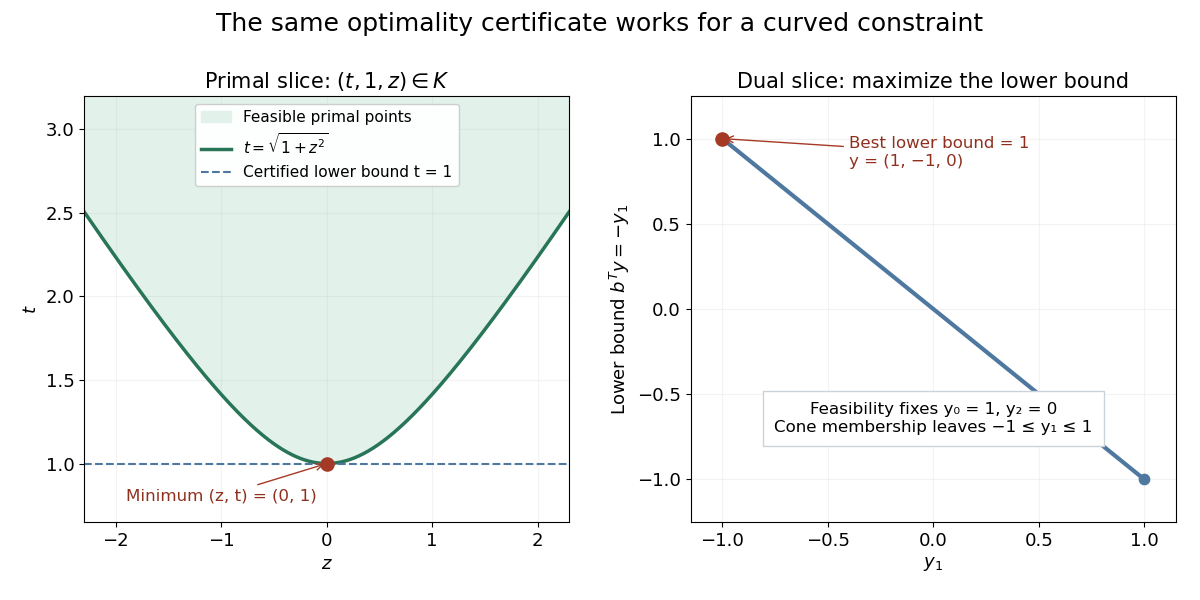
A curved primal constraint and an interval of dual certificates
. The left panel is the slice of the second-order cone, so its boundary is . The right panel is the dual slice , : admissible form , and reaches at . The optimal slack variable and dual variable lie on different cone boundary rays with zero dot product. Details.
The zero dot product is . Individual coordinate products need not be nonnegative here: the cancellation occurs across coordinates. The valid complementary slackness condition is cone-level orthogonality, rather than the coordinatewise interpretation of the nonnegative orthant.
For a feasible point and a feasible dual variable , weak duality follows from one identity:The inequality is the defining property of the dual cone. Every feasible pair therefore encloses the optimal objective function value:Both optima are finite when such a pair exists. Consequently,These are absolute cost bounds, rather than bounds on distance to an optimizing vector. Zero gap certifies both optima immediately. A small positive gap bounds the remaining improvement even if no strong duality theorem has been invoked.
For the nonnegative-orthant optimality certificate example, is feasible and costs . Pairing it with gives , so its cost exceeds the optimum by at most . Here the optimum is known to be , and the bound is exact. Pairing the same with the weaker certificate gives : a valid but less informative guarantee.
The identity assumes exact primal and dual feasibility. With a dual linear-system residual , it becomesThe second term has no guaranteed sign. Checking only a small linear-system residual and the cone dot product is insufficient when is large; a separate bound follows from the Cauchy-Schwarz inequality. Approximate cone membership likewise needs a quantified correction before claiming a certificate.
For an exact arithmetic example, minimize subject to . The point is optimal. A proposed multiplier is nonnegative and gives zero cone dot product because the slack is zero, but violates by . Its purported lower bound is , exceeding the optimum. The missing term explains the failure.
For a proper cone , suppose a point satisfies and is finite. This generalized Slater condition gives strong duality and attainment of the conic dual problem's optimum. It does not by itself assert primal attainment.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §5.9.1, printed p. 265: generalized Slater condition, strong duality and dual attainment
The two worked examples have strict primal points: has slack in the interior of the nonnegative orthant, and has slack in the interior of the second-order cone. Both optima were already certified by explicit feasible pairs. Slater's condition explains why a matching optimal dual variable can be expected under these hypotheses; checking a supplied zero-gap pair needs only weak duality.
Changing cone geometry preserves the bound mechanism. For a positive semidefinite cone, the dual cone pairing is the Frobenius inner product of two matrices. This connects the same certificate idea to semidefinite programming, while the central path uses strictly interior primal and dual points to approach vanishing gap.
In 1995, Lieven Vandenberghe and Stephen Boyd presented a primal-dual interior-point method for convex optimization with matrix inequalities. Their algorithmic study included exploiting problem structure and allowing incomplete Conjugate gradient method solves within an iteration. This illustrates how the primal-dual viewpoint guides computation as well as checking a final answer.[ref]
A Primal-Dual Potential Reduction Method for Problems Involving Matrix Inequalities by Lieven Vandenberghe and Stephen Boyd. Publication record and authored abstract: A Primal-Dual Potential Reduction Method for Problems Involving Matrix Inequalities, Mathematical Programming, Series B, 69(1), 205–236 (1995)
Conic optimization using the completely positive cone. For a real symmetric matrix , the trace-normalized program minimizes a weighted average of nonnegative-unit-vector Rayleigh quotients. The weights are the squared norms of the factors in . Hence a minimizing rank-one factor attains the same value as the original orthant minimum.
Conic optimization using the copositive cone. The constraint supplies an exact reformulation of a Rayleigh quotient minimum on the nonnegative orthant. Exact conic formulation does not itself provide an efficient membership algorithm.
Let for a real symmetric matrix . Compactness gives attainment. Homogeneity shows is a copositive matrix exactly when , provingIts conic program dual is the trace-normalized completely positive optimization problem. A minimizing vector gives , which certifies equality and dual attainment directly. In general differs from the unrestricted smallest eigenvalue.
Articles by others on the same topic
There are currently no matching articles.