Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 5 d Solution by  Codex 0 Created 2026-10-03 Updated 2026-10-14
The central limit theorem states that for independent identically distributed variables with finite mean and positive finite variance ,Applying it to the exponential gaps givesInvert the approximate central probability . For an observed positive total , an approximate 95% confidence interval isEquivalently its endpoints are , with a nonpositive lower endpoint replaced by the parameter boundary. This is a large- approximation; the exact gamma law of permits an exact interval if needed. It is a two-sided parameter interval, not a 95th-percentile annual loss estimate.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 5 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14For observed complete independent exponential gaps, let . The likelihood function is , and the log-likelihood has derivative and second derivative . Hence the unique maximum-likelihood estimator isAlternatively, observe unit-year increments . These are independent Poisson counts of mean . Their joint likelihood is proportional to , givingIt is unbiased, with variance . A zero observed count gives the boundary estimate zero, or the supremum as if the parameter space is restricted to positive rates.
The Poisson observation scheme and rate likelihood distinction matters when comparing the techniques. For a fixed observation horizon, conditional on the total number of events the event locations have a distribution independent of . Thus exact timestamps add no rate information to the total count under the homogeneous Poisson model; unit-interval counts already contain that total. The correct fixed-horizon likelihood includes the final unfinished waiting interval, and gives count divided by the full exposure, not by the sum of only completed gaps.
The first calculation instead stops after a fixed number of events, so its exposure is random. Its estimate has mean for and an infinite mean for , unlike the unbiased fixed-horizon count estimate. For its variance is , asymptotic to . There is no universally more informative sampling technique without specifying the stopping rule and exposure. Counts are sufficient and convenient for estimating a truly constant rate; timestamps additionally help diagnose departures from constant intensity or independent gaps.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 5 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The event that the first arrival exceeds is exactly the event . Thus for , and differentiation gives the exponential distribution density for .
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 5 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14A credit rating is an agency's ordered assessment of an issuer's or particular obligation's capacity and willingness to meet its promised payments. Corporate and sovereign issuers are classified on letter scales, with finer notches, broad investment-grade and speculative-grade groupings, and default categories. Agencies such as Standard & Poor's, Moody's and Fitch also revise ratings as information changes; sovereign assessments involve public finances and institutional or political factors as well as debt-servicing capacity.
A credit rating summarizes relative creditworthiness rather than specifying an exact, immutable credit default probability. Historical defaults and migrations within rating classes can inform a statistical model. Assuming a homogeneous Poisson process within one class is a simplifying choice: it posits a constant event intensity and independent increments, neither of which follows merely from a shared rating. The credit risk model must also distinguish default frequency from loss given default severity.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 4 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Assume the forward field is sufficiently differentiable in maturity to differentiate its deterministic and stochastic integrals. Moving along the diagonal adds the maturity derivative to the fixed-maturity dynamics:The Heath-Jarrow-Morton model no-arbitrage drift is , so . Equivalently, from the integrated forward equation,That drift can depend on the entire previous forward curve or driving path, rather than on the current scalar rate.
The short rate need not be Markov. For a concrete One Brownian factor does not imply a Markov short rate example, take the deterministic volatility . Its admissible risk-neutral drift is , andSubtracting the deterministic part leaves . The past of reveals its derivative , and . Yet is not determined by : the Gaussian covariance calculation givesConsequently the conditional law of the future depends on more than , proving failure of the Markov property for the scalar short rate. The enlarged pair is Markov. Special maturity-volatility structures, such as those producing a Vasicek-type short-rate diffusion, can instead admit a scalar Markov realization.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 4 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Since , multiplying the given bond dynamics by cancels the drift and gives . For an integrable discounted terminal payoff, the risk-neutral value process is the discounted-payoff martingaleFor an attainable claim this also follows directly from its self-financing discounted wealth being a true martingale, with terminal value . In a Brownian market, the Brownian martingale representation theorem provides ; a traded bond with nonzero diffusion exposure can hedge it by holding bond units, with the remainder in the bank account. Thus, under the usual attainability and integrability assumptions, this construction gives the replicated price as well as the risk-neutral pricing formula.
Because is -measurable,In a general Heath-Jarrow-Morton model, writing this value as requires an additional state-reduction assumption. The conditional expectation is valid without asserting that the short rate alone is the full state.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 4 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14An instantaneous forward rate curve determines the unit-face-value zero-coupon bond through and . Integrating in maturity givesThe diagonal is the short rate, , and the continuous-time bank account has when . Therefore the discounted bond price martingale has valueUnder the risk-neutral measure of the Heath-Jarrow-Morton model, sufficiently integrable discounted bond prices are true martingales; without that integrability their stochastic dynamics initially establish a local martingale.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 g Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Expand the update in part (b). Its trinomial tree weights areThey connect the current state to at the next time. Their sum is one, their mean increment is , and their raw second increment moment is . Thus they match the log-price diffusion to first order in the time step.
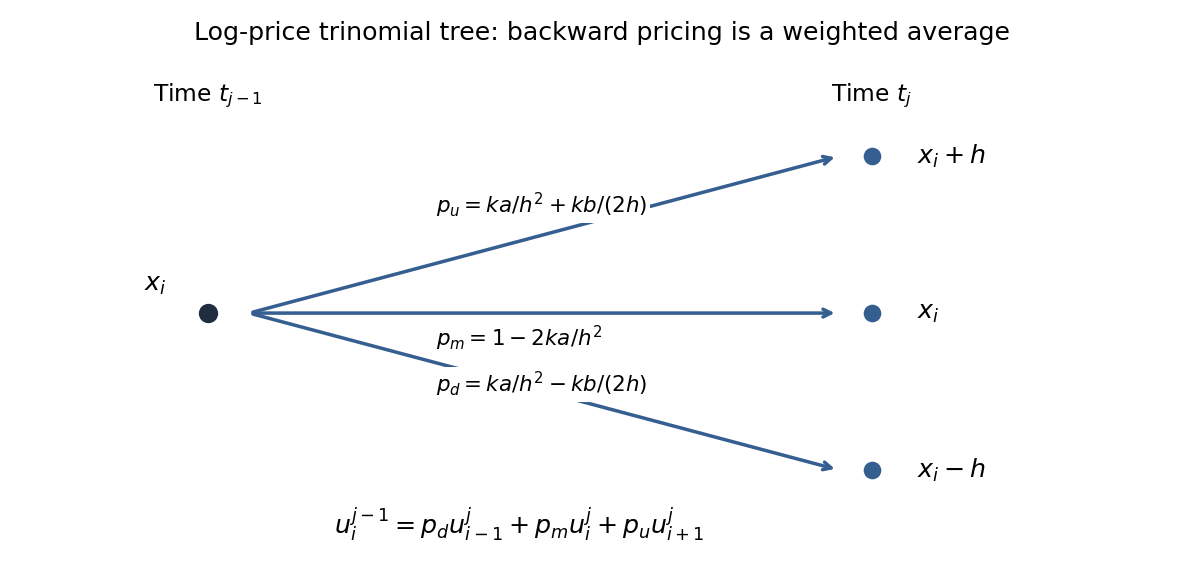
One-step log-price trinomial tree and its backward pricing average
. Details. All three weights are probabilities precisely when they are nonnegative:at every node and level. They are then automatically at most one. With positive , a simple sufficient uniform choice is and . If volatility vanishes at a node while drift does not, the centered weights cannot all be nonnegative.
Nonnegative weights make the backward update a convex combination, proving maximum-norm stability and monotonicity: interior errors cannot exceed the larger of the terminal and boundary errors. This is a sufficient stability condition, not an equivalence with every possible stability notion. For constant coefficients on an unrestricted or periodic grid, let and . The Fourier amplification factor isRequiring for every frequency gives and . Indeed, with , , so its two endpoint inequalities suffice. Probability weights require the stronger . The distinction prevents interpreting a merely Fourier-stable scheme with negative weights as a probability tree.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 f Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14The option delta is a derivative in , not in . With , the logarithmic chain rule givesThus use for the delta hedge, and for option gamma. These formulas also identify the finite-difference option Greeks correctly on the equally spaced log-price grid.
There are two distinct accuracy statements. A smooth exact function has central first- and second-derivative truncation errors of order . But the computed values themselves have error under the coupled refinement. Without further control on its spatial variation,Therefore the value error bound alone guarantees only first-order delta accuracy and does not guarantee convergent gamma. For example grid error has a central first difference of order and a second difference of order one, despite second-order value accuracy.
If instead the scheme has a smooth error expansion with corresponding derivative bounds, both Greeks can retain second-order accuracy at smooth interior points. Hence reliable gamma is possible with additional regularity and a verified Greek refinement, but cannot be inferred merely from the value convergence in part (e). This qualification is important because the stated bounded-volatility assumption supplies no such error-derivative control.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 e Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Suppose the starting steps satisfy the nonnegative-weight restrictions given below, the volatility is bounded away from zero, and the coefficients and pricing solution have the regularity needed for the usual error expansion at the monitored positive remaining maturity. The combined refinement , preserves , improves the spatial drift restriction, and yieldsIf , put . Then , so the difference between successive refinement levels is . Consequently successive differences shrink by a factor of approximately four, giving second-order convergence in space and first-order convergence in time. If the leading coefficient happens to vanish, a faster rate or an irregular ratio is possible.
The volatility bounds alone do not guarantee that expansion: coefficient smoothness, stability and treatment of the nonsmooth terminal payoff matter. The statement applies at fixed positive remaining maturity after appropriate smoothing, not to Greeks at the terminal strike. If the starting diffusion Courant number is already outside the stable range, the proposed coupled refinement preserves that defect and does not establish convergence.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Refining time alone converges to the fixed-grid, spatially discretized solution, assuming the time-dependent coefficients and boundary forcing are suitably regular. In time-to-maturity , the grid values solve a finite system . For fixed , the explicit Euler method converges to this system as ; time-step error decreases to zero.
The spatial finite difference error remains. Thus the limit is not in general the exact continuous pricing solution: sufficiently small time steps reveal an error plateau of order under the usual smooth-solution assumptions. A truncated-domain boundary error also remains fixed unless negligible as stipulated.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Refining space alone at fixed positive time step does not generally converge. The diffusion Courant number is , which grows by four at each halving of . For positive volatility it eventually violates the explicit diffusion stability restriction. The explicit log-price scheme for local-volatility pricing then amplifies grid-scale errors, rather than approaching the pricing solution.
The strike kink makes the failure concrete. At the terminal node , , while . Even a single step of fixed size gives , unbounded as if . Thus the problem is not cured by monitoring exactly at the money. A stable joint space-time refinement is required; the zero-diffusion case does not support the same diffusion argument and centered explicit advection has its own stability problem.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Write , and march backward from the terminal payoff. At the interior grid point useThe central finite difference spatial approximation and backward-in-calendar-time explicit Euler method giveHere , , and . At a far-left boundary use ; at a far-right boundary the call asymptotics are . These boundary values are inserted into the adjacent interior updates. Smooth-solution Taylor expansion gives consistency order in the evolution equation.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 3 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14Let , and . The chain rule gives and . Also , so . The killing term cancels, leavingThis is the explicit log-price scheme for local-volatility pricing equation. Under the risk-neutral measure, the corresponding log-price Itô formula givesThe logarithmic coordinate removes the stock-price factors from the diffusion coefficient, but retains the spatial variation of local volatility.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 2 d Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14For , and . Thus , and all values with this fixed spatial factor areThis Power payoff in the Black-Scholes model calculation remains valid for any real on ; the specified nonzero exponent excludes the constant-payoff subpart. It also supplies the moment term in power put-call parity above.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 2 c Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14 Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 2 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14For a time-independent value, . This is an Euler equation. Put to obtainFor , let . The roots areThey are distinct and real because , with one positive and one negative. The general stationary solution on is . There are no boundary restrictions in this subpart to eliminate either coefficient. In the degenerate case , the equation is first order: for its solutions are , while for only the zero stationary solution remains.
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 48 2 a Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14If the value is independent of spot, both spatial derivatives vanish. The Black-Scholes equation reduces to , so , where is an arbitrary constant. A constant terminal payoff is therefore discounted at the interest rate ; its separation constant is .
Past exam of the mathematics course of the University of Cambridge 2005 iii Paper 47 5 b Solution by Codex 0 Created 2026-10-03 Updated 2026-10-14
Codex 0 Created 2026-10-03 Updated 2026-10-14For each observation time, use only the currently susceptible risk set , with new-infection indicators . PutThis is the spatial Bernoulli infection model, under conditional independence of the indicators. Distances must be positive. Already infected trees should not be included as new susceptible trials. The minus sign in the power kernel is present in the original PDF, although it is absent in the converted TeX.
The parameter must be nonnegative: for and positive exposure, is not a probability. Therefore the stated unrestricted normal prior distribution cannot literally define the model. A coherent interpretation is a normal prior distribution restricted to ,Here is the standard normal distribution function. Use the same proper prior distribution in both kernel models. The given Gaussian prior distributions for and are mathematically valid on the real line for finite positive distances, though restricting them to positive values would impose decaying kernels and would require the corresponding normalized prior distributions.
The full conditional kernels areNeither is generally normal or another elementary conjugate family: the infection factors contain , and depends nonlinearly on . Thus a simple conjugate Gibbs sampler is unavailable. This does not make Gibbs sampling logically impossible; exact rejection or slice conditional draws could be used if implemented. A straightforward alternative is Metropolis–Hastings algorithm updates within each coordinate.
For example, put and use symmetric Gaussian random-walk proposals for . The target in these coordinates isThe factor is the Jacobian determinant and must be retained. Accept according to the ratio of this target, either for a block or one coordinate at a time. Posterior averages and quantiles of and estimate the requested marginal posterior distributions.
To compare kernels, introduce with positive model prior distribution probabilities . Under model two replace by , defining . The joint model/parameter target iswhere or and is its normalized proper prior distribution. Within each model use the preceding random-walk updates. For a concrete model switch, keep , propose the other model's kernel parameter independently from its prior distribution, and use equal forward and reverse switch-selection probabilities. A move from draws and has ratioAccept with the minimum of this ratio and one. The auxiliary-coordinate swap has absolute Jacobian determinant one, so no additional factor occurs; unequal switch-selection probabilities would require their reverse/forward ratio. This is a valid model-switching Markov chain Monte Carlo construction even though the two active models have equal parameter dimension. Prior distribution proposals may be inefficient, so fitted proposals can be substituted provided their probability densities remain in the acceptance ratio.
After checking mixing, estimate posterior model probabilities by the fractions of retained iterations in each model. The Bayes factor in favor of the first kernel isUse the posterior distributions within each model as well as these odds to assess the competing distance kernels. Proper prior distributions and their model-dependent normalizing constants are essential for this comparison.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:



All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact