A Homogeneous Poisson process models arrivals at a constant rate . Its counting process counts arrivals in , with . Its paths are right-continuous nondecreasing functions, take nonnegative integer values, and have unit jumps almost surely. The defining Poisson distribution of each increment isIt has stationary increments: the probability distribution above depends on the duration , not the starting time . It also has independent increments: counts in any finite collection of disjoint time intervals are independent random variables. Together these conditions specify the joint count laws, not merely the Poisson distribution at a single time.[ref]
Poisson Processes (Chapter 2). pp. 78-79: counting-process definition and its equivalence to exponential interarrival times
The rate has units of arrivals per unit time; is dimensionless. The Poisson distribution givesFor a toy rate per minute and a duration of minutes, the expected value and variance of the count are both . The probability of no arrival is , and the probability of exactly three is . In two consecutive one-minute intervals, the probability of exactly two arrivals in the first and exactly one in the second is , using independent increments. These are exact model calculations with rounded decimals, not measured frequencies.
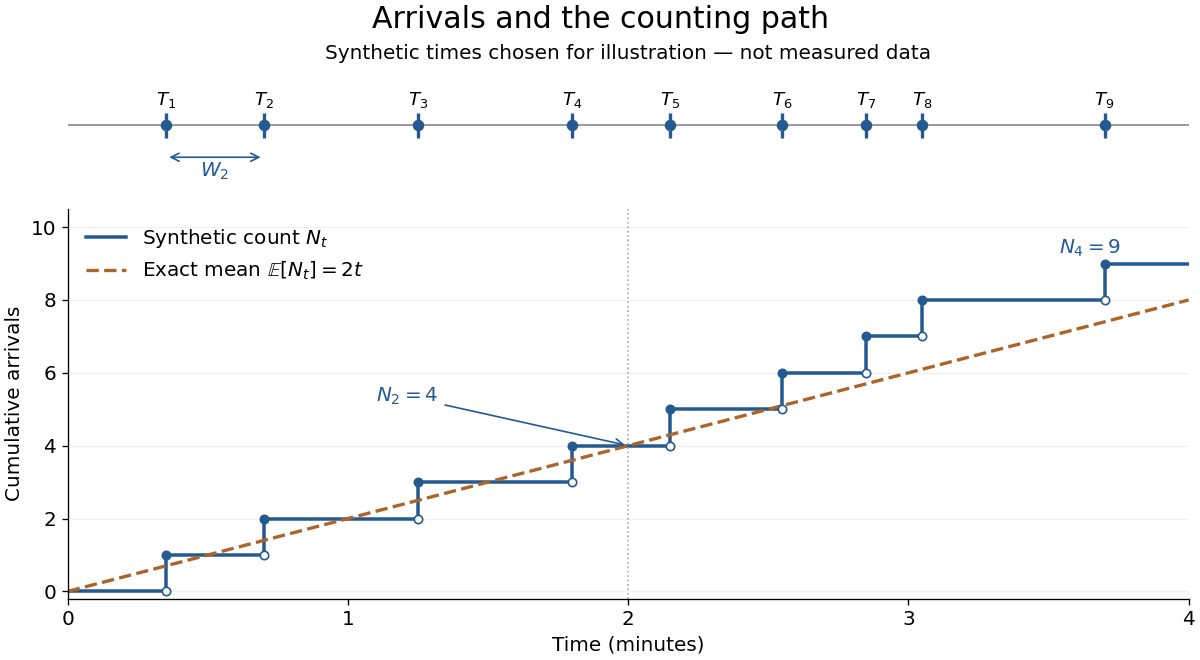
Synthetic arrival times and their right-continuous counting path, compared with the exact mean at two arrivals per minute
. Details. 
The diagram's nine hand-chosen arrivals illustrate a path; the line is an expected value, not a prescribed trajectory. Constant rate does not imply evenly spaced arrivals. Poisson interarrival times connect the count description to waiting, while Poisson thinning explains how independently routing arrivals produces separate streams. This makes the Poisson process useful as a simple arrival model for a queue, provided constant rate and independent increments are plausible. For a deterministic changing rate, use an Inhomogeneous Poisson process; bunching or history-dependent arrivals need additional assumptions. Conditional on , the arrival times are the order statistics of independent uniform distributions on , as developed in Poisson process conditional arrival times.
Consider a homogeneous Poisson process of arrival rate , with each arrival staying for a fixed duration . For any fixed arrival index , its visit overlaps another visit if the preceding interarrival time is below or the following interarrival time is below . If the nearest preceding arrival has already left then all earlier ones have left; if the next arrival is too late then all later ones are too late. These two gaps are independent exponential random variables, so the probability of no overlap is . Taking its complement gives the formula. This is an unconditional statement for a fixed indexed arrival; conditioning on a fixed calendar closing time would change the problem.
For a rate-one Poisson process with Poisson arrival times , suppose and . Thenwhere and denotes the bivariate normal distribution with standard normal marginal distributions, including the singular cases. In particular, equal scales give and separated scales give .
To prove this, fix real and put for large . The event is exactly . Counts at the two deterministic times are sums of a shared count on and an independent count on the remaining interval. The central limit theorem for a centered Poisson random variable of diverging parameter follows by writing a count at a real time as its count at , a sum of independent unit increments, plus an independent remainder with expected value at most one. Markov's inequality makes that remainder negligible after division by .
Apply this central limit theorem to the two independent count blocks whenever their lengths diverge. A block with bounded length, or length negligible compared with the scale of its coordinate, contributes a term tending to zero in probability. The standardized pair of counts therefore has a joint normal limit whose correlation coefficient isThis includes : the difference block then has negligible variance after normalization. In the arrival event the standardized count at must be at least . Reversing this inequality changes the sign of the second limiting normal random variable, giving the asserted negative correlation coefficient. Continuity of the marginal distributions permits the moving thresholds and the weak inequalities, including at the singular limits.
Every is realized by with , and zero by . Conversely, even when has no limit, it has a subsequence converging in the extended interval . If the original pair has a joint bivariate normal distribution limit, that subsequence has the same limit, forcing its correlation coefficient into .
For a Poisson process, the count and Poisson arrival time have the displayed inequality at every deterministic . A large count and a late arrival reflect opposite directions of the same fluctuation.
Here is a proof from independent increments. If , write with independent of . Conditional on , the event has probability , a nondecreasing function of . The event has a nonincreasing indicator function . For any random variable and an independent copy , oppositely monotone bounded functions satisfyTaking proves the claim. If , condition instead on ; then is nonincreasing in and is nondecreasing, giving the same inequality.
The inequality is preserved under joint convergence in distribution when the marginal distributions of the limit are continuous. Consequently, a limiting bivariate normal distribution with standard normal marginal distributions cannot have positive correlation coefficient. For , conditioning on makes , so , contradicting the inequality. For , that quadrant has probability , which also contradicts it.
The time of the -th event of a Poisson process. At positive rate , the Poisson interarrival times , with , are independent and identically distributed random variables with the rate- exponential distribution. In particular, has expected value and variance . The inverse-count identity is .
Let be the th arrival time, and set . In a Homogeneous Poisson process of rate , the gaps are independent and identically distributed random variables with an exponential distribution:Here uses the rate convention. Under the scale convention , the same probability density function is ; a simulation function accepting a scale must receive . Conversely, summing independent rate- exponential random variables to form and counting those sums constructs a Homogeneous Poisson process.[ref]
The first-gap formula follows immediately from and the Poisson distribution. Independence of all successive gaps is the additional interval-theorem assertion; deterministic-time independent increments alone should not simply be substituted at random arrival times without justification. The memorylessness of the exponential distribution givesAt the toy rate of two per minute, the mean gap is half a minute, the median is minutes, and the probability of waiting longer than half a minute is . Here is the natural logarithm. Already having waited a minute without an arrival leaves this same conditional probability of waiting another half minute. The exponential distribution describes a model with no aging of the remaining wait; a scheduled arrival with a fixed gap has no such property.
A Poisson process observed for a fixed duration has likelihood proportional to . Complete independent exponential distribution gaps observed until a fixed event count have likelihood . Both give count divided by exposure, but the exposure is random in the second design. Under fixed exposure the total count is sufficient: conditional on it, the event locations are independent of the rate, so exact timestamps add no rate information to interval counts. Gap estimates and fixed-horizon estimates should not be compared without distinguishing their stopping rules and any final censored gap.
For a homogeneous Poisson process of rate , almost surely: unit-time increments are independent Poisson variables and the strong law of large numbers applies, then monotonicity fills the intervals between integers. At its th point , simplicity gives . Consequently . Rate and mean interarrival time are reciprocals.
For a unit-rate Poisson process and real , the displayed process is a nonnegative martingale with initial value one. Independent increments give , proving its conditional mean property. The Ville inequality turns this exponential moment into a maximal tail bound.
For a unit-rate Poisson process, gives the displayed maximal deviation bound for . Poisson exponential martingales and the Ville inequality control upper and lower deviations; the upper-tail rate also bounds the lower-tail probability. Since and , the rate is strictly positive for every positive deviation level.
For a rate- Poisson process, keeping every second arrival gives a renewal process with independent interarrival times equal to sums of two exponential waiting times. Put . Its count mean and variance are and . The variance is strictly smaller than the mean for : sixteen times their difference has derivative and is zero at zero, because . Therefore this process is not a Cox process.
A counting process which, conditional on a random nonnegative locally integrable intensity , is an Inhomogeneous Poisson process. For , conditioning gives and . Thus finite-variance counts are never underdispersed. Randomness of the intensity may induce dependence between increments which are independent conditionally.
When each parent has a Poisson number of independently displaced offspring, the conditional offspring process has the displayed directing measure. For disjoint target sets, multinomial distribution splitting of a parent's Poisson count gives joint probability generating function . Multiply over independent parents to obtain independent Poisson counts conditional on the parents. Compactly supported displacement ensures local finiteness for a locally finite parent process.
// Destination: discrete-probability-distribution.bigb
A Cox process can be directed by a random locally finite measure, which need not have a density. Conditional counts in disjoint sets are independent Poisson variables with that measure's masses. Uniform circular offspring displacements give a directing measure supported on random circles; its unconditional mean can still be a multiple of planar Lebesgue measure. A random intensity function is the special case in which the directing measure is absolutely continuous.
An inhomogeneous Poisson process with locally integrable intensity has independent increments andfor . Its cumulative intensity is .
If and , then is a rate-one Poisson process, becauseConversely, , so has a Poisson distribution of mean .
The difference of two independent rate- Poisson processes is a continuous-time simple symmetric random walk with total jump rate and variance at time .
Poisson thinning splits a Poisson process by independently marking each arrival as retained or rejected. Let the original Homogeneous Poisson process have rate , and let be a deterministic measurable function of time. Attach independent uniform distributions on , independent of the entire original Poisson process. At arrival time , retain the arrival if . Given all arrival times, these decisions are independent and have the specified retention probabilities. Define the two counting processes using an indicator function:The Poisson thinning theorem gives independent retained and rejected Inhomogeneous Poisson processes. Their rates are and , respectively, in the sense of the intensity function of a point process. In particular, for ,The independence is of the two whole processes: every finite collection of retained counts is independent of every finite collection of rejected counts. It is not merely zero covariance for one interval. For constant , the streams are Homogeneous Poisson processes of rates and ; the endpoints include the identically zero stream.[ref]
Lectures on the Poisson Process by Günter Last and others. Definition 5.7, Proposition 5.5, Theorem 5.8 and Corollary 5.9, printed pp. 42-44: location-dependent independent marking, intensities, and independence of the split processes
For an exact toy calculation, take per minute and retain with on and on . In the first two minutes, the retained and rejected expected values are and . In the next two minutes they are and . Over all four minutes, are independent Poisson distributions with mean each, and their sum has mean . ThusThese probabilities and expected values describe the model, not empirical measurements. In the diagram, the original nine synthetic arrivals split into five retained and four rejected arrivals; those realized counts need not equal their expected values.
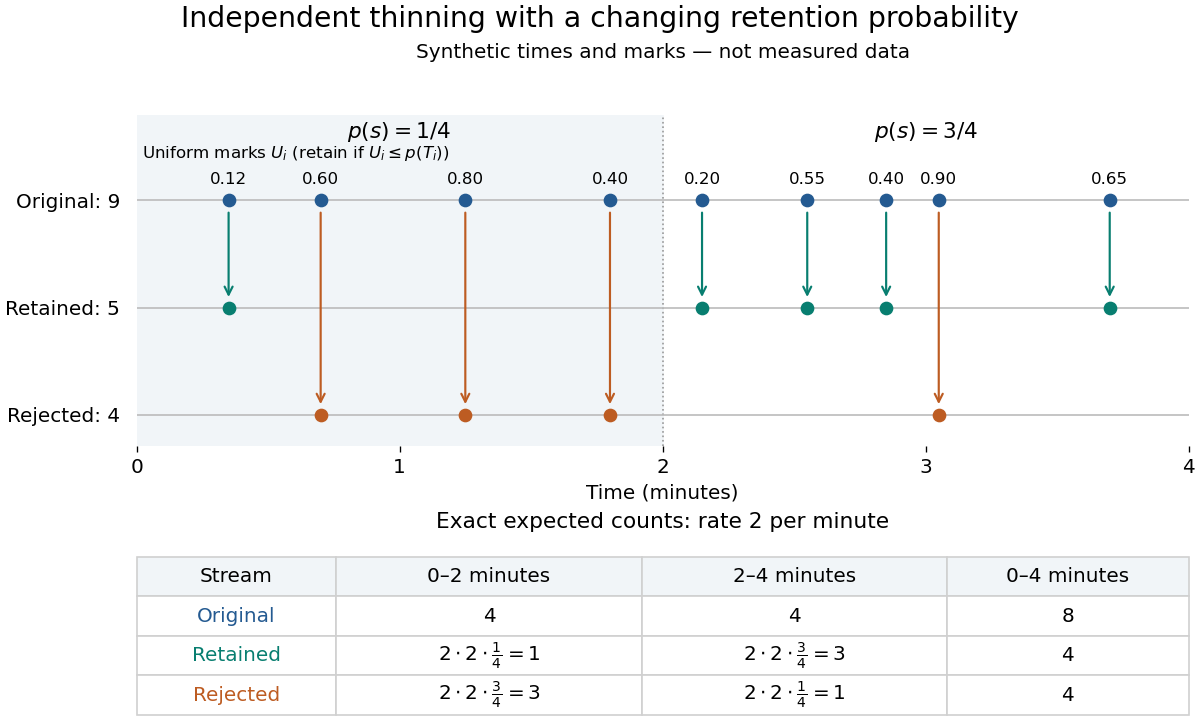
Independent marks split a synthetic Poisson arrival path, with exact expected counts for two time-dependent retention probabilities
. Details. 
The mechanism explains why mutually exclusive labels can yield independent counts: randomness of the original total offsets the dependence from allocating a fixed total. For constant and an interval with original mean , the conditional retained count has a binomial distribution given . The joint probability generating function isThis factorization proves the two independent Poisson distributions; disjoint original intervals give independent pairs. For varying , the Independent marking theorem for Poisson point processes gives the same conclusion with the two integrated intensities. The joint red and green Poisson count formula gives the corresponding direct calculation with probability mass functions.
Independence here is unconditional. After conditioning on , the identity gives covariance for constant . Thus the retained and rejected counts are dependent for and , even though their unconditional covariance is zero. Poisson thinning can model independent routing of arrivals, or independent detection of arrivals with a known efficiency schedule; using only a retention fraction without checking the marking mechanism can give a wrong count law.
Independent marking is the hypothesis that guarantees the Poisson thinning theorem. Equal marginal retention probabilities do not guarantee it. Consider one Bernoulli random variable with success probability , independent of a Poisson process, and retain every arrival when and none when . Each arrival is retained with probability , but the marks share the same coin. In an interval whose original count has Poisson distribution of mean , the retained count is and the rejected count is , soThe extra variance shows that is not Poisson distributed; the negative covariance proves dependence. Its no-arrival probability is , rather than . For the toy values , both rules have retained mean , but the common-coin rule has variance and no-arrival probability , compared with variance and no-arrival probability for independent marking. These formulas follow by conditioning on and using the law of total variance.
An arrival-dependent or adversarial retention rule can change the law just as strongly. Keeping every second arrival gives . Its successive retained gaps are sums of two independent exponential random variables, hence have the Erlang distribution of shape two and rate , not an exponential distribution. The resulting renewal process and its count variance are analyzed in Every second Poisson arrival has underdispersed counts, and the two dependent streams in alternating split of a Poisson process. As an even more restrictive rule, keeping only the first arrival ever gives , a Bernoulli distribution at each , so it cannot have a positive-mean Poisson distribution. A thinning rule must specify how decisions depend on arrivals and on one another; the independent-marking conclusion cannot be applied automatically to arbitrary deletion.
Let be a nonnegative integer-valued random variable with finite expected value , and independently label each of its items with either of two equally likely labels. If the two resulting counts are independent random variables, then has a Poisson distribution. Indeed, its probability generating function obeys . With , iteration gives . Finite expected value gives , hence and . Conversely, Poisson thinning produces independent Poisson distributions for the two counts.
Assign each of claims with independent category labels to one of finitely many categories with probabilities . Conditional counts have a multinomial distribution with probability generating function . Averaging over gives . This proves independent category counts and supports discrete-severity compound Poisson distribution representations.
Mark each member of an independent Poisson infection cohort by its symptom-onset interval, using independent delays. Poisson thinning gives independent onset-bin counts, and sums over independent cohorts remain independent Poisson counts. Fixed cohort totals instead induce multinomial dependence. The marking assumptions are essential.
For an M-M-infinity queue with empty initial state, Poisson arrivals of rate and exponential lifetimes of rate produce a Poisson occupancy of mean at time .
Conditioned on , the arrival times are distributed as the order statistics of independent uniform points on . Their conditional joint density onis , obtained by dividing the Poisson-process density by .
For independent Poisson processes of rates and , the number of type-two arrivals before the first type-one arrival satisfiesThis follows by marking the superposed process by its arrival type.
Let be the points of a rate- Poisson process and let independent identically distributed marks be independent of the process. ThenCondition on , use uniform order statistics, and sum the resulting exponential series.
With , the age of a rate- Poisson process has meanGiven , the last arrival is the maximum of uniform points and , including .
Articles by others on the same topic
There are currently no matching articles.