For a nonnegative integer-valued random variable , write . Its probability generating function packages the entire probability mass function into one power series:This domain is guaranteed, even for complex , because . At the constant monomial is one, including when : the convention here gives . Also . The power series may converge beyond this domain, but that needs an additional argument. Encoding a probability distribution this way turns convolution of independent random variables into multiplication.[ref]
Random: Probability, Mathematical Statistics, Stochastic Processes by Kyle Siegrist. Expected Value, §6 Generating Functions, Basic Theory, The Probability Generating Function: definition, absolute convergence, inversion, and the independent-sum identity
Coefficient extraction recovers every probability mass:Indeed, termwise differentiation of a power series is valid inside ; evaluating the th derivative at zero kills every term except . Thus two probability generating functions with the same coefficients describe the same probability distribution, without any finite-moment assumption.
At one, approach along the real line from below. For each positive integer , termwise differentiation of a power series followed by the monotone convergence theorem gives the factorial momentFor integer , set . The limit may be infinite; it is a finite boundary value only when the corresponding factorial moment is finite. In particular, a finite first moment givesand a finite second moment givesThe variance formula follows from . These are boundary limits of derivatives; they do not assert that the probability generating function extends smoothly through one.
For a nonnegative integer-valued random variable, its moment-generating function satisfies wherever finite. The guaranteed probability generating function domain therefore supplies finite values for real ; it does not guarantee positive exponential moments or a finite moment-generating function on a neighborhood of zero. Bounded nonnegative integer-valued random variables have polynomial probability generating functions, but their convenient behavior is not a general existence theorem.
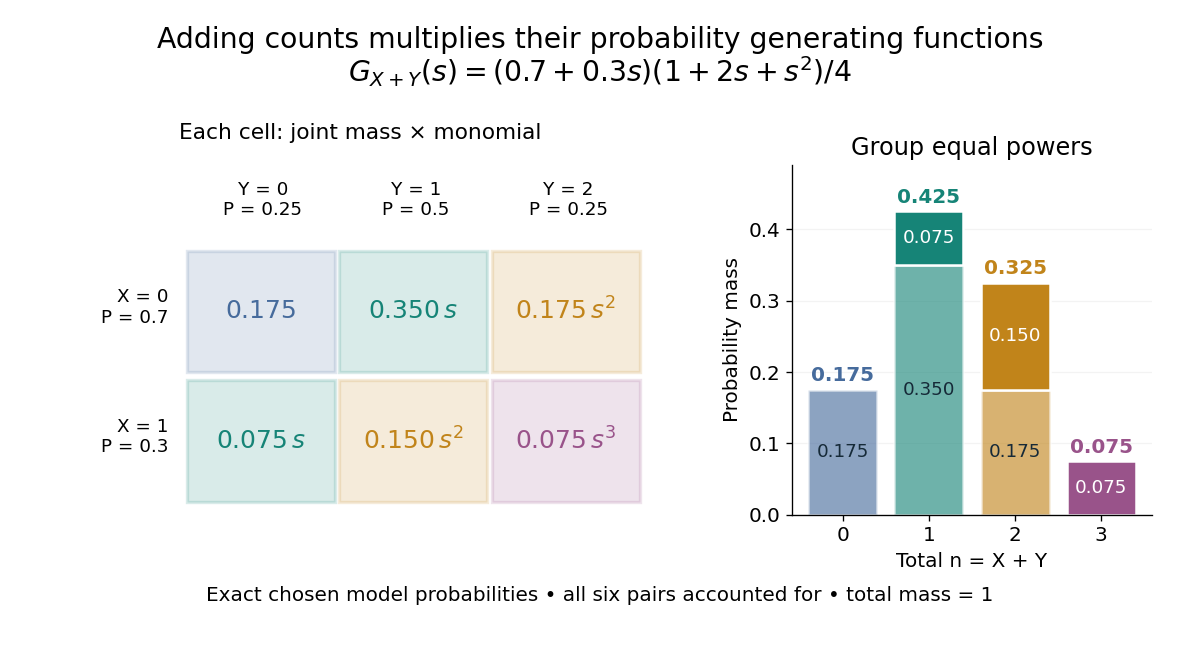
For nonnegative integer-valued independent random variables , factor the expected value of a product:The Cauchy product explains what this means for individual probability masses:Every way of splitting the total contributes once. This is convolution of independent random variables; multiplying probability generating functions performs the bookkeeping automatically.
For an original example, take independent and , using the Bernoulli distribution and binomial distribution. ThensoDirect enumeration of the six pairs gives the same probability masses. For example, total one collects and , with contributions . The coefficients sum to one. The expected value is ; since , the variance is , agreeing with .
Uncorrelated random variables are insufficient for the product identity. For a concrete counterexample, let be uniform on and set , . Then , but , whereas . Zero covariance controls one mixed moment, not the full joint probability mass function.
Let be a nonnegative integer-valued random variable, and let be nonnegative integer-valued independent and identically distributed random variables, with common probability generating function . Require the whole sequence to be independent of , so are jointly independent. Set the random sumwith the empty sum equal to zero. Given , the probability generating function of an independent sum yields the conditional expectation . By the law of total expectation,The composition is valid because . Merely making the independent of each other does not preserve their conditional laws when depends on them. This is the probability generating function version of transform composition for an independent random sum.
For a Poisson distribution count with mean , substitution into gives a compound Poisson distribution withIf the jumps have finite second moment, conditioning also gives mean and variance . The extra spread comes from randomness in the count as well as randomness in the jumps.[ref]
Random: Probability, Mathematical Statistics, Stochastic Processes by Kyle Siegrist. The Poisson Process, Compound Poisson Processes, Definition; Properties: mean, variance, and generating-function conditioning proof; Compound Poisson Distributions: count independent of the sequence
For an original example, choose and jumps taking values one and two with equal probability. Keep the independence assumptions above. ThenHere , , and . The law of total expectation and law of total variance giveThus the aggregate is not itself a Poisson distribution, whose mean and variance would coincide.
To recover the probability mass function without repeated differentiation, use and compare coefficients:For example, . As an independent check, expanding gives
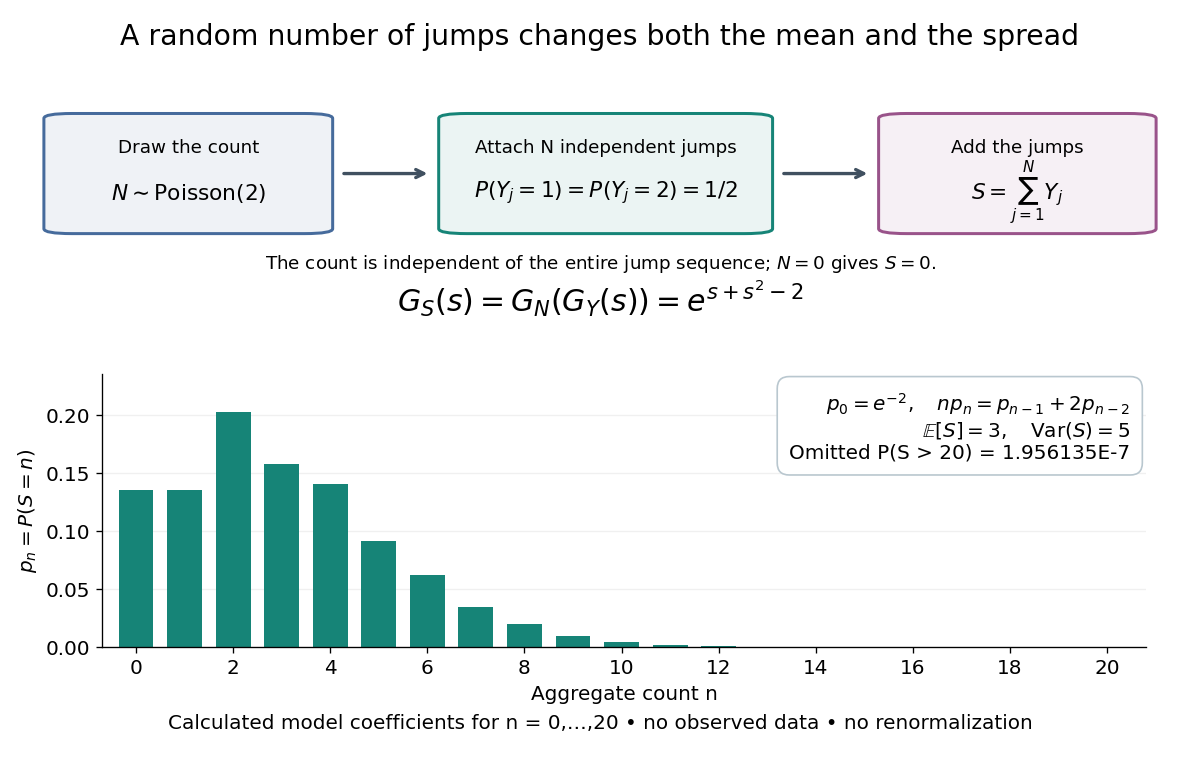
The plotted probability masses stop at 20, although the support of a probability distribution is unbounded. The omitted tail probability isThis model has bounded jumps and an unbounded count. Its entire probability generating function does give a finite moment-generating function at every real argument, but the general random sum composition only guarantees the stated domain.
Encode a fair die with face labels by . Its probability generating function is . Two independent dice with polynomials have the same sum probability distribution as another pair if and all four dice have faces. Redistributing factors can construct unexpected examples, but each resulting polynomial must have nonnegative integer coefficients, no constant term if labels must be positive, and value at . For example, reallocating from one copy of to the other gives face labels and .
For a positive integer-valued random variable of finite support, this transform is a finite Dirichlet series. Its values encode ordinary moments, , and its derivatives at zero encode logarithmic moments: . Positive support is essential to these definitions; the transform is distinct from the ordinary probability generating function .
Articles by others on the same topic



A probability-generating function (PGF) is a specific type of power series that is used to encode the probabilities of a discrete random variable. It is particularly useful in the study of probability distributions and in solving problems involving sums of independent random variables. ### Definition For a discrete random variable \( X \) that takes non-negative integer values (i.e.