The initial table of content was limited to the first level because it is larger than 1000 articles. There are 7376 articles in total. Expand a branch to load its children.
A rough path augments a path with compatible higher-order iterated-integral data. The extra data records effects, such as signed area, that are not continuously determined by the first-level path in the uniform topology. A rough differential equation uses this enhancement to recover a continuous solution map for irregular drivers.
A control is a continuous nonnegative function on ordered pairs of times, zero on the diagonal and superadditive as displayed. It measures the size of increments of a rough path, typically through . Continuous finite variation gives suitable controls, which let local estimates be stated without tying them to a particular time parametrization.
A rough differential equation interprets a differential equation using the higher-order data of its driving rough path. For , its local expansion includes , with a remainder controlled at order greater than one. For a smooth driver it is the usual controlled ordinary differential equation; for enhanced Brownian motion it is the corresponding Stratonovich equation.
A pathlevel solution is the ordinary state path satisfying a local rough Taylor expansion with a remainder of order in a control function for rough paths. It specifies the first level of the solution, rather than requiring the full lifted solution as part of the definition. With vector fields of regularity , , the Davie lemma bounds discrete Euler errors uniformly; compactness and passage to the limit give such a path.
For a finite time grid, suppose a nonnegative error is zero on neighboring points and obeys . For a control function for rough paths and , sufficiently small control intervals have the displayed bound with constants independent of the grid. Splitting near half the control size makes the higher-order errors contract, and handles a crossing single grid interval by its zero error. Applying this to local Euler composition errors yields compactness of approximate pathlevel solutions.
For sufficiently regular vector fields, for example bounded fields with bounded derivatives through order three when , the solution map of a rough differential equation exists uniquely and is locally continuous in the rough path metric. Ordinary differential equations driven by smooth approximations therefore converge whenever their enhanced drivers converge. The theorem makes the enhancement, rather than just the original path, the correct input for a continuous solution map.
The Stratonovich enhancement of Brownian motion is a geometric -rough path for every . Its second level consists of Lévy area and the prescribed symmetric tensor. Its increments satisfy the Chen identity and have finite Hölder rough-path norms at every exponent below .
For every and every positive radius, the canonical Brownian enhancement has positive probability of lying in the displayed rough path metric ball. This controls both displacement and area. Together with Cameron-Martin quasi-invariance of enhanced Brownian motion, it puts every lifted Cameron-Martin control in the support of enhanced Brownian motion.
For , the support of a measure of enhanced Brownian motion is the rough-path closure of path signatures of paths in the Cameron-Martin space of Wiener measure. Polygonal convergence gives one inclusion. For the reverse inclusion, decompose Brownian motion into its polygonal interpolation and independent pinned bridges. The bridge enhancement becomes small in probability as the mesh decreases, while every finite-dimensional neighborhood of the polygonal vertices has positive Gaussian probability. Rough path translation then gives positive probability in every ball around a prescribed control path signature.
For deterministic nested partitions with mesh tending to zero, lift the polygonal interpolation of Brownian motion by its ordinary iterated integrals. These path signatures converge almost surely to enhanced Brownian motion in every Hölder rough-path metric of exponent below , hence in -variation for . Conditioning on the partition values gives a nested martingale for the first level and the off-diagonal second levels. Moment bounds and interpolation upgrade pointwise convergence to convergence in the rough path metric.
Condition on the Brownian values at a dyadic mesh. First-level increments and antisymmetric area increments of its polygonal lift are conditional expectations of the corresponding Brownian increments. Conditional Jensen inequalities and the homogeneous degree-two norm give the displayed bound. The Doob maximal inequality makes the right-hand side uniformly finite almost surely when the Brownian Hölder norm has sufficiently many moments. Dense-time martingale convergence and equicontinuity then yield simultaneous convergence at every time.
The path signature collects the ordered iterated Riemann-Stieltjes integrals of a continuous path of bounded variation. Its truncation belongs to the free step-N nilpotent Lie group. It multiplies under concatenation by the Chen identity, is independent of orientation-preserving reparametrisation of the whole path, and records more than its endpoint displacement.
For a continuous path of bounded variation, integrate successively over the ordered simplex using Riemann-Stieltjes integrals. These integrals form the levels of its path signature. Appending the final integration variable gives the differential recursion .
The product of two coordinate iterated integrals of a path is the sum over order-preserving interleavings of their integration variables. Split the product of the two ordered simplices according to the joint order of all variables. This identity explains the algebraic constraints on a geometric rough path and the cancellation of low-degree terms in the composition of its local Euler maps.
Partition each ordered integration simplex according to the number of times before the concatenation point. The integral over each resulting region factors into an initial iterated integral and a final iterated integral. Summing these factorizations proves the identity in the truncated tensor algebra.
This inhomogeneous variation metric compares the tensor increments level by level. A common alternative is the Hölder metric . On a finite interval convergence in this metric implies -variation convergence whenever . Both topologies control the iterated integrals needed by the universal limit theorem.
A geometric -rough path is a limit, in the rough path metric, of path signatures of sufficiently regular paths. It is a weak geometric p-rough path. At the same exponent these definitions need not coincide; weak geometric paths can be approximated after slightly weakening the variation exponent. The Brownian enhancement is geometric for every .
For and a continuous path of bounded variation, translate the first level by and add the mixed integrals , and to the second level. Integration by parts defines the second mixed integral. The operation is continuous in the rough path metric and the variation norm of . For canonical lifts it is precisely the enhancement of the sum of the paths.
For a deterministic path in the Cameron-Martin space of Wiener measure, the law of is equivalent to the law of enhanced Brownian motion. The Cameron-Martin theorem gives equivalence for the underlying Brownian paths; the canonical enhancement of the translated path is exactly the rough-path translation, including its mixed area terms. Continuity of this translation transfers small-ball positivity at the identity to every control signature.
A weak geometric -rough path is a continuous path in the free step-N nilpotent Lie group, with , whose increments have finite -variation for the Carnot-Carathéodory distance. Its multiplicative increments are . They obey the Chen identity and the algebraic symmetries of path signatures.
The first level of this group path is zero but its second level grows linearly. Its Carnot-Carathéodory distance increments are a constant times . It therefore has finite -variation precisely when , and is a step-two weak geometric rough path at , even though its first-level trace is constant. For higher truncations the same Lie exponential defines a compatible lift.
Harmonic analysis decomposes functions into elementary oscillations, generalizing Fourier series and the Fourier transform. On a locally compact Abelian group the elementary oscillations are continuous unitary characters, and Haar measure supplies translation-invariant integration.
A positive Borel measure near a domain boundary is a Carleson measure when its mass in boundary neighborhoods is bounded by a constant times their boundary measure. On the unit disc, this becomes the displayed bound for every Carleson box. The equivalent hyperbolic geodesic cap version follows from the geodesic-cap and Carleson-box comparison. The Carleson embedding theorem on the disk explains why this geometric growth condition controls integration of analytic Hardy spaces.
A positive Borel measure on the unit disc satisfies for every H1 space on the unit disk function exactly when it is a Carleson measure, with comparable optimal constants. The normalized squared Cauchy kernel tests necessity. For sufficiency, the boundary shadow of every point with lies inside a component arc of . The geodesic-cap and Carleson-box comparison bounds the measure of each shadow region by its component length, giving . The layer cake representation and H1 non-tangential maximal inequality on the disk give the embedding. The broader kernel and covering mechanism is discussed in Terence Tao's harmonic-analysis notes, Exercise 2 after Lemma 4.1; the analytic endpoint here uses the fractional-power argument just given.
A boundary neighborhood over an arc of the unit circle, with radial depth equal to its normalized angular length . Changing that depth by any fixed positive factor gives an equivalent Carleson measure condition. Large arcs and central mass can be handled separately by finitely many fixed neighborhoods covering the unit disc.
This supremum function takes a supremum over a cone approaching the boundary point ; the positive number is its aperture. For an analytic upper-half-plane function, it belongs to . To prove this without first assuming boundary absolute continuity, shift the function upwards, apply subharmonic Poisson comparison to its square root, and use the strong bound for the Hardy-Littlewood maximal function. Fatou lemma removes the shift.
For integrable boundary data on the unit circle, this follows from the Poisson kernel bound in a fixed Stolz region. The arc of radius and successive dyadic annuli contribute at most , which sum to the displayed estimate. This links harmonic extension to the Hardy-Littlewood maximal function and its strong bounds for .
For , an analytic Hardy space controls the integral means of a holomorphic function as it approaches a domain boundary. On the disk, requires ; on the upper half-plane it requires . For use a supremum norm. These analytic spaces differ from the harmonic Hardy space of the upper half-space; the Hardy space of the circle is the boundary Hilbert-space realization of the disk space.
This Hardy space consists of holomorphic functions with , where is normalized angular measure. The H1 non-tangential maximal inequality on the disk controls their approach to the boundary, and the Carleson embedding theorem on the disk characterizes measures against which all these functions remain integrable.
For an analytic H1 space on the unit disk function, its fixed-aperture non-tangential maximal function obeys the displayed strong bound. First replace by , . The fact that modulus powers of holomorphic functions are subharmonic gives . Since a Poisson maximal function is dominated by the Hardy-Littlewood maximal function, the strong Hardy-Littlewood maximal inequality yields . Pointwise interior convergence and the Fatou lemma remove . Analyticity permits this endpoint estimate; general boundary data have only a weak maximal bound.
For , this holomorphic function has H1 space on the unit disk norm one: its boundary modulus is the unit-mass Poisson kernel on the circle. The radial integrals are bounded by that boundary integral by subharmonic comparison and tend to it by continuity. Choosing at depth comparable to an arc's length makes bounded below by the reciprocal length throughout its hyperbolic geodesic cap. It tests necessity in the Carleson embedding theorem on the disk.
This Hardy space consists of bounded holomorphic functions on the unit disc, with norm . Its almost-everywhere boundary realization follows from the Fatou theorem for bounded holomorphic functions.
A bounded holomorphic function on the unit disc has finite nontangential limits almost everywhere on its boundary. To outline a proof, bounded real and imaginary harmonic parts have boundary representations: apply the Banach-Alaoglu theorem to their circular traces and pass to the limit in the Poisson integral on the unit disk. Almost every boundary point is a Lebesgue point. The fact that a Poisson integral converges nontangentially at Lebesgue points gives the desired limits. Their norm equals the interior supremum norm, and the Poisson integral recovers the original function. Exceptional points can lack even radial limits; is a bounded example at the boundary point one.
If a finite complex Borel measure on the circle has Fourier coefficients for all , then it is absolutely continuous with respect to arc length. The reflected Fourier convention gives the equivalent theorem with positive coefficients vanishing. The Poisson integral on the unit disk is analytic because of the one-sided Fourier spectrum. Subharmonic comparison for its square root and an maximal estimate produce an integrable radial maximum. This maximum dominates the weak-star boundary measure, forcing absolute continuity of measures. The same proof on the real line says that a finite measure with Fourier transform of a finite measure supported in has a Lebesgue density.
For and a positive threshold , take maximal dyadic cubes with mean of exceeding . They are disjoint, have total volume at most , and their means are at most . Replace inside each selected cube by its mean to obtain ; write . Then , , , and . The outside bound follows from the Lebesgue differentiation theorem. This separates a bounded part from localized cancellation errors.
A complex-valued function on a group is positive-definite when the displayed inequality holds for every finite choice of points and coefficients. This includes positive semidefinite, rather than necessarily strictly positive definite, Gram matrices. In particular and . On an Abelian group, every convolution square with is continuous and positive-definite: its quadratic form is the integral of .
For an Abelian group, on finite formal sums of group points, define , with the first variable linear. Quotient by the null space of this positive semidefinite form and complete to a Hilbert space. Left translation is unitary, and generates a dense span of translated vectors. For continuous , the equality gives strong continuity. This realizes as a matrix coefficient without assuming its integral representation.
For a locally compact Hausdorff Abelian group, a continuous positive-definite function is uniquely representable as for a finite positive Radon measure on the Pontryagin dual group. Its total mass is . Conversely every such finite positive measure defines a continuous positive-definite function.
A positive-definite function on the discrete group is the sequence of Fourier coefficients of a unique finite positive Borel measure on the circle, with total mass . Positivity makes the finite sums nonnegative. Their measures converge weakly to the required measure; uniqueness follows from density of trigonometric polynomials in continuous functions.
For a finite positive Borel measure on the circle, averaged squared Fourier coefficients tend to the sum of squares of its atomic masses. Express each squared coefficient as a double integral and average the circle character. The averaged character is bounded by one, tends to one on the diagonal and to zero elsewhere, so the dominated convergence theorem gives the diagonal mass. In particular an atomless measure has vanishing averaged absolute coefficients by the Cauchy-Schwarz inequality.
For finite sums of compactly supported convolution squares, . Insert the Bochner theorem representation of into and apply the Fubini theorem: its representing measure is . Reversing and using uniqueness gives the displayed identity. It makes the local quotients consistent wherever .
Potential theory studies harmonic functions, subharmonic functions, and the Laplace operator, including harmonic measure, regular boundary points, and the Dirichlet problem. The Brownian representation of the Dirichlet problem connects these analytic objects with exit probability distributions.
A Dirichlet form on a real space is a densely defined closed nonnegative symmetric bilinear form with the Markov contraction property. In the real case, truncating to keeps it in the form domain and cannot increase . The Dirichlet form of a Markov chain is a discrete energy example; Laplacian energy on a region supplies a continuous example.
An integral equation asks for an unknown function that occurs under an integral. Integral equations with a variable upper limit have a triangular dependence structure that often permits successive approximation.
This square-root-kernel integral equation is inverted by integrating over and interchanging integrations. The inner integral over equals , so . Differentiating recovers . The changes of variables , put the angular-ray equation into this form.
Suppose is continuously differentiable on . For , the improper integral exists, but substituting directly into the ordinary Leibniz integral rule produces an undefined endpoint term. First use integration by parts to obtainThe new endpoint term at vanishes, and the differentiated kernel is locally integrable. Differentiating gives the displayed formula. One rigorous justification rewrites the second term as by Fubini's theorem; the inner integral is continuous for , so the fundamental theorem of calculus applies. Moreover : if , the right difference quotient at zero diverges rather than defining a finite derivative.
For an absolutely continuous with , this causal Abel integral equation has inversionUnder Laplace-transform growth hypotheses, the convolution theorem for Laplace transforms converts the original kernel into . Since , the transformed inverse is , giving the formula. It also holds locally in the corresponding integrable convolution class: convolving the two power kernels produces the constant by the beta-gamma identity, so substitution recovers . The same convolution identity proves uniqueness in that class. For example gives .
A linear integral equation depends linearly on its unknown function. For example, with has a trivial homogeneous null space whenever its inhomogeneous problem has a unique solution: otherwise a nonzero homogeneous solution could be added to that solution. This is the uniqueness step used in dressing constructions of a Lax pair.
A Volterra integral equation has a variable integration limit, so its value at a point depends only on earlier values. Repeated integration produces factorial decay, which often makes its Neumann series converge without a smallness assumption.
The derivative and convolution theorem for Laplace transforms give . Partial fractions yield , so tends to two. A direct check gives and . Introducing the memory variable gives the equivalent local system , , , explaining why the transform denominator has a repeated pole at .
For causal convolution on , the Laplace transform convolution theorem converts into . Since this multiplier is , inversion gives the displayed resolvent kernel. The formula remains valid for locally integrable forcing on finite intervals: substitution and the Fubini theorem reduce verification to an identity between the two continuous sine kernels. Thus a global Laplace transform is a convenient derivation, rather than an essential growth restriction on every local forcing.
A function weighting the influence of past values in a history-dependent equation. In a Volterra integral equation its convolution with the history is causal: only earlier times appear. For an integrable kernel, measures its response to a constant input. In a generalized Langevin equation, the friction memory kernel records delayed resistance to the velocity.
The iteration , successively appends terms of the displayed series. Induction verifies the iterates, and factorial denominator bounds give convergence with derivatives on compact sets. Its limit is the power series solution of , , .
For time-dependent integral kernels on a Riemannian manifold, composition also integrates over the intermediate point: . It is associative under the usual absolute-integrability hypotheses. The integration simplex gives factorial bounds for iterated convolutions of bounded kernels.
Starting from , induction integrates at the th step. Its denominator accumulates the odd integers . The factorial bound for a Volterra iterate is stronger because .
If , repeated integration produces the time-ordered simplex of volume . Thus the Neumann series converges on every finite interval, without requiring the single-step operator norm to be less than one.
The angular parts , and span the spherical harmonic basis. A radial function times therefore has definite and equal probabilities for the three outcomes.
The angular dipole is the degree-one spherical harmonic component. A real angular dipole is a function for a fixed vector . Direction-dependent observer velocity and gravitational endpoint terms can therefore be discarded from higher-multipole calculations when they have this form.
The angular monopole of a function on the sphere is its constant spherical-harmonic component, equal to its angular average. Subtracting it removes the mean temperature of a cosmic microwave background sky map without altering higher angular multipoles.
For an angular spherical harmonic of degree , the radial, tangential gradient and tangential curl families can be normalized as , and . They depend only on direction. At only the radial family is defined by these formulas.
A solid harmonic extends a spherical harmonic to a harmonic function in space with either the regular radial power or the irregular radial power . In three dimensions these are the two separated radial solutions of the Laplace equation at angular degree .
An irregular solid harmonic is harmonic on punctured three-dimensional Euclidean space and generally singular at the origin. The Kelvin transform maps a degree- regular solid harmonic to a constant multiple of its irregular counterpart.
A degree- homogeneous polynomial satisfies Euler homogeneous function theorem . The product rule gives in three dimensions. Taking gives the displayed identity and the equivalence of harmonicity on . The origin is excluded; even has a distributional Dirac delta function source there.
For the positive Laplace-Beltrami operator on the unit sphere , with , the eigenvalues are for integers . Their eigenspaces consist of restrictions of degree- harmonic polynomials and have dimensions , with the second term zero for . The Laplacian in polar coordinates gives the eigenvalue; Fischer decomposition and the Stone-Weierstrass theorem prove completeness.
The integral of three spherical harmonics on the sphere. In the conventional complex basis it is real and equals a product of two Wigner 3j symbols and . It vanishes unless the multipoles satisfy a triangle condition, is even, and . It carries the angular geometry of the reduced CMB bispectrum.
A regular solid harmonic is : it is homogeneous of degree and solves the Laplace equation. Thus and . These identities turn angular spherical harmonic expansions of displacement, density and Newtonian gravitational potential into radial equations.
For orthonormal complex spherical harmonics, . This converts an angle between two directions into a separable sum. Together with Orthogonality of Legendre polynomials, it projects rotationally invariant scattering kernels onto angular multipoles.
A spin-weight- field on an oriented sphere acquires a phase under rotation of its local tangent-frame basis. Spin-weighted spherical harmonics form the angular basis for such fields. The polarization combinations carry opposite spin weights of magnitude two; ordinary scalar functions have spin weight zero.
The angular basis for a spin-weight- field generalizes ordinary spherical harmonics. It has . For scalar-source CMB polarization about a wavevector, only survives and .
On a spin- field , the spin-raising and lowering operations are and . The intermediate spin changes after each application. For an axisymmetric scalar , either operation applied twice yields .
Here and . This follows by combining the associated Legendre function recurrence with the normalized spherical harmonic constants. It gives the adjacent-multipole couplings in a photon Boltzmann hierarchy.
A power law is a relation , with fixed constants and . For positive , any real number is allowed. Its useful feature is a simple scaling rule:The same proportional change of input produces the same proportional change of output, independently of the starting value. The exponent controls that response; the coefficient fixes the magnitude.
For example, the area of a circle is . Doubling the radius multiplies its area by four, and tripling it multiplies the area by nine. The volume of a sphere is : the same changes multiply its volume by eight and twenty-seven. The distinction explains why similarly shaped objects do not preserve their ratio of surface area to volume when their size changes.
When the output is positive, a logarithm turns the power law into a straight-line relation. Using positive reference values and ,These ratios are dimensionless quantities, so the formula also applies to physical measurements with units. Plotting both ratios on a logarithmic scale gives a line of slope . Changing a unit changes the numerical coefficient, while the exponent stays the same. Positive describes increasing values; negative describes decreasing values; gives a constant. The zero coefficient is a degenerate case with no useful logarithmic slope.
Exact scaling is stronger than regular variation. The function has a doubling ratio tending to four, but its logarithmic correction keeps growing. The diagram contrasts it with the exact power law .
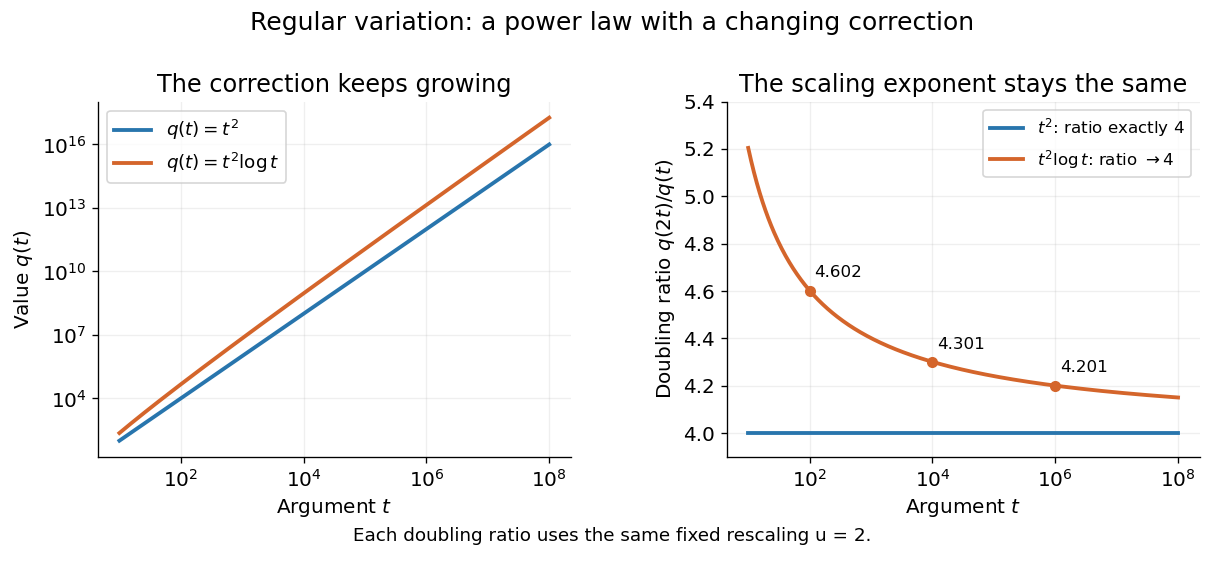
Exact quadratic scaling and a logarithmic correction have different finite doubling ratios, even though the correction leaves the limiting exponent unchanged
. Details. A power law for a probability density and a power law for a tail probability have different exponents. For a Pareto distribution with and lower endpoint one,The tail probability has exponent ; differentiating it and changing sign gives the probability density exponent . Confusing them changes the interpretation of a fitted exponent. The normalizing coefficient and lower endpoint also matter: a decreasing power law is not automatically a valid probability density over the entire positive real line.
The appearance of a line over a finite logarithmic range is evidence to investigate, rather than a proof of an exact power law or its mechanism. In their study of power-law distributions, Clauset, Shalizi and Newman combine maximum likelihood estimation, goodness-of-fit tests and comparisons with alternative models; their abstract explains why ordinary least-squares fitting can give misleading results for tail data. See Aaron Clauset, Cosma Rohilla Shalizi and M. E. J. Newman, Power-law distributions in empirical data, SIAM Review 51 (2009), 661–703. The scaling rule is mathematically exact when it defines a model; whether a dataset supports that model is a question of statistical inference.
A power-law distribution uses a power law for a probability mass function or a probability density on a specified range. For a continuous model with on and zero below it, the total integral is finite exactly when . Normalization then requires , giving a Pareto distribution with shape parameter . Discrete models instead normalize a sum. The support and normalizing coefficient are part of the model, and a power law for its tail probability uses a different exponent from its probability density.
A cored power-law density profile is finite at its centre and approaches a power law outside a core radius. A simple continuous example is for and for . The normalization is the core density. Smoothing the transition changes integrated coefficients but not convergence thresholds fixed by the outer slope.
A function has polynomial growth when for some constants . Such growth is slow enough for a locally integrable function to define a tempered distribution.
Complex dynamics studies iteration of holomorphic and rational maps, especially the division of the Riemann sphere into stable Fatou behavior and chaotic Julia behavior.
Holomorphic maps and are holomorphically conjugate if a biholomorphic coordinate change satisfies . Iterating gives , so periodic points and their exact periods correspond. Differentiating at a periodic point gives equality of return multipliers, since the nonzero derivative of cancels. Locally uniform convergence and normality transfer through the coordinate change, so it also transports Fatou sets and Julia sets. Between entire Riemann spheres the biholomorphic change is a Möbius transformation; an affine change is sufficient for many polynomial normalizations.
Two rational sphere maps are Möbius conjugate if for a Möbius transformation . This is precisely global holomorphic conjugacy between Riemann-sphere self-maps. It preserves degree, local degrees of a holomorphic map, exact periods and return periodic-orbit multipliers, and transports the Fatou set and Julia set by . Since a Möbius map and its inverse are Lipschitz on the compact sphere, this last assertion follows directly from equicontinuity of the iterate families. An affine holomorphic conjugacy is the special case where fixes infinity.
A subset is completely invariant for a rational map if . This asserts invariance in both directions, including every preimage, rather than just invariance of one chosen inverse branch. For a nonconstant sphere map, the two inclusions and already imply the equalities, because the map is surjective. The Fatou set and Julia set are completely invariant. A Fatou component need not itself be completely invariant even though the union of all components is.
A point is periodic for an iterated map if for some positive integer . Its exact period is the least such , and the distinct points form its periodic orbit. For a holomorphic map its periodic-orbit multiplier is , computed in a local coordinate; at infinity use a reciprocal coordinate. The chain rule makes this the cyclic product of derivatives along the orbit, so it is the same at every point of that orbit.
An exact -cycle consists of distinct points with , indices read modulo . Every point has exact period . The return multiplier is , computed in local charts if necessary; cyclically changing the starting point leaves it unchanged. Thus an attracting, superattracting or repelling return is of the same type at every point of the cycle. If a period- root coincides with a lower-period point at a parameter limit, multiplicity in the equation need not represent distinct points of an exact cycle.
A holomorphic periodic point is repelling when its return multiplier has modulus greater than one. It belongs to the Julia set: if the iterates were normal near it, a subsequence of the return iterates, all fixing the point, would converge locally uniformly in the spherical metric. Near their fixed finite value the limit lies in a finite coordinate chart, so Cauchy's derivative estimate would bound their derivatives at the point. Those derivatives are the successive powers of the multiplier and are unbounded. The same argument in a reciprocal coordinate handles infinity.
A holomorphic periodic point is attracting when its return multiplier has modulus strictly less than one. For the return map , choose a local coordinate at the fixed point and a number strictly between and one. Taylor expansion gives on a sufficiently small disc. It maps that disc into itself, and successive returns converge uniformly to there. Composing with the finitely many intervening maps gives locally uniform convergence to the periodic orbit and places its basin in the Fatou set.
A holomorphic periodic point is superattracting if its return multiplier is zero. The return map then has local expansion with . This implies a strict contraction on a sufficiently small disc and rapid convergence of returns. Infinity is superattracting for every polynomial of degree at least two: the reciprocal-coordinate return has a zero of order equal to the polynomial degree.
For , the Mandelbrot set is . Thus it records the nonescaping finite critical orbit. The connected Julia set criterion for a polynomial says that the corresponding filled Julia set is connected exactly for these quadratic parameters. Parameters with an attracting fixed point form the main cardioid: its multiplier gives the fixed point and parameter , with . Its boundary has a cusp at . There the critical orbit increases along the real interval to the parabolic fixed point , so the cusp belongs to the set. The real section extends from to ; the familiar period-two bulb is attached at .
The period-two bulb is the open disc of quadratic parameters with an attracting exact two-cycle. The points in that cycle are roots of , whose product is . Its multiplier is therefore , giving precisely the disc inequality. At the two roots merge into the fixed point , whose original multiplier is minus one; the second iterate has multiplier one and a triple fixed-point root. This boundary point is the attachment to the main cardioid.
The main cardioid consists of quadratic parameters with an attracting fixed point. If that fixed point has multiplier , then it is and , . The map is injective on the open unit disc: equality of two parameter values forces either equal multipliers or their sum to be two, impossible for distinct interior multipliers. Its boundary is the cardioid obtained from . At the parameter derivative vanishes, giving the cusp . Parameters just to the real right of that cusp have monotonically escaping critical orbits, while the cusp's critical orbit tends to , so it is on the Mandelbrot set boundary.
A family of holomorphic or meromorphic maps is normal when every sequence has a subsequence converging locally uniformly in the spherical metric, possibly to infinity.
For a holomorphic normal family, limits are holomorphic or identically infinity. A uniform bound at one interior point excludes infinity on its connected domain. Every sequence therefore has a finite locally uniform subsequential limit. The Cauchy integral formula makes the derivatives converge locally uniformly too, so the derivative family is normal. Without the point bound this can fail: tends uniformly to infinity on the unit disk, whereas its derivatives are not normal at zero.
Choose a countable cover by connected disks on which a family is normal. From any sequence extract successive subsequences converging on each disk and use the diagonal sequence. The limits agree on overlaps; a finite holomorphic limit and infinity cannot agree on a nonempty overlap. Connectedness therefore gives one global type of limit, and finite compact subcovers give locally uniform convergence. This proves normality of the family on the whole domain from normality near every point.
If a bounded holomorphic function on the complex upper half-plane has as , the rescaled functions form a normal family. Every subsequential limit equals on the imaginary axis, hence everywhere by the identity theorem for holomorphic functions. The entire sequence converges locally uniformly to . For a nontangential sequence , put ; then remains in a fixed compact subset of the half-plane. This gives . The bounded example shows that unrestricted boundary convergence can fail.
// Destination: analysis.bigb
A family of meromorphic functions on a domain that omits three fixed points of the Riemann sphere is normal. For holomorphic functions with values in the complex plane, omitting two fixed values suffices.
The Fatou set of a rational map is the largest open subset of the Riemann sphere on which its iterates form a normal family. Its complement is the Julia set.
A Fatou component is a connected component of the Fatou set of a rational map. It is open. A rational map sends each Fatou component onto another one: complete invariance of the Fatou set puts it inside the inverse image of the target component; its maximal connectedness makes it one full inverse-image component. Restricting the globally proper sphere map to such a component is proper, since the inverse image of a compact subset intersected with the component is closed in a compact set. Its image is both open and closed in the connected target component, hence the whole target. A component is periodic if some iterate returns it to itself.
A Herman ring is a doubly connected periodic Fatou component on which the first-return map is holomorphically conjugate to an irrational rotation of an annulus . Compactness of the circle of rotation factors proves normality of the return iterates, and the finitely many intervening iterates preserve normality. It is the annular rotation-domain counterpart of a Siegel disc.
A Siegel disc is a simply connected periodic Fatou component on which the first-return map is holomorphically conjugate to an irrational rotation of the unit disc: , with . Its return iterates are normal because any sequence of rotation factors has a convergent subsequence in the unit circle, giving locally uniform limits after conjugation. The iterates generally do not converge to a constant. This is a rotation domain, illustrating stability without attraction.
Suppose a Fatou component satisfies , and some has . Every connected component of maps properly and surjectively to : properness follows by intersecting compact preimages with the relatively closed component; openness and closedness then give surjectivity. Such a component must meet the entire fiber over , which lies in . Since is itself one inverse-image component, there can be no other. Hence and , proving complete invariance.
A periodic Fatou component of a rational map is an immediate attracting basin, an immediate parabolic basin, a Siegel disc, or a Herman ring. Attracting and parabolic basins capture critical orbits, while the boundaries of rotation domains lie in the closure of the postcritical set.
Articles were limited to the first 100 out of 7376 total.
Articles by others on the same topic


Analysis is the process of breaking down complex information or concepts into smaller, more manageable components to better understand, interpret, and evaluate them. It can be applied in various contexts, including: 1. **Data Analysis**: Examining data sets to extract meaningful insights, identify patterns, and make informed decisions. This often involves statistical methods, data visualization, and interpretation of results.