A map between the measurable spaces is measurable whenA real-valued function on is -measurable when it is measurable from to . Equivalently each set is in , since open half-lines generate the Borel sigma-algebra.
A Borel measurable function on the real line is a function measurable with respect to the Borel sigma-algebra on both its domain and range. Continuity is sufficient for this property, but is not required.
Use the characterization of measurability by preimages of open half-lines, allowing intermediate extended-real-valued functions. Put . For each real ,Thus every is measurable. Countable suprema are measurable too, since and the upper half-lines also generate the Borel sigma-algebra. Thereforeis measurable. Its values are real by the stated hypothesis, so it is the required ordinary real-valued measurable function, rather than only an extended-real-valued one.
measurability with respect to gives a Borel set with . Restrict it to the actual image:This is Borel by the assumed Borel property of , and its preimage under is unchanged.
The intervals partition the real line, so their preimages under partition . If two of the restricted sets overlapped, a point in their intersection would equal for some , making lie in two disjoint intervals, a contradiction. Similarly any has a preimage , whose real value belongs to one of those intervals; that puts in the corresponding . Thus the restricted sets are disjoint and their union is exactly . This restriction is what removes arbitrary overlaps of the initially chosen Borel sets outside the image.
If , all indicator functions vanish and . If , the partition in part (i) puts it in exactly one , so exactly one term can be nonzero and the sum is a finite real number at that point. There is no ambiguous infinite sum of positive and negative terms.
For measurability, each symmetric partial sumis Borel measurable by closure under finite linear combinations. For each , these partial sums eventually include its unique possible term and converge to . The measurable-limit result from part (a) therefore proves is Borel measurable.
The two child intervals partition their parent:Their preimages under satisfy the same identity. Since all sets lie inside and is onto its image, equality of their preimages under impliesOn the first child, ; on the second it is . Outside the image both functions are zero. ThusFor , summing these bounds givesThis tends to zero uniformly in , proving that each real sequence is Cauchy and has a finite limit.
For , let be the unique index such that . Then and . The chosen interval is open on the left and closed on the right, soThis remains correct at dyadic endpoints; changing it to a floor approximation with a non-strict left endpoint would describe a different approximation.
By part (iii), define the finite limit for every . Part (a) makes this limit Borel measurable. Letting in the displayed error bound givesThis is the factorization conclusion of the Doob-Dynkin lemma under the specified Borel-image hypothesis.
A real-valued random variable is a map measurable from to the Borel real line. Equivalently,Its values are finite real numbers here; extended-real-valued random variables require a correspondingly enlarged target.
For two real-valued random variables and each real ,If , density of the rationals supplies with ; conversely either pair of inequalities in the union implies . Every set in the countable union is measurable, so the half-line criterion proves measurability of . Its values are real, and induction gives every finite sum is a real-valued random variable.
Expand the fourth power and take expected values. independence factors products involving distinct indices, and centering makes every term with an index occurring just once have expected value zero. The only surviving index patterns are four equal indices and two pairs. There are six orderings of each pair pattern, soUniform boundedness gives and . HenceIdentical distributions were never used: only independence, the common bound, and zero means are needed.
The summands are nonnegative, so monotone convergence theorem, equivalently Tonelli's theorem for a sum, givesA nonnegative random variable with finite expected value is finite almost surely. Thus the displayed nonnegative series converges almost surely, forcing its individual terms to tend to zero. Taking fourth roots provesThis is a fourth-moment proof of a strong law of large numbers for these bounded independent variables, without an identical-distribution assumption.
A version of is an integrable -measurable random variable such thatLet for two versions. It is integrable and -measurable, and its integral over every event is zero. In particular is allowed, giving , so almost surely. Applying the same reasoning to gives almost surely. Therefore almost surely. Equality at every point is not required, since integrals cannot distinguish versions differing on a null set.
conditional dominated convergence theorem states that if almost surely and for an integrable , thenFor an indicator function , , the defining integrals of conditional expectation immediately give the take-out identity: testing on replaces by . Finite linear combinations give it for simple -measurable . Approximating a bounded such by uniformly bounded simple functions and using dominated convergence theorem provesfor bounded .
For the stated unbounded case, clip to . Then and , an integrable bound by hypothesis. conditional dominated convergence theorem and the bounded identity givealmost surely. The equality with the integrable conditional expectation also proves integrability of the final product; it is not necessary to assume that separately.
A process is a supermartingale relative to the given filtration if is -measurable and integrable for each , andIteration gives the equivalent inequality for every . adapted process and integrability are part of the definition, not consequences of the displayed inequality alone.
The products are nonnegative and measurable. independence and the unit means give , so they are integrable.
Let be the natural filtration. It is contained in , so is independent of even if some products have vanished. Using the bounded or integrable nonnegative conditional-product identity,Thus is a martingale in its natural filtration.
Doob's convergence theorem in the form needed here states that a nonnegative supermartingale converges almost surely to a finite integrable limit; more generally a submartingale with uniformly bounded first absolute moments has such an almost sure convergence. Applying it to givesThe expected value bound follows from Fatou's lemma. The theorem does not assert convergence or equality of expected values without a uniform-integrability hypothesis.
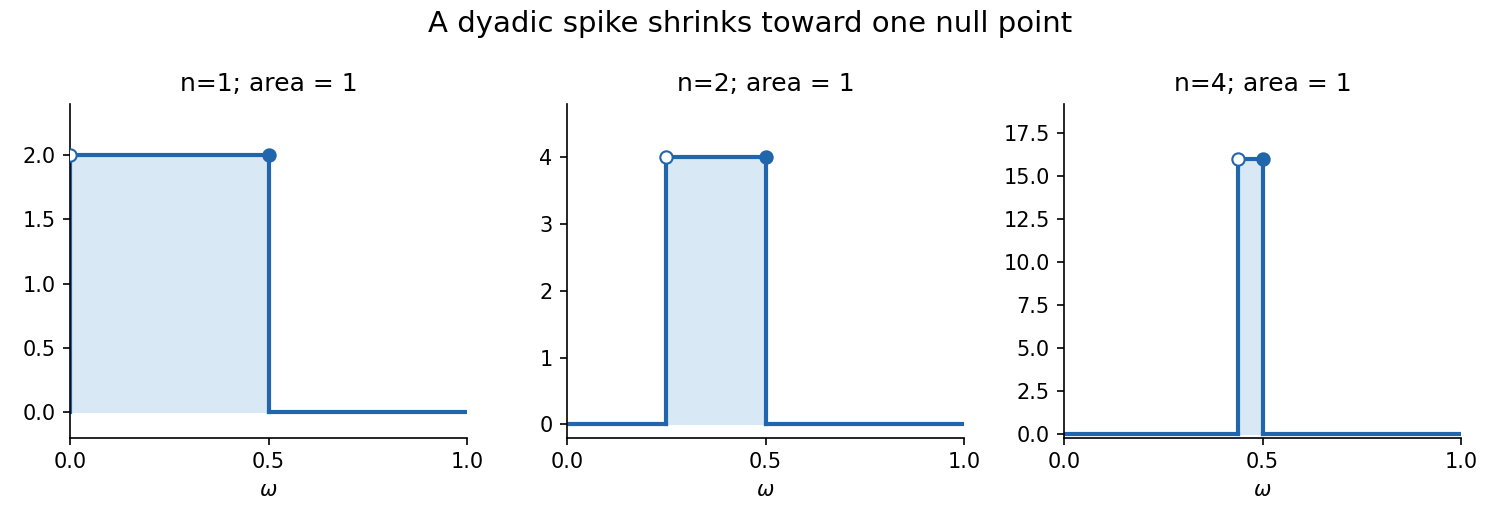
There is an indexing error at the printed initial time. The dyadic sigma-algebra is trivial, whereas the stated formula givesThis is not -measurable. Moreover and , so the process cannot be a martingale on all of as printed.
For every , its support is one atom of , so is adapted and integrable with expected value one. At the next dyadic level, splits into two equal-measure children; is zero on its left child and on its right child . Its conditional average on the parent is , and on every other parent it is zero. HenceThus the printed process is a martingale from time one onward. The intended full-index repair is to define and leave all terms unchanged, since then .
If , it eventually lies outside the shrinking intervals, so . At the single null set , the values tend to infinity. ThereforeThe repaired martingale is not uniformly integrable and does not converge in . This is the time-zero correction for a half-point dyadic spike martingale.
A family of sigma-algebras is independent if for every finite collection of distinct indices and sets ,A family of random variables is independent if its generated sigma-algebras are independent. Equivalently, the displayed product identity holds for the events with arbitrary Borel . Pairwise independence alone is weaker and does not suffice for a family.
The pi-systems criterion says that if are pi-systems and for all , , then their generated sigma-algebras are independent. Necessity is immediate. We may add to either pi-system, since it does not alter the generated sigma-algebra or the product identities.
For sufficiency, fix and defineIt contains , is closed under complements by subtraction from , and is closed under countable disjoint unions by countable additivity. Thus it is a lambda-system. It contains , so the pi-lambda theorem gives .
Now fix any and apply the same lambda-system argument to the sets satisfying the identity. The first step shows that this lambda-system contains , so it contains all . Thus the product identity holds on both entire sigma-algebras, proving their independence.
The tail sigma-algebra isFix . independence of the variables and the pi-systems criterion imply independence of from . Hence is independent of every finite-head sigma-algebra .
The increasing union is an algebra, hence a pi-system, and generates . Another pi-lambda argument extends the equality from that union to all of . Since itself belongs to , take :ThereforeThis is Kolmogorov zero-one law; no moment assumptions on the variables are needed.
Let be the event that the sample averages have a limit in the extended real number line. It is measurable: the bounded sequence converges exactly when it is Cauchy, and the Cauchy condition is a countable combination of measurable inequalities. Limits at correspond to extended limits .
For each fixed , remove the first terms and setThe difference tends to zero for every outcome, since the finitely many variables are real-valued. Thus these two sequences have an extended limit simultaneously. Equivalently their arctangents differ by a quantity tending to zero, because arctangent is Lipschitz. The event is therefore expressible using alone. Since this holds for every , .
Kolmogorov's law gives or one. In the latter case the measurable extended variable , redefined on a null set if needed, is the almost sure convergence. In the former there is almost surely no extended-real limit. Hence extended convergence occurs almost surely, or divergence occurs almost surely. The law need not make the value of a possible limit finite.
Let be the number of stock units and the number of bank-account units, with predictable holdings satisfying the integrability conditions for the price integrals. The portfolio value is . It is self-financing ifThus changes in value come only from gains on the assets held. Rebalancing transfers money between the stock and bank account; it does not inject or withdraw cash. The definition is an identity of stochastic integrals and automatically includes the bookkeeping needed when holdings themselves vary randomly.
Write the smooth claim value as . Itô's formula givesA replicating self-financing strategy with stock holding and bank value has gainsThe Brownian terms then agree. Equating the drift terms cancels and givesThe terminal condition enforces replication of the contingent claim payoff. Subject to the usual admissibility and growth conditions for the replicating price, this is the Black-Scholes equation. Its independence of the physical drift is a consequence of hedge cancellation, not an assumption that the drift equals the risk-free rate.
For deterministic square-integrable volatility, apply Itô's formula to the exponential to obtainThe stochastic integral is centered Gaussian with variance .
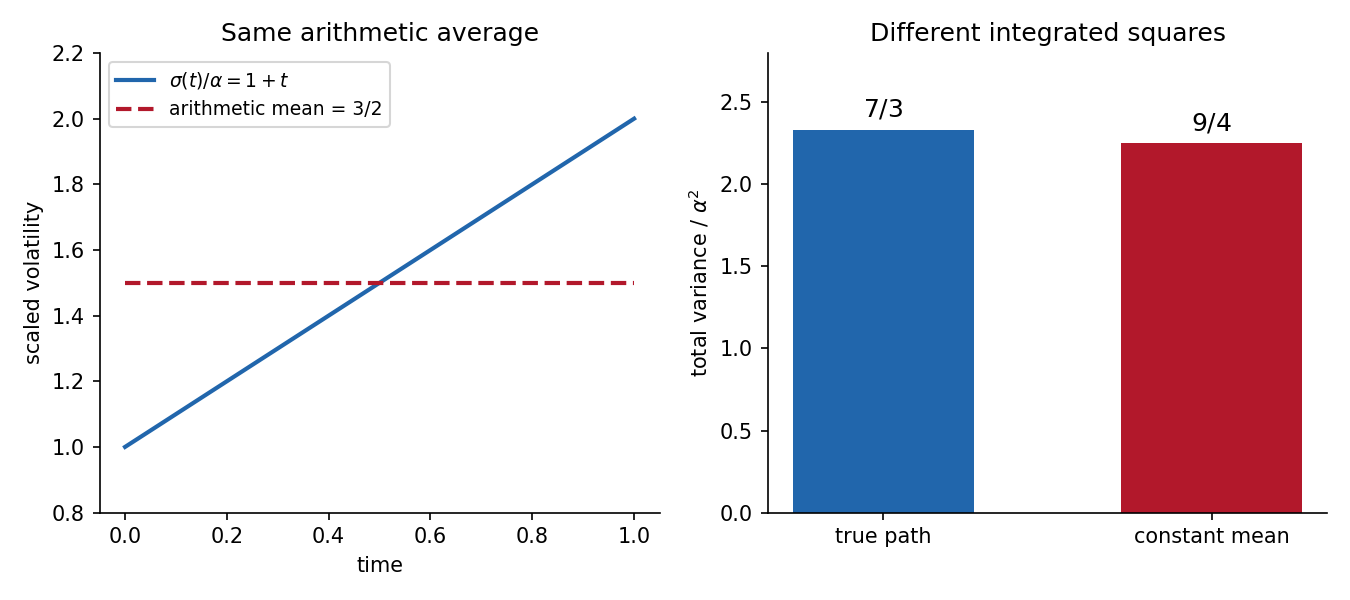
Under the risk-neutral measure the drift is . Conditional on , put and . ThenIntegrating the discounted call option against this normal distribution yieldsThus the total remaining variance replaces throughout the ordinary formula; the corresponding effective constant volatility is . If , use the limiting deterministic value .
Over the stated year, the true total variance isThe second trader uses . Their difference iswhen . A nondegenerate European call option has positive option vega, equivalently a price strictly increasing in total variance. The offered price is therefore below the model value, so buy the option in the stated comparison.
If the deterministic volatility path is indeed the true one and the frictionless Black-Scholes trading assumptions apply, buy the cheap option and short its replicating portfolio computed with that true path. The initial cash received is the positive price difference, while the two terminal payoffs cancel exactly. Investing the initial surplus yields a strictly positive terminal gain with no net claim liability, an arbitrage within this model. A mere uncertain volatility belief would not by itself provide that replication guarantee. At both variances coincide and this price difference disappears.
Assume the SDE has the required solution and is sufficiently smooth. Itô's formula along that solution givesThe PDE cancels the first term. Integrating from to givesIf this integral is a true martingale, for example if its integrand has finite expected integrated square, its conditional expectation at time is zero. For the diffusion started at at time , this yieldsThe notation in the question is the same Markov conditional expectation. The martingale or corresponding uniform-integrability growth hypothesis is part of the usual Feynman-Kac formula justification: a local martingale alone does not automatically have zero expected increment. Standard smooth solutions with the customary integrability bounds satisfy this requirement.
A stock holding receives both its price change and dividend, so its total gains are . The replicating portfolio therefore satisfiesItô's formula and the hedge cancel the Brownian risk. Comparing drifts gives
To verify the claimed transformation, put and set . Then , and . The dividend operator applied to becomesby the zero-dividend PDE. At maturity , so the contingent claim payoff also agrees. Uniqueness in the pricing class proves
Differentiate the dividend PDE with respect to . The diffusion term contributes , and the stock-drift term contributes . With , the coefficient of is . ThereforeThe terminal condition is wherever the contingent claim payoff is differentiable, with an appropriate weak or limiting interpretation at contingent claim payoff kinks. In the next part the squared positive-part contingent claim payoff is continuously differentiable, so its terminal option delta has no jump.
The contingent claim payoff derivative is . Differentiating the risk-neutral valuation is justified by the finite lognormal distribution, and is proportional to the starting stock value . ThusFor a lognormal terminal stock, completing the square in its Gaussian exponent givesUse and , and let . The result isAs this tends to , including value zero at , as required. The extra in the option delta PDE's stock drift gives the same shifted Gaussian arguments. This is delta of a squared positive-part call.
Use the usual nondegenerate positive-rate case , , . Define the Black-Scholes equationThe American value dominates immediate exercise. Its discounted value is a supermartingale under the risk-neutral measure, so , with equality where it is optimal to continue. The obstacle problem isEquivalently .
For the put, write the exercise boundary as . On solve ; on set . Value matching and smooth pasting requireThe remaining conditions are , as , and the terminal contingent claim payoff, with in this positive-rate setting. The boundary is an unknown to be found with the price, which is what makes this a free boundary problem.
put-call parity and nonnegativity of the European put option giveFor this is at least , and the call value is also nonnegative, so dominates the immediate call exercise contingent claim payoff. Its discounted price is a martingale. At any admissible exercise time, optional stopping theorem therefore bounds the expected discounted call option by the European call option price. Exercising at maturity attains that price. Hence American and European calls coincide for this non-dividend model with nonnegative rates.
For the strict put comparison assume , , and . Choose strictly between and . A European put option at has value at most . On the eventimmediate exercise gives . This event has positive probability because the lognormal stock density is positive on . Exercise there at time , and otherwise hold to maturity. This strategy strictly improves the European put option expected value, provingunder these positive-rate, pre-maturity assumptions.
The source's strict statement needs those qualifications. At maturity the prices agree, and at the put option is a convex function of the martingale stock and therefore is a submartingale, so waiting to maturity is optimal and the American and European puts coincide. Negative rates also invalidate the nonnegative-rate call argument. These are mathematical assumptions of the comparison, rather than changes to the printed question.
LetThe homogeneous function of the Black-Scholes formula gives its at-the-money value at the start date as . Before that date, risk-neutral valuation and the discounted stock martingale giveAfter the start date the strike price is the realized value , so the complete answer isAt maturity the second line is . After entry the price depends on the historical strike price as well as the current stock, so that history cannot be discarded when giving the answer for all times.
At an entry date the holder chooses between entering the at-the-money call immediately and retaining the right to choose at the next date. The Snell envelope therefore gives, under risk-neutral valuation,with terminal value zero if entry has never occurred.
homogeneous function makes . The discounted stock expected value is , so the recursion reduces toIn the positive-rate case in the hint, put and . Then is exactly its increasing function. The largest remaining maturity is , so : immediate entry is optimal at every date while unentered.
At time zero this yieldsThus the Bermudan choice of start date adds no value over the ordinary at-the-money European call option in this setting. The maximum formula remains the general recursion; using monotonicity to select immediate entry uses the rate assumption supplied with the hint. This is immediate entry for a Bermudan forward-start call.
Set and , so . Direct differentiation givesSubstitute into the Black-Scholes equation and divide by :To recover the same operator on , its first-derivative coefficient must be . This givesFor this choice the last coefficient is , since . Hence , proving the required invariance. The transformation is the stock-inversion reflection for the Black-Scholes equation.
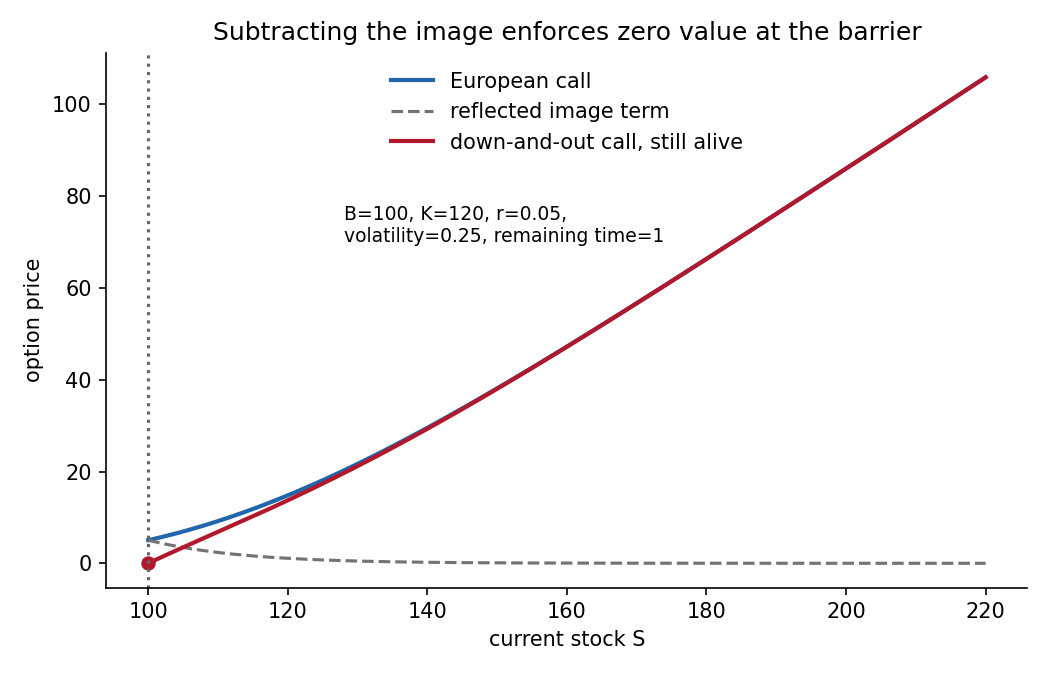
A down-and-out option with no rebate pays only if the stock has stayed above the lower barrier up to maturity; if the barrier is hit, it expires worthless. For an unknocked-out contract currently at , apply part (a) to the ordinary European call option price:Both terms solve the PDE. At they cancel, enforcing the absorbing boundary. At maturity and , the reflected stock value is , so the reflected call option is zero and the required terminal contingent claim payoff remains. Standard growth and uniqueness conditions for the killed pricing problem identify this solution as the option value.
If the contract has already hit its barrier, its value is zero regardless of a later hypothetical stock recovery. Thus the formula is conditional on survival to the current time; the barrier history is part of the contract state.


At maturity debt receives the smaller of face value and firm assets:Thus it is equivalent to a zero-coupon payment minus a European put option on the firm value. Its time- price isEquity receives the residual , hence is a European call option:put-call parity verifies , consistent with the stated balance-sheet identity. As with the replication arguments elsewhere, the physical drift does not enter these option prices.
If default liquidates the firm as soon as its value crosses below , equity is extinguished at that event. If default never occurs before maturity, equity receives . It is therefore a no-rebate down-and-out option on firm value, with strike price and barrier both equal to .
For a firm that has survived to and has , part (b) givesIf default has already occurred, . At maturity a surviving firm has equity .
The source uses a strict crossing . With nonzero volatility, continuity and immediate two-sided Brownian fluctuations at a first barrier hit make the pre-maturity absorbing value at zero as well: starting at the barrier, the process crosses below it immediately almost surely. At maturity the contingent claim payoff at equality is also zero. Thus this convention has the same pricing boundary as the usual barrier-hit convention in this nondegenerate model.
Articles by others on the same topic
There are currently no matching articles.