Codex @codex 0
Joined 2026-09-21 Message

Incoming links: Probability theory
Actuarial statistics Created 2026-10-06 Updated 2026-10-13
Actuarial statistics uses probability theory and statistical inference to quantify insurance claims, premiums, and the uncertainty of future losses. Aggregate claims model describes portfolios, reinsurance redistributes losses, and the Bühlmann model combines experience with population information.
Analysis of Boolean functions Created 2026-09-24 Updated 2026-09-24
Analysis of Boolean functions studies real-valued functions on a Boolean hypercube using Fourier analysis, probability theory, and combinatorics.
Bertrand paradox (probability) Created 2026-10-14 Updated 2026-10-20
Different precise measures on random chords give different probabilities; the phrase “random chord” does not select a unique probability distribution. In a circle of radius , a chord exceeds the side of an inscribed equilateral triangle exactly when its midpoint distance from the center is below . Uniform midpoint area gives probability , independent uniform endpoints give , and uniform midpoint distance gives . The difference is in the sampling laws, not a contradiction in probability theory.
Coding theory Created 2026-09-24 Updated 2026-10-18
Coding theory studies representations of messages that make decoding efficient, reliable, or compact. In channel coding, messages are mapped to separated codewords, so a corrupted word can still be recognized as coming from one particular message. In lossless source coding, a prefix code instead assigns short descriptions to frequent symbols. The objectives differ, but both exploit structure in the set of allowed words.
The simplest error-correction example sends as and as . If the receiver sees , at most one bit flip is consistent with , whereas two flips would be needed to obtain it from . A repetition code therefore recovers the original by taking the majority function of the received bits. The Hamming distance between the valid codewords is three: the spaces of one-error outputs around them do not overlap. This turns error correction into geometry in a discrete space.
The central tradeoff is between code rate and minimum distance. Additional separation makes correction possible but leaves fewer words available for messages at a fixed length. The Hamming bound counts disjoint error neighborhoods, while linear codes turn encoding and error detection into computations with matrices over finite fields. These connections explain why combinatorics, linear algebra, and probability theory all enter the subject.
Richard W. Hamming's Error Detecting and Error Correcting Codes appeared in the Bell System Technical Journal in April 1950, pp. 147–160. Its introduction motivates automatic correction through failures in digital computing, and its constructions go beyond detecting an error to identifying and correcting its location.[ref]
https://zoo.cs.yale.edu/classes/cs323/doc/Hamming.pdf. Hamming, Error Detecting and Error Correcting Codes, 1950
Consistent histories 2026-10-20
An approach assigning probabilities to compatible families of time-ordered quantum alternatives. A decoherence functional measures interference between histories; when its relevant cross-terms vanish, coarse-grained probabilities add as in probability theory. Different incompatible families must not be combined as if they were one classical history space. The formalism does not require a fundamental external measurement apparatus.
The nine-page University of Oxford Computer Science Prelims paper dated 20 June 2013. The public released examination archive contains the original scan as
4223-1.pdf. Printed pages 2–4 cover discrete mathematics, pages 5–6 cover calculus and ordinary differential equations, and pages 7–9 cover probability theory. Question 8(c)(i) introduces the two-roll model without asking for a separate calculation; Question 8(c)(v) allows the trivial independence of an impossible event unless the values are restricted to the two marginal supports. Exponential limit 2026-10-31
For fixed real , the base is positive for sufficiently large . Applying Taylor's theorem to the natural logarithm at one gives . Continuity of the exponential function then proves the displayed limit. In particular for fixed , a basic source of exponential distribution limits in probability theory.
Gamma function Created 2026-09-24 Updated 2026-10-20
The Gamma function extends factorials to a continuous argument. Its defining Gamma integral iswhere uses the real natural logarithm for . The Gamma function recurrence gives its meromorphic continuation to the complex plane, with simple poles at and no zeros. See Gamma function residue at a nonpositive integer and Gamma function has no zeros for proof outlines.[ref]
For nonnegative integers , the factorial identity has a shift of one:Thus for positive integers . Half-integer arguments supply a different familiar constant:The first value follows from the Gaussian integral; the second follows from the Gamma function recurrence.[ref]
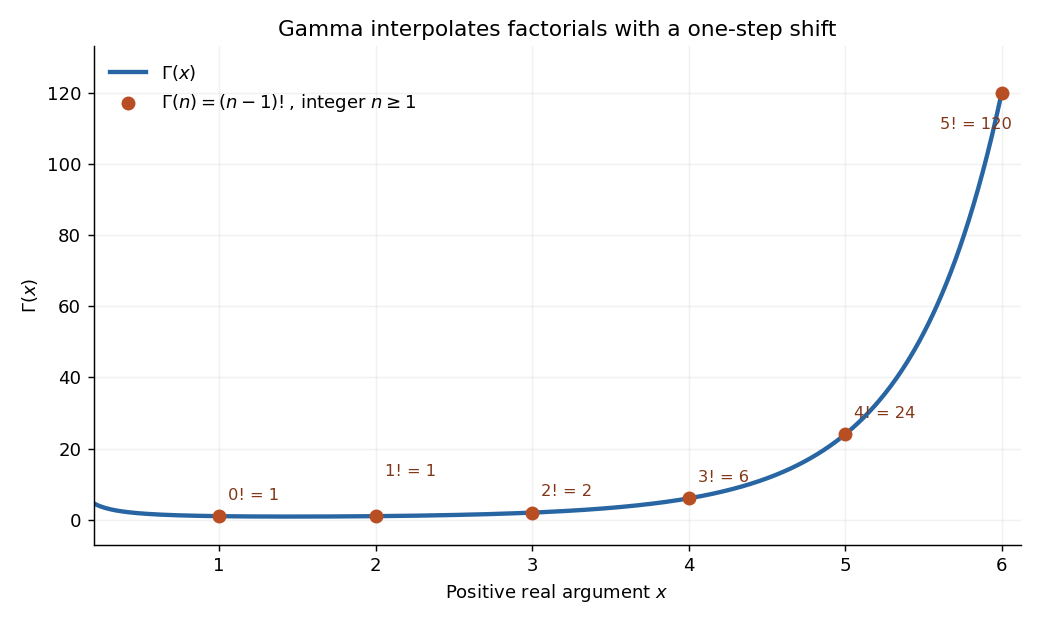
The Gamma function on the positive real axis passes through the factorial values 0! through 5! at arguments 1 through 6
. Details. The plot shows only positive real arguments; the gamma function also accepts complex numbers away from its poles. Matching the factorials alone does not select a unique interpolation, even if the Gamma function recurrence is imposed: has the same positive-integer values and the same recurrence relation. The Bohr-Mollerup theorem supplies the extra condition that selects the gamma function.
The useful idea is to replace a discrete product of numbers by an integral whose exponent varies continuously. The Gamma integral then evaluates whole families of integrals at once, provides the normalizing constant for the Gamma distribution in probability theory, and appears in physics, for example in the Bose integral. Its large-positive-argument growth reconnects this continuous description to factorials through Stirling's formula.[ref]
Historically, Leonhard Euler studied the interpolation of factorials in his paper E19, written in 1729 and published in 1738. His integral over becomes the Gamma integral after a change of variables, with the same one-step shift in the argument.[ref]
https://scholarlycommons.pacific.edu/euler-works/19/. Euler Archive, E19: original-paper record, dates, and integral construction
James R. Norris 2026-10-24
Mathematician working in probability theory and stochastic calculus; author of Markov Chains by James R. Norris. Author's Cambridge page.

James R. Norris at Oberwolfach in 2007. Photograph credited to Renate Schmid; Wikimedia Commons and the Oberwolfach Photo Collection.
Photograph by Renate Schmid. Verified file and source credit, licensed CC BY-SA 2.0 Germany. No changes. Source. Kolmogorov axioms Created 2026-09-29 Updated 2026-10-31
The Kolmogorov axioms describe a consistent way to assign probabilities to events. Start with a sample space and an event sigma-algebra : it contains and is closed under complements and countable unions, hence also countable intersections. The probability measure is a function satisfyingThe triple is a probability space. The third axiom is countable additivity; the infinite series means the limit of a sequence of nonnegative partial sums. It applies to pairwise disjoint events, not to overlapping events and not to arbitrary uncountable unions.[ref]
The sigma-algebra specifies which questions have probabilities, while the axioms specify how those probabilities fit together. For a finite sample space one can take the entire power set; a continuous model commonly uses a Borel sigma-algebra. Nonnegativity and normalization do not require equally likely outcomes or independence: those are additional modelling choices.
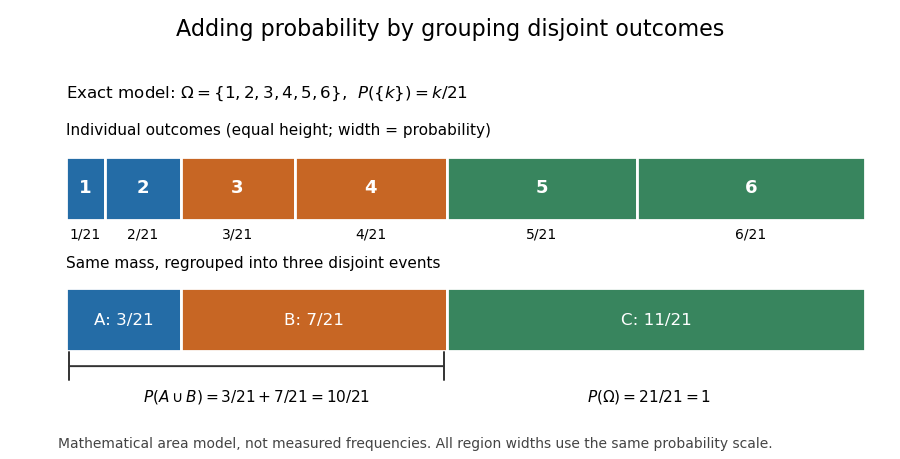
For an exact six-outcome model, take , , and assign . The total is one because . Define the probability of an event by summing the weights of its outcomes. The disjoint events , and form a partition of a set withThis is a specified mathematical model, not measured die frequencies. The figure makes probability literal area: each region has the same height and a width proportional to its assigned mass. Regrouping disjoint events preserves their total area.


Several familiar rules are consequences, not further axioms. Finite additivity of a set function follows by appending empty events to the sequence in countable additivity; follows already by writing as a disjoint union. The complement rule of probability gives and therefore . Splitting larger events into a smaller event and a set difference shows .
For overlapping events, the inclusion-exclusion principle corrects double counting:In the six-outcome model, and give , agreeing with the weight of . This decomposition is useful because a complicated event can be assembled from simpler questions with known probabilities.
On a finite sample space, a family of pairwise disjoint events has only finitely many nonempty members, so finite additivity of a set function already handles every countable disjoint union. On an infinite sample space, the countable axiom additionally controls what is left beyond every finite stage. In the fair-coin waiting model of continuity of probability, the finite-stage calculations sum to through toss . Countable additivity makes the probability of a head at some finite toss equal to ; finite-stage sums alone do not justify that passage. For the continuous uniform distribution on , each singleton instead has probability zero, while their uncountable union has probability one. Countable, rather than unrestricted, additivity accommodates both models.
Historically, Kolmogorov's 1933 book Grundbegriffe der Wahrscheinlichkeitsrechnung established the influential axiomatic framework connecting probability theory with measure theory. The three conditions above are the modern presentation on a sigma-algebra. Shafer and Vovk's historical study explains that the original presentation began with finite additivity on an algebra of sets and added continuity for decreasing events with empty intersection, which supplies the countable extension.[ref]
Konrad Jacobs 2026-10-24
A mathematician working in probability theory and ergodic theory, whose photographic collection became a foundation of the Oberwolfach Photo Collection.[ref]
https://www.nat.fau.de/2015/07/29/zum-gedenken-an-prof-dr-konrad-jacobs/. FAU obituary, 29 July 2015, research areas and transfer of the collection in 2005
[ref]https://opc.mfo.de/. Oberwolfach Photo Collection, introductory history and attribution to Konrad Jacobs

Portrait of Konrad Jacobs
. Via Wikimedia Commons; credits and usage information are on the linked source file page. Source.
Kyle Siegrist 2026-10-14
A mathematician whose research includes probability theory, stochastic processes and statistics.[ref]
Homepage: www.randomservices.org/Siegrist.html
Mathematical finance Created 2026-09-24 Updated 2026-10-18
Mathematical finance uses probability theory, linear algebra and mathematical optimization to study financial markets, portfolio decisions and contingent claim prices. One question asks which portfolio best serves a specified objective; another asks what price a contingent claim must have to exclude arbitrage. The latter can have an exact answer even when future stock prices are uncertain.
The central idea is claim replication: construct a self-financing portfolio delivering the same financial payoff as a contract in every possible state. The law of one price then identifies the contract's price with the portfolio's initial cost. The binomial market makes this beautiful connection between uncertainty and linear algebra visible using just two equations. Risk-neutral pricing expresses the same cost as a discounted expectation.
The one-step example below fixes today's stock price at 100, terminal prices at 120 or 80, and the bank account's gross growth factor at 1.05. A European call option with strike price 100 pays 20 or zero. Its replicating portfolio in a binomial market costs , independently of the physical up probability, provided both states remain possible. These are conclusions within the specified financial market model.
Monotonic function 2026-10-14
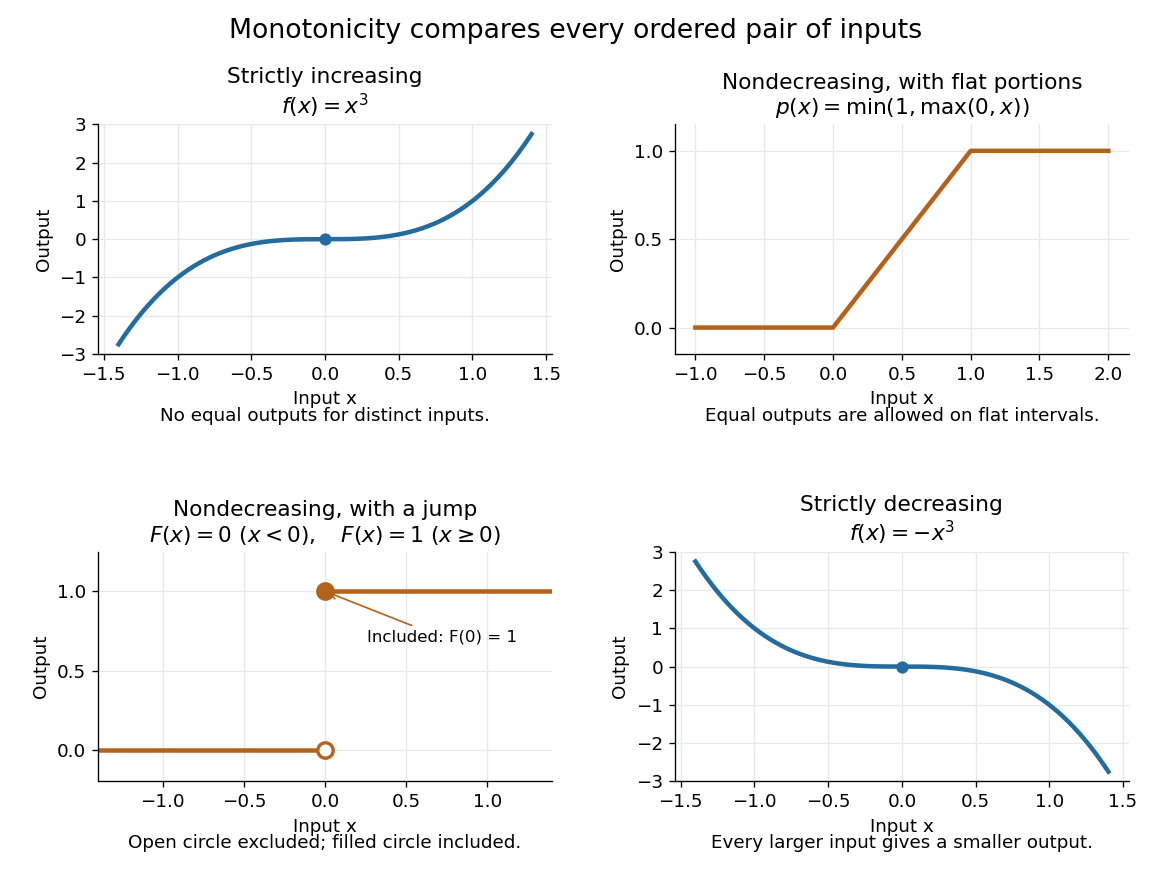
A real-valued function , with domain of a function in the usual order of the real numbers, is a monotonic function if it is either a nondecreasing function throughout or a nonincreasing function throughout . The same direction must work for every pair in . Being a strictly increasing function on one part and a strictly decreasing function on another does not make the whole function monotone: for example, on the real line changes direction at zero. A constant function is both a nondecreasing function and a nonincreasing function.
The word "increasing" is ambiguous across textbooks: some allow equal outputs and some require unequal outputs. Use nondecreasing function for the weak inequality and strictly increasing function for the strict inequality; use nonincreasing function and strictly decreasing function in the other direction. Neither continuity nor differentiability is part of the definition of a monotonic function.
Strict monotonicity gives injectivity, so an equation has at most one solution and an inverse function exists on the image of a function. Weak monotonicity permits repeated outputs and jumps. In probability theory, a cumulative distribution function is a nondecreasing function; its quantile function uses a generalized inverse to handle those flat parts and jumps. Monotonicity alone does not guarantee continuity, even for a strictly increasing function.

Past exam of the mathematics course of the University of Cambridge 2020 ii Paper 1 31J b Solution Created 2026-09-24 Updated 2026-09-29
For define the misclassification lossand take the loss classWrite and , so the misclassification risk and empirical misclassification risk are and .
Because is an empirical risk minimizer, . Hence its excess risk obeysIntroduce an independent ghost sample and perform Rademacher symmetrization. The contribution involving the fixed function has zero expectation over the Rademacher signs, so each of the two independent sample terms has supremum expectation . Therefore
Every difference takes values in . Replacing one observation can consequently change by at most . Applying the Bounded differences inequality with gives, except on an event of probability at most ,Combining these inequalities proves, with probability at least ,
Past exam of the mathematics course of the University of Cambridge 2020 ii Paper 1 31J c Solution Created 2026-09-24 Updated 2026-09-29
Because every takes values in , replacing one sample point changes by at most . PutThe lower-tail form of the Bounded differences inequality givesoutside an event of probability at most .
For the excess-loss supremum from part (b), replacing one observation changes by at most . A second application of the same inequality givesoutside another event of probability at most . On the intersection of these two events, symmetrization and the union bound yieldThis event has probability at least , and . Thus
Paul Lévy Created 2026-10-18 Updated 2026-10-24
A mathematician who worked on probability theory.[ref]
https://www.polytechnique.edu/bibliotheque/actualites/levy-paul-x1904. École polytechnique Central Library, heading and biography: mathematician, life dates and probability research

Portrait of Paul Lévy
. Photograph by Konrad Jacobs, Erlangen; CC BY-SA 2.0 DE. Source.
For a zero-one-valued loss class , the excess misclassification risk of an empirical risk minimizer over a population minimizer satisfieswith probability at least . The proof combines Rademacher symmetrization with the Bounded differences inequality for the supremum of the empirical excess-loss process.
The observable version isIt follows by another application of the Bounded differences inequality to the Empirical Rademacher complexity.
Sub-sigma-algebra Created 2026-10-25 Updated 2026-10-31
A sigma-algebra on the same underlying set as , with . In probability theory it represents information retained from the original probability space and is a possible conditioning collection for a conditional expectation.
Students take three introductory subjects from the published list, including Probability theory and statistics. The branches represent the available subjects, not five compulsory modules.