Calculus connects local change with accumulated change. A derivative asks how fast a function changes near one input; an integral adds its contributions across an interval. The fundamental theorem of calculus explains why these operations fit together: accumulating a continuous rate produces a quantity whose derivative is that rate.
For example, suppose a particle moves along a straight line with position metres at time seconds. Its velocity is metres per second. Between and , adding the velocity over time givesHere the velocity stays positive, so the displacement also equals the distance travelled. If the particle reverses direction, the integral of its signed velocity still gives displacement, while the integral of its speed gives total distance.
This is useful because local rules are often easier to specify than whole trajectories. A differential equation can prescribe a particle's velocity or a population's growth rate; integration then reconstructs its evolution, subject to an initial condition. In the other direction, a derivative extracts local information from a known function, and optimization uses that information to locate or approach promising inputs. The same two operations therefore connect measurement, prediction and design.
The visual connection is developed in derivative, integral and fundamental theorem of calculus. The definitions depend on limits, which turn progressively finer finite measurements into exact mathematical statements. A graph with a corner need not have a derivative there, and the conditions permitting integration or interchange of limits matter; calculus is more than a collection of symbolic rules.
Historically, Isaac Newton described changing quantities and their rates in the language of fluents and fluxions; his manuscript History of the Method of Fluxions records that approach.[ref]
https://www.newtonproject.ox.ac.uk/view/texts/normalized/NATP00356. Isaac Newton, History of the Method of Fluxions, Cambridge University Library MS Add. 3968
Gottfried Wilhelm Leibniz's Nova methodus pro maximis et minimis appeared in Acta Eruditorum in October 1684, pp. 467–473; the original article is preserved in the HKUST Library collection.[ref]https://digitalcollections.hkust.edu.hk/Detail/objects/b540295. Gottfried Wilhelm Leibniz, Nova methodus pro maximis et minimis, 1684
The modern limit definitions used here should not be read back into those seventeenth-century formulations.In Cauchy's 1821 terminology, an infinitesimal is a variable quantity tending to zero. Other mathematical frameworks give different precise meanings to the word; the intended framework must be specified.[ref]
Cours d'analyse by Augustin-Louis Cauchy. Chapter II
Differential calculus studies derivatives: how a function changes near an input and how that local information describes its graph or evolution. Its tools include linear approximation, higher derivatives, and Taylor series; applications include finding velocity from position and studying optimization through critical points.
The floor function and ceiling function turn a real number into directed integer bounds. They answer two different questions: which integer is the largest one that does not exceed , and which is the smallest one that is not less than ?Both outputs are integers. These are exact mathematical operations; they need not choose the closest integer, and they do not refer to roundoff error in floating-point arithmetic.
For example,The fractional part is . The negative example matters: discarding the digits after the decimal point would give , which is truncation toward zero, rather than the floor function's value . At an integer, the floor function and ceiling function agree and the fractional part vanishes.
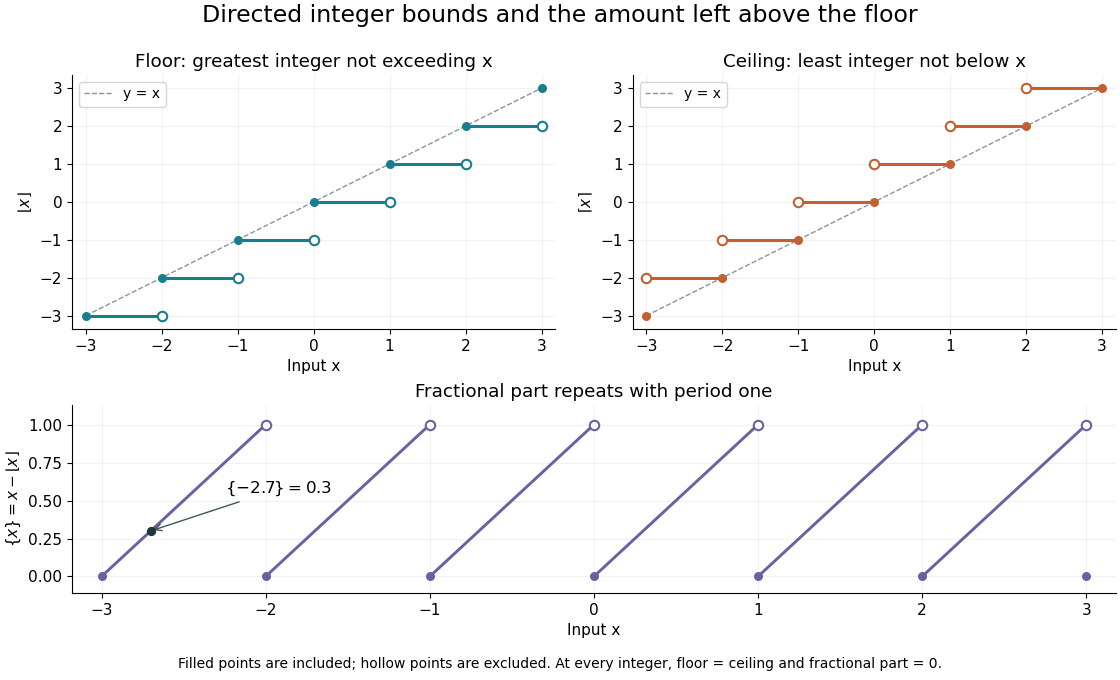
The usefulness is a bridge from continuous quantities to discrete decisions. An integer count in a closed interval uses both bounds. A ceiling count for fixed-size batches counts how many containers or pages are needed; a floor function counts how many complete groups fit. In Euclidean division, the same bounds specify the quotient, while the fractional part records the scaled remainder. A small amount of notation removes many cases that would otherwise have to be stated separately.
The reflection identityfollows by reflecting the ordered integers across zero: the largest one below becomes the smallest one above . For every integer , translation gives and . These formulas turn upper bounds into lower bounds and move examples between neighboring intervals.
For a historical example of the notation in use, Kenneth E. Iverson's 1962 conference paper A Programming Language lists the floor function, ceiling function and residue operation alongside the ordinary arithmetic operations. It states the two defining inequalities above, then extends operations component by component to vectors and matrices. This shows their role as tools for describing algorithms, rather than merely conventions for writing decimal numbers. [ref]
https://www.jsoftware.com/papers/AFIPS196205a.htm. Iverson, A Programming Language, AFIPS Spring Joint Computer Conference, May 1962, Basic Operations; transcription with typography changes documented at the end
For real numbers , the integers in the closed interval begin at and end at , if there are any. Their number is thereforeThe extra one includes both ends of the resulting integer interval. The maximum with zero handles an empty intersection: contains no integer, even though it has positive length.
For , the ceiling function selects and the floor function selects , giving . The four points are . For , the count is five, not four: the real length and the number of integer points are different quantities.
The endpoint convention matters. For the half-open interval with , the last allowed integer is , so the count becomes . This handles an integer endpoint without including it accidentally. For example, has four integer points.
The floor is the greatest integer not exceeding the real number . Equivalently, exactly when , for an integer . The floor function is constant on each such half-open interval and has a discontinuity of a function at each integer.
For nonnegative integers and positive integers , is the number of complete groups of size that fit into items. With and , five complete groups use 100 items. Euclidean division writes , retaining the two-item remainder rather than treating the quotient as a number of complete groups.
For a positive integer , indices with the same quotient form intervals. If an interval begins at , it ends at . There are distinct quotients: either , or the quotient is below . This permits summing constant-quotient blocks instead of visiting every index.
The operation returning for . It rounds the exact quotient toward negative infinity; for nonnegative integers and positive , it is the quotient in Euclidean division.
An algorithm for evaluating sums that depend on . If , then all indices from through have quotient . Jumping to visits only blocks rather than all indices.
A floor sum adds values of a floor function, often in the form for integers , , , and . If , it counts lattice points with and . Splitting and into quotients and remainders isolates an arithmetic progression and a constant contribution; swapping the remaining counting axes leads to an Euclidean algorithm reduction.
For an arithmetic function , changing the order of the finite summation gives . Both sides count pairs of positive integers with , assigning weight to each pair. This expresses a weighted floor sum in terms of a summatory function.
The fractional part of a real number isIt is the amount left after removing the lower enclosing integer, even for negative inputs. Thus . It is not the signed string of digits obtained by truncation toward zero.
Translation by an integer leaves the fractional part unchanged: . It is therefore a periodic function with period one, increasing from zero toward one on each unit interval, then returning to zero at the next integer. In Euclidean division with , ; for , this is .
The notation is useful for following repeated motion modulo an integer. In normality and equidistribution under integer multiplication, the values shift the digits of a positional notation; the fractional part discards the leading integer portion without losing the remaining digits. Its braces must be distinguished by context from the braces denoting a set.
The ceiling function gives the least integer large enough to meet a real lower bound. For a real number ,Thus , , and . The operation rounds upward in the total order on the real numbers, which can move a negative input towards zero. Its difference from the input obeys . Python's
math.ceil implements this least-integer definition. [ref]https://docs.python.org/3.14/library/math.html#math.ceil. Python 3.14 math.ceil documentation: the least integer at least x
.The ceiling count for fixed-size batches is a direct application. Suppose each box holds at most items, with positive integer , and there are items. The smallest number of boxes with enough capacity is : a candidate count must satisfy . For , , six boxes are needed, leaving unused places. Exactly 100 items need only five boxes, and zero items need zero boxes. Adding one to the floor function result unconditionally would therefore overcount at exact multiples of .
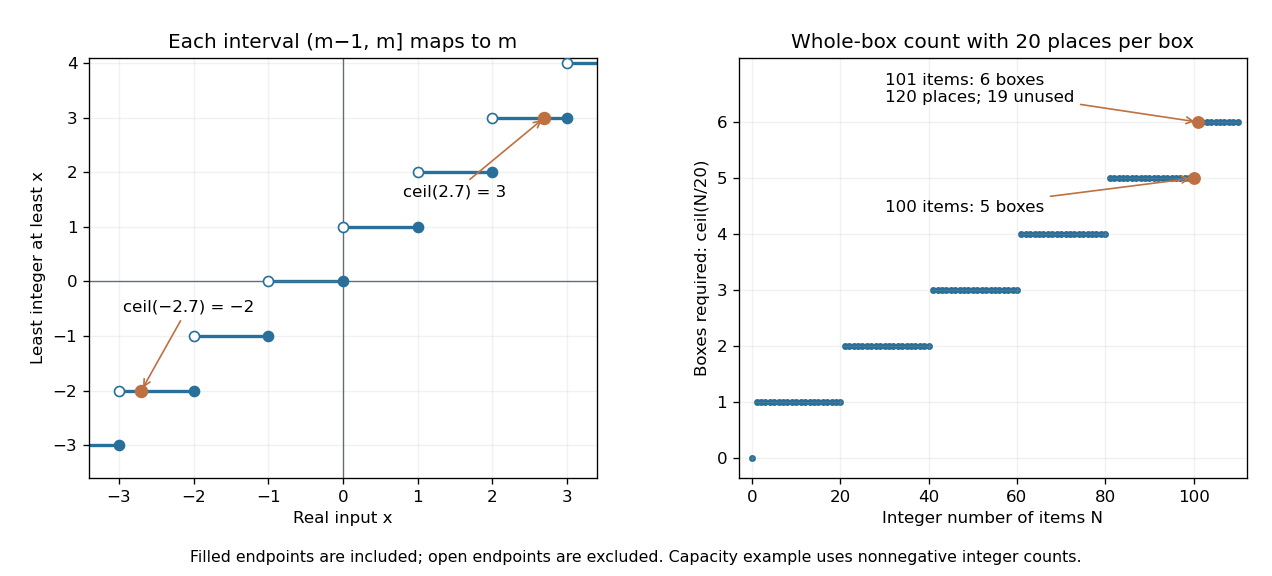
The ceiling function retains the endpoint on the left and counts enough whole containers
. Left: open and filled endpoints distinguish the half-open intervals where , including negative inputs. Right: the original capacity example uses 20 items per box; 101 items need six boxes, while an exact multiple of 20 needs no extra box. The right-hand inputs are integer item counts. Details.For nonnegative integer and positive integer , Euclidean division gives the exact identityWrite , . The count is when the remainder is zero and otherwise, and the right-hand side encodes these two cases. This argument specifies the domain of the identity; arbitrary negative denominators require their own sign conventions.
The ceiling function is a nondecreasing function, constant on each of the half-open intervals , and has a discontinuity of a function at every integer. It is tied to the floor function by . Adding an integer shifts its output by the same amount: . At an integer the floor and ceiling agree; at every other input they differ by one. These statements refer to exact real numbers; an input already perturbed by floating-point arithmetic can land on the other side of a threshold.
Suppose is a nonnegative integer count of items and each batch holds at most items, where is a positive integer. The smallest sufficient number of batches isIndeed, exactly when the integer is at least . If , no batches are needed. If is a multiple of , no partly filled batch is needed.
For items with capacity per batch, . Five batches can be full and the sixth holds two items, leaving unused places. This is a different question from the five complete groups counted by .
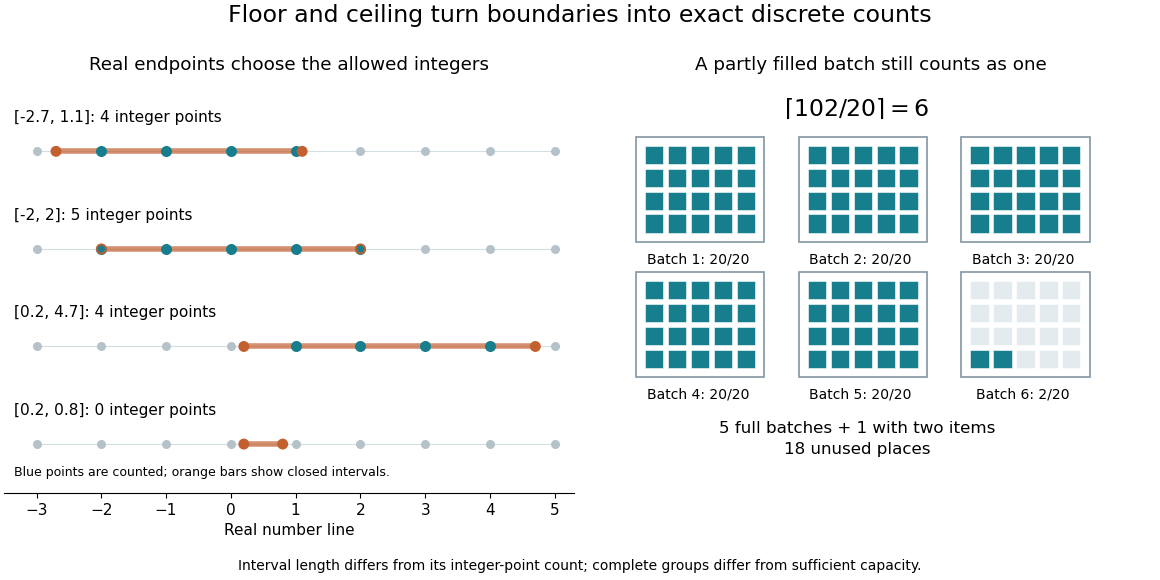
Writing the Euclidean division , , gives the equivalent rule when , and when . This explains the ceiling function's jump: one extra item beyond a complete multiple demands a whole additional batch. For exact integer arithmetic, the identity avoids a fractional intermediate value; an implementation still needs an integer representation large enough to hold .
Truncation toward zero removes the fractional magnitude of a real number, giving the integer obtained by applying the floor function to its absolute value and restoring the original sign; a magnitude below one gives zero. More precisely,The result is zero for . For example, and , whereas . Python's
math.trunc uses this towards-zero convention, so replacing it by math.floor changes calculations with negative noninteger inputs. [ref]https://docs.python.org/3.14/library/math.html#math.trunc. Python 3.14 math.trunc documentation: floor on positive inputs, ceiling on negative inputs
.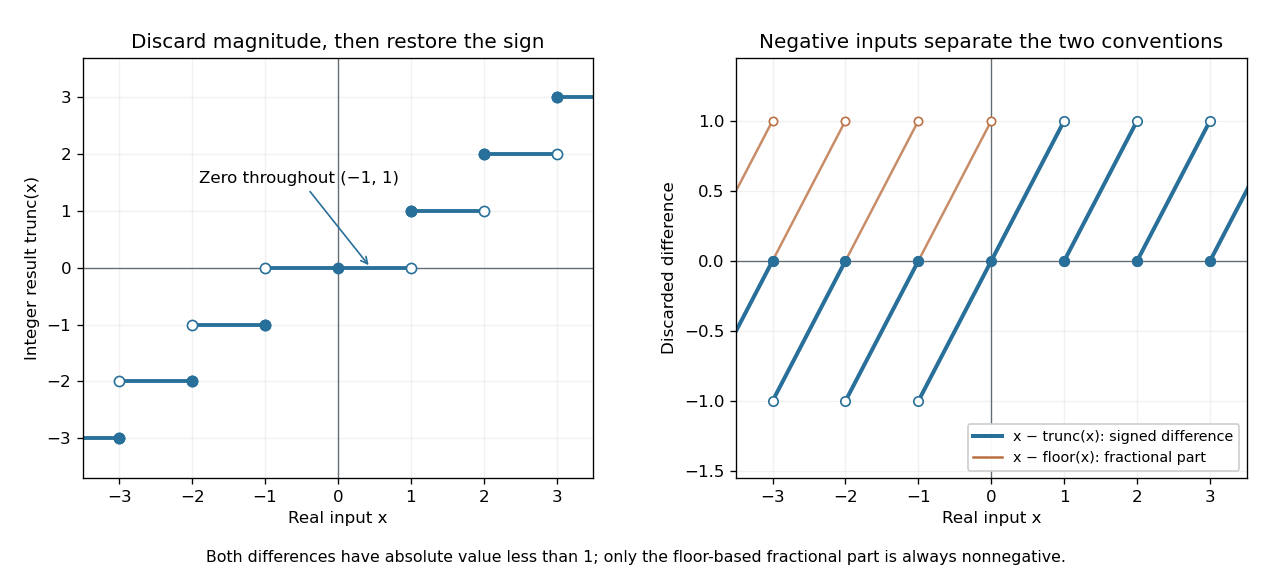
Truncation toward zero is symmetric in sign, while the fractional part defined by the floor function is always nonnegative
. Left: exact integer endpoint values distinguish the two sign-dependent truncation rules; a whole neighborhood of zero maps to zero. Right: takes the sign of a noninteger input, while lies in on both sides of zero. Open endpoints show excluded limiting values. Details.For every real number ,The discarded difference has the sign of when is noninteger. In contrast, the fractional part is always in . At , these two differences are and . Thus specifying a signed fractional remainder requires specifying which integer-valued operation is used.
Unlike the floor function and ceiling function, truncation toward zero need not commute with adding an integer. At and , , whereas . This matters if negative coordinates are assigned to equal-width bins by converting a quotient to an integer: belongs to the bin under the floor function, but truncation gives zero. The appropriate operation follows from the declared bin intervals.
Truncation toward zero is a nondecreasing function with a discontinuity of a function at each nonzero integer. It has no discontinuity of a function at zero, because it is identically zero on . Its agreement with the floor function on the positive side and the ceiling function on the negative side explains the different closed endpoints in the diagram.
An integral adds up contributions of a function across a domain of integration. For a continuous function on , the Riemann integral is the common limit of its Riemann sums as the largest subinterval width tends to zero:Each product combines a value with the width over which it acts. When is nonnegative, the result is the area beneath its graph; values below the horizontal axis contribute with the opposite sign. The signed area under a graph can therefore vanish even when the graph encloses nonzero geometric area.
For a velocity on , use equal time steps. The left and right Riemann sums areBecause the function is increasing, they bound the integral. With six steps they give and ; with sixty steps they give and . Both approach the same total, . This is accumulation made exact by refining finite measurements.
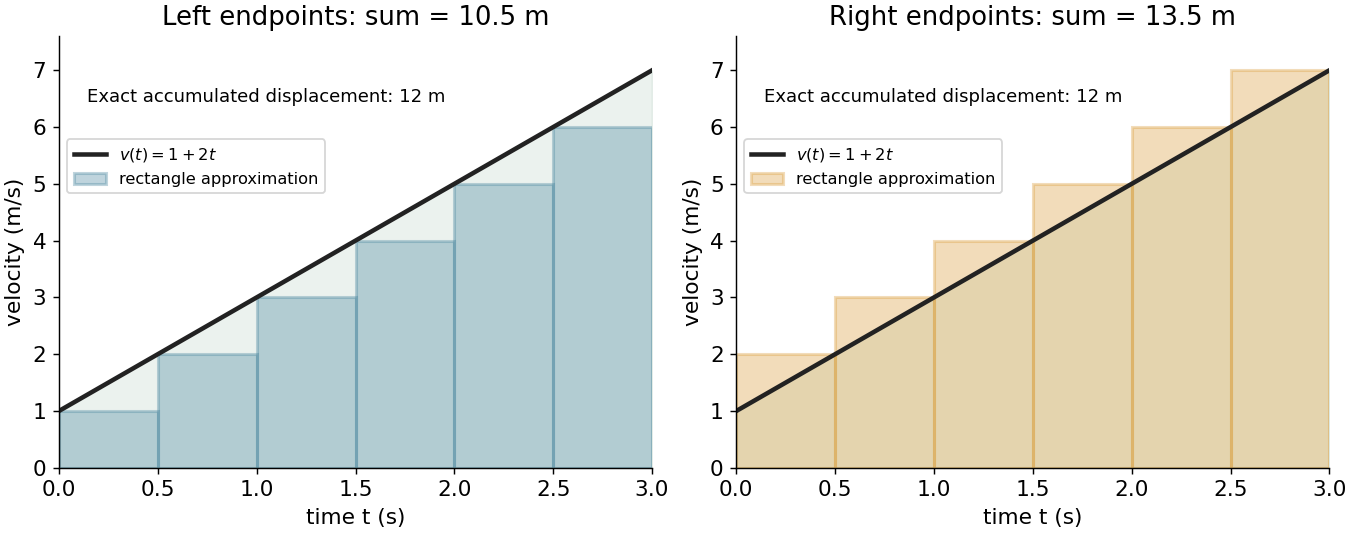
An integral retains units: velocity times time gives displacement, and a probability density function integrated over an interval gives a probability. Weighting a density by a function gives its expectation. The same operation serves different subjects because it expresses a common pattern, value multiplied by extent, then accumulated.
The fundamental theorem of calculus often evaluates a definite integral by finding an antiderivative, but a finite sum or a numerical approximation is still useful when no convenient antiderivative is available. An indefinite integral denotes a family of antiderivatives; a definite integral denotes an accumulated value between specified endpoints. More general constructions, including Lebesgue integration, extend the class of functions and domains that can be handled.
On , the power rule for derivatives and the fundamental theorem of calculus give the displayed antiderivative. In particular for , understood as an improper integral when needed. At , the antiderivative on is the natural logarithm .
An integral over the boundary of a region, such as a line integral around a planar region or a surface integral over the boundary of a three-dimensional region. Green's identities convert certain volume integrals into boundary integrals.
The two identities areTo prove them, expand in its exponential series. Since on , the Weierstrass M-test justifies termwise integration. Substituting gives through the gamma function. Inserting these moments into the series and shifting proves both formulas. Each resulting numerical series has absolute convergence.
If measurable functions satisfy almost everywhere and is nonnegative and Lebesgue integrable, then is Lebesgue integrable and . This follows from monotonicity of the Lebesgue integral. Conversely, with rules out Lebesgue integrability of . For nonnegative improper integrals, the same comparison applies after taking increasing finite-interval limits.
The domain of integration is the set over which an integral is taken. For a multiple integral, inequalities or parameter ranges specify which points belong to ; a change of variables transforms both these bounds and the integration element through its Jacobian determinant. For example, a polar region exists only at angles where .
The set over which an integral is taken. For a double integral, boundary inequalities describe the allowed coordinate pairs, and slices of this set determine the limits in an iterated integral. The domain need not be a rectangle or connected. A change of variables transforms both the integrand and this set.
If and is differentiable, the chain rule gives . Taking antiderivatives gives the substitution ruleWriting and records this chain rule in reverse. For a continuous function and continuously differentiable , the fundamental theorem of calculus gives the corresponding definite integral identityThe order of the transformed endpoints determines the sign. For example, . If the substitution is used in the opposite direction by solving as a function of , one must restrict to a suitable inverse branch; the tangent half-angle substitution illustrates why separate branches can be necessary even when the original integrand is smooth. The general change of variables formula extends substitution to higher dimensions.
A trigonometric substitution is integration by substitution using a trigonometric function to simplify an integrand, especially a square root. For example, , with and , changes to and to . The interval restriction fixes the sign of the square root. Similarly simplifies . The transformed integral must include the differential and, for a definite integral, the new limits.
For an integrable function on an interval of positive finite length, its average value is the integral divided by that length:If is constant on equal-length subintervals, this is their values' arithmetic mean; unequal lengths require a weighted mean. For example, values and on two equal halves give average value , whereas value on the first quarter and on the remaining three quarters give . The integral measures total contribution; the average value of a function divides out the interval length.
For the function on , the average value of a function is . Replacing it by the constant preserves its integral on this interval. This is why the Haar projection uses cell averages to obtain a coarser description while retaining each cell's total contribution.
For integrable real-valued functions on a measure space and fixed real numbers , their linear combination is integrable, and the Lebesgue integral satisfiesThe same rule applies to any finite summation: for integrable functions and fixed scalars . Finite signed values matter: integrability ensures all these integrals are finite, so no undefined occurs.
This is the distributive property of finite summation carried into integration: a fixed factor can be pulled out, and a finite sum can be integrated term by term. For simple functions, distribute the finite sums of value times measure; approximation extends additivity to nonnegative measurable functions, and splitting into a positive part and negative part gives the integrable signed case. See Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem (Proposition 122: linearity for integrable functions). For example, . With a probability measure, linearity of integration gives linearity of expectation.
For and a real-valued function with a finite Riemann integral or Lebesgue integral on , the signed area under a graph is its definite integral: geometric area above the horizontal axis contributes positively, and geometric area below it contributes negatively. If these two nonnegative areas are and , thenThe second expression is the total geometric area under a graph. Taking the absolute value of the first expression does not usually give the second: cancellation has already removed information about how much area lies on each side.[ref]
For an exact example, take the polynomial function on . Its polynomial roots are and : it is negative between them and positive on the two outer intervals. An antiderivative is , so the fundamental theorem of calculus givesThus and . The signed area under a graph is , whereas the total geometric area under a graph is . To compute the latter with antiderivatives, split at each sign-changing polynomial root and reverse the sign of the negative contribution.
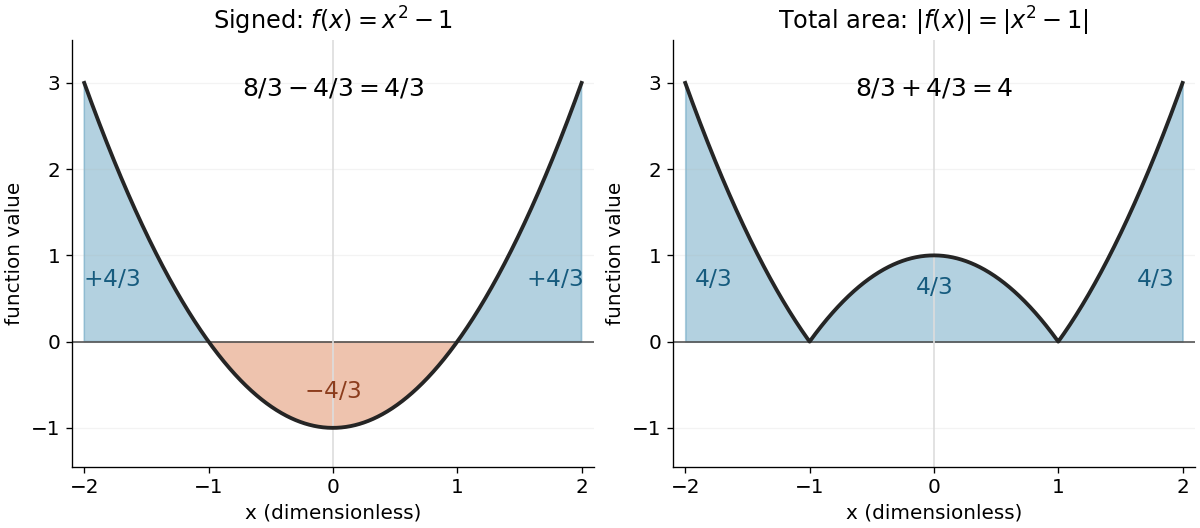
The polynomial x squared minus one has signed integral 4/3 and total geometric area 4 on the interval from minus two to two
. Details. Cancellation is useful information when the integrand represents a signed contribution. For the polynomial function on , the two triangular areas give , although . Zero net signed area therefore means balanced positive and negative contributions, rather than an empty region.
The short algebraic justification uses the positive part and negative part : and . Their integrals give and , and linearity of integration gives the difference and sum formulas. For Lebesgue integration, require both contributions to be finite to avoid the undefined subtraction .[ref]
A definite integral accumulates an integrand between specified endpoints, retaining the sign of each contribution. For a real-valued function on a finite real interval, a finite definite integral is a scalar; an indefinite integral describes a family of antiderivatives. The lower and upper limits of integration specify where accumulation starts and ends. The integration variable is a placeholder: .
This is useful whenever a varying rate must be converted into a total change. For motion along a straight line with continuous velocity and position satisfying , the fundamental theorem of calculus gives displacement, while accumulating speed gives the distance traveled from velocity:Negative velocity reduces displacement while adding to the distance traveled from velocity. The physical dimension of a definite integral is the product of the integrand's physical dimension and the integration variable's physical dimension: here . An area on a rate graph need not be a spatial area.[ref]
5.4 Integration Formulas and the Net Change Theorem. Theorem 5.6 and the displacement and total-distance discussion
As an explicitly synthetic motion model, let for , with . Using numerical values in seconds and metres, an antiderivative gives . The velocity changes sign at : the model first moves m in the negative direction, then m in the positive direction. Its displacement is m, and its distance traveled from velocity is m. The initial position fixes the constant of integration, but does not change either accumulated quantity.
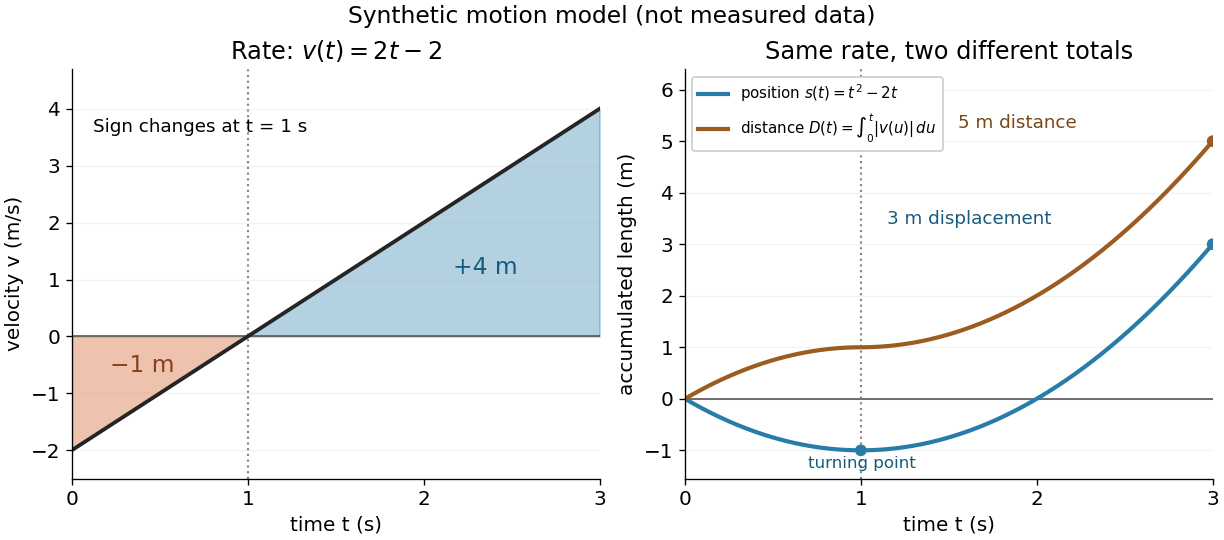
Synthetic variable velocity model with displacement 3 metres and distance traveled 5 metres over three seconds
. Details. Orientation matters independently of whether the integrand is positive or negative. For a function integrable on the interval containing the endpoints, use the conventionsFor the preceding velocity model, accumulation from seconds back to seconds gives m. Reversing the bounds of the speed integral gives m, which is an oriented integral, not a negative distance traveled from velocity; physical elapsed-time totals use the earlier endpoint first. The splitting rule holds even when is outside the interval between and , provided integrability holds on the interval containing all three endpoints.[ref]
Existence needs hypotheses. For a bounded function on with , a finite Riemann integral exists when every tagged Riemann sum approaches the same value as the largest cell width tends to zero:The limit must be independent of both the partition of an interval and the tags. Merely making the number of cells large can leave a wide cell unresolved. On a finite closed interval, every continuous function, and every bounded function that is continuous except at finitely many points, is Riemann integrable.[ref] Boundedness alone is insufficient: the Dirichlet function on is on the rational numbers and on the irrational numbers. Tags can all be chosen rational or all irrational, giving Riemann sums of or at arbitrarily small cell widths.[ref]
For a finite signed Lebesgue integral, the condition is instead that be a measurable function for Lebesgue measure and . A measurable function for Lebesgue measure that is also a bounded function on a finite interval satisfies this condition since gives . The Dirichlet function therefore has Lebesgue integral zero: the rational numbers form a null set, so it equals zero Lebesgue almost everywhere. The Riemann integral and Lebesgue integral agree for the continuous functions used in the diagrams.[ref]
Lecture 12: Lebesgue Integrable Functions, the Lebesgue Integral and the Dominated Convergence Theorem. Definition 120, Proposition 123(2), Remark 124 and Theorem 126
An unbounded integrand or infinite endpoint requires further analysis, for example the limits defining an improper integral; the notation alone does not establish convergence.The lower and upper integration limits specify the ordered endpoints of a definite integral . Interchanging the integration limits reverses its sign: .
The Wallis integrals are for integers . Integration by parts gives for , with , . HenceBecause in the integration interval, for . Combining this with the recurrence gives , proving that the ratio tends to one and yielding the Wallis product.
Here , and . The identity holds where the segment of source points , , avoids the observation point and the denominator is nonzero. Differentiating the right side with respect to gives the integrand and its value at is zero. Dotting with a current dipole moment evaluates a continuous line of dipole electric potentials.
In , the function is the integrand. It is distinct from the integration variable, the bounds and the resulting integral. In contour integration, the transformed integrand includes the parametrization derivative.
A multiple integral accumulates a function over a region with several coordinates. The Fubini theorem and Tonelli theorem give conditions under which it equals successive one-dimensional integrals. A change of variables formula expresses it in new coordinates using the absolute Jacobian determinant.
A triple integral is a multiple integral over a three-dimensional region. For a mass density , gives the total mass, while gives its volume. Iterated one-dimensional integration is justified by Fubini's theorem under absolute integrability, and a change of variables includes the absolute Jacobian determinant in the volume element.
Under a smooth locally invertible coordinate map into Euclidean space, the positive volume element in a multiple integral is multiplied by the absolute Jacobian determinant. In three-dimensional spherical coordinates, ; in cylindrical coordinates, . The absolute value distinguishes positive integration measure from a signed orientation convention.
An iterated integral performs successive one-variable integrals. In the displayed expression, is held fixed during the inner integration over , and the result is then integrated over . The inner bounds may depend on that fixed outer variable. By contrast, an inner bound depending on an already integrated variable does not specify such a nested operation without further interpretation. For example, the triangle , gives , or, in the other order, . Fubini's theorem and Tonelli's theorem supply conditions under which these iterated expressions equal the same multiple integral.
The sequence in which variables are integrated in an iterated integral. Reversing the order changes the slicing of the domain of integration, often requiring more than one integral. Fubini's theorem permits interchange for absolutely integrable functions, while Tonelli's theorem permits nonnegative measurable integrands even when the integral is infinite. Conditional convergence requires additional care; geometric reversal alone is not a general justification for interchanging improper integrals.
If a region is invariant under one coordinate reflection and an integrable function changes sign under that reflection, its multiple integral is zero. Apply the change of variables formula to the reflection, whose absolute Jacobian determinant is one: the integral equals its negative. This applies to odd coordinate powers in symmetric volumes and to the off-diagonal entries of an inertia tensor when the mass density shares the coordinate-reflection symmetries.
An integral representation expresses a function through an integral of specified data and an integral kernel. Green-function representations solve differential equations this way, while the Bromwich inversion formula reconstructs a function from its Laplace transform.
The sine and cosine integrals accumulate and , with different normalizations at zero and infinity. They arise in oscillatory integrals, Fourier transforms of singular kernels and Fourier series of logarithmic profiles.
For real , its small-argument expansion is . Integrating separates the logarithm from the regular correction. Its conventional constant is the Euler--Mascheroni constant; the primary series normalization is dlmf.nist.gov/6.6.E6 .
For real , the sine integral approaches . Exponential damping gives , so the limiting constant follows by letting . Integration by parts of the tail gives .
Lebesgue integration constructs an integral from the measure of level sets or from approximation by simple functions. It is linear on integrable functions and is stable under the principal convergence theorems of measure theory.
If and nonnegative measurable functions satisfy for all , then their Lebesgue integrals obeyThe quantile derivative identity and monotone substitution inequality prove the one-dimensional case; Tonelli theorem extends it by induction. It implies the Brunn–Minkowski inequality.
If , then for every there is such that whenever the measure of is below . In particular, integrals over a sequence of shrinking measurable sets tend to zero.
A time integral accumulates an integrand over a time coordinate. In perturbation theory it commonly sums the effect of an interaction over all possible vertex times.
A double integral integrates a function over a two-dimensional region. A change of variables formula can replace the region and area element using a Jacobian determinant.
It is a multiple integral with two integration variables.
An antiderivative recovers a function from its local rate of change. For a real-valued function on an open subset of the real line, a differentiable function is an antiderivative whenFor example, has the antiderivatives for every real additive constant . Their derivatives agree, while their values can differ. On an interval, the constant of integration describes the entire freedom in the answer. [ref]
https://openstax.org/books/calculus-volume-1/pages/4-10-antiderivatives. OpenStax Calculus 1, §4.10: antiderivatives and their families
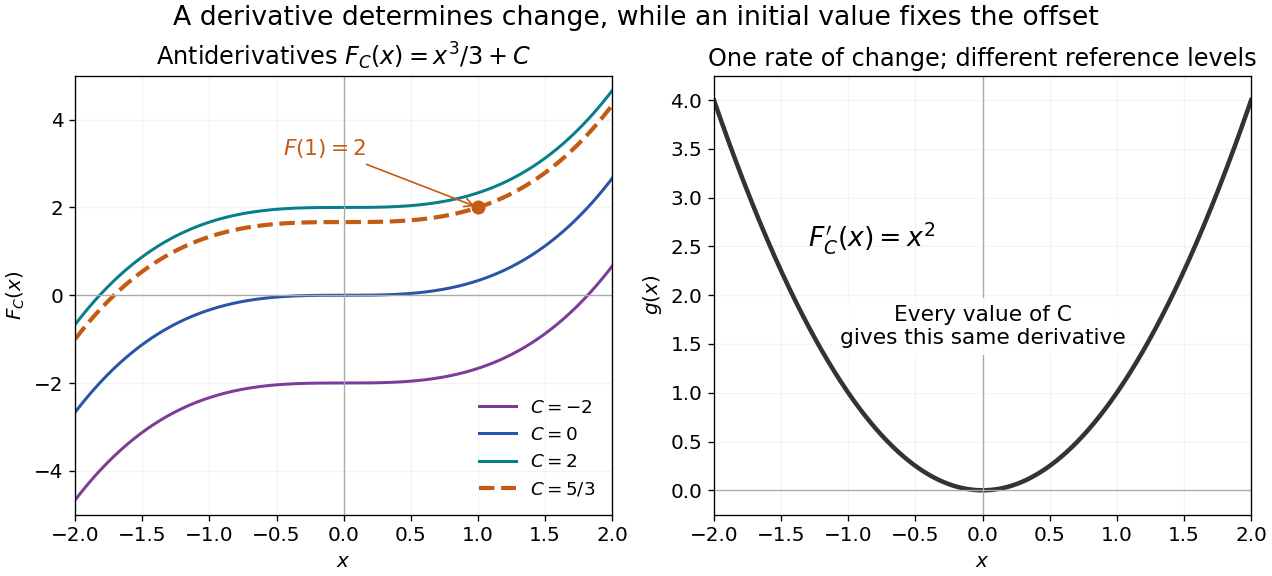
The indefinite-integral notation records this family on an interval. For the illustrated family, the extra condition selects . Thus reversing differentiation requires both a rate and a reference value if a unique function is wanted.
The fundamental theorem of calculus supplies a construction when is continuous on an interval . Choose and set ; then . Integrability alone does not guarantee a classical antiderivative. The Heaviside step function is Riemann integrable on bounded intervals, but cannot be a derivative throughout an interval containing its jump: Darboux theorem for derivatives requires every intermediate value. [ref]
https://www.jirka.org/ra/html/sec_mvt.html. Lebl, Basic Analysis I, §4.2.5: the intermediate-value property of derivatives
A holomorphic function on a domain with complex derivative . Its contour integral satisfies by the chain rule along each smooth contour segment. In particular every closed contour has integral zero. Having local complex antiderivatives need not provide a single one on a domain with holes.
On a connected open interval, if , every antiderivative of has the form , where is a constant function. Indeed, two solutions satisfy : the zero derivative on a connected open set principle makes their difference constant. In one dimension, the mean value theorem proves this on any closed subinterval. [ref]
https://www.jirka.org/ra/html/sec_mvt.html. Lebl, Basic Analysis I, Proposition 4.2.6: zero derivative on an interval
An initial condition or boundary condition can determine . If a particular antiderivative is and , thenFor , and , this gives . Without that reference value, choosing simply selects one member of the family.
The freedom has a physical meaning in a simple kinematic model. A velocity , with constant acceleration , determines position only as . The initial condition selects ; changing the starting position does not change the prescribed velocity.
For the differential equation on , the antiderivative is . The boundary condition gives . Discarding the constant of integration therefore needs a specified condition or an approximation that quantifies its effect. On a domain with several connected components, the freedom is larger: antiderivatives on disconnected domains require a separate constant on each component.
Let be an open subset of the real line, and let be antiderivatives of the same function on . Each connected component is an open interval. On that component, , so the mean value theorem gives . The constants on different components are independent: there is no subinterval inside joining them. Conversely, adding any chosen constant on each component preserves the derivative everywhere on .
For example, the domain of is . Every antiderivative on this domain has the formwith arbitrary real . The logarithm of the absolute value differentiates to on each side. The function with and is therefore a valid antiderivative, although it cannot be written as with one global constant.
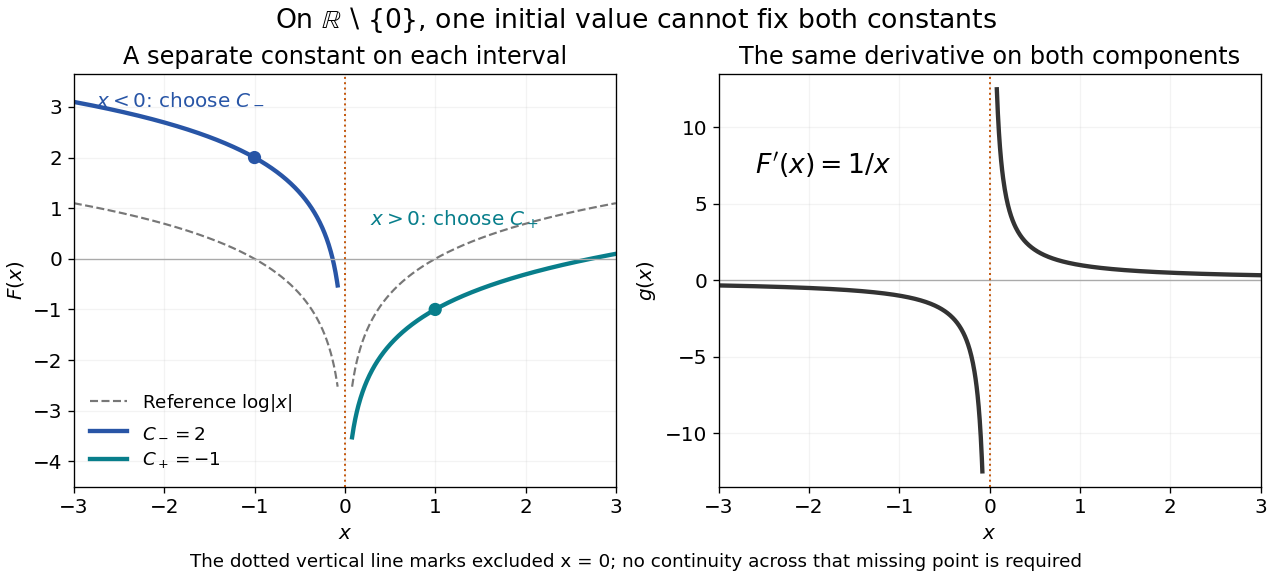
Two disconnected intervals allow independent constants while the derivative stays the same
. Details. An initial condition at fixes and leaves free. Fixing both constants requires one reference value in each connected component, or additional conditions that couple the components. The locally constant function captures this remaining freedom.
A constant added to a function changes its reference level without changing its derivative:Geometrically, it is a vertical translation of the graph. For , changing moves every plotted value by the same amount while preserving every tangent slope. This is the geometric reason that antiderivatives form a family.
When represents a physical quantity, the physical dimension of must match that of . When position is obtained from velocity, is a position offset. An unknown starting position remains unknown even when the rate of change is known exactly.
When describing the family of antiderivatives on an interval, the arbitrary additive constant is the constant of integration. On a disconnected open domain, the corresponding freedom is a locally constant function, as in antiderivatives on disconnected domains, rather than necessarily one constant on the whole domain.
The Gaussian integral gives the exact area under a Gaussian function. For a positive real number ,This is a finite improper integral over the whole real line. For example, and . Increasing from one to four narrows the curve and halves its area, while its height at zero stays one. The change of variables explains the factor .
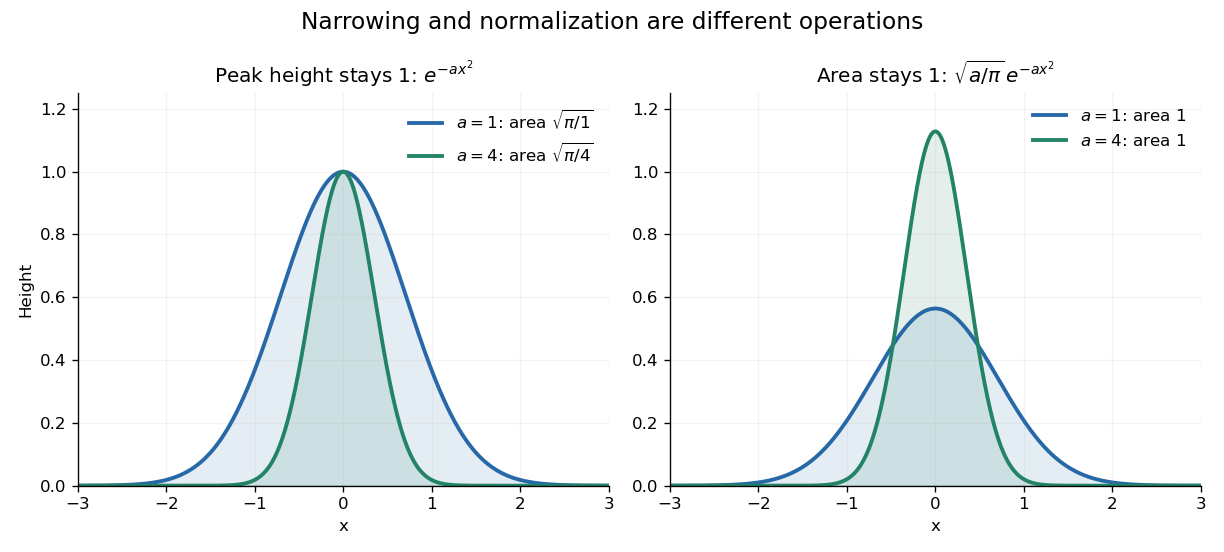
The useful consequence is an exact normalization. For and any real center ,This is a probability density function for a normal distribution with expected value and variance . A narrower probability density function must be taller to keep total probability one. In the usual notation , the prefactor is , where is the standard deviation.
The same area calculation makes the one-dimensional heat kernelintegrate to one in , with the diffusion coefficient. A spreading Gaussian function can therefore preserve total mass while its height falls. This links the Gaussian integral with both the normal distribution and the diffusion equation.
Finite intervals lead to the error function, rather than this single constant:The complementary tail is described by the complementary error function. These definitions and their real-axis limits are given in the NIST reference. [ref]
The polar-coordinate proof of the Gaussian integral explains why appears in an integral of a function defined on a line: squaring its area creates a rotationally symmetric integral on a plane. Substitution also gives , connecting the result with the gamma function.
For , the real integrand is symmetric under , so the ordered domain contributes half the full plane. The result is , using the Fourier transform of a Gaussian function. The imaginary part is not generally zero and must not be discarded before pairing conjugate harmonics in a real response.
For , the integrand is even and integrable at zero and infinity. On the positive half-axis the change of variables maps bijectively onto and satisfies . Solving the quadratic for the positive root givesAfter doubling this half-axis integral, the odd part of the transformed integrand integrates to zero and the remaining Gaussian integral yields the formula. The reciprocal substitution also givesThe positive parameters ensure that the substitutions and improper integrals are valid; the second identity can also be recovered by differentiating the first in under the integral sign.
For integers , integration by parts givesThe boundary term vanishes because at zero and Gaussian decay dominates every power at infinity. The initial values are , the half-line Gaussian integral, and by the substitution rule . More generally, for real , that substitution gives , linking the recurrence to the Gamma function.
For and a nonnegative integer , substitute . Then , so the integral reduces to the gamma function value . This proves the formula. The corresponding whole-line integral is zero by odd symmetry, and both integrals converge absolutely. A half-line integral of an odd function need not vanish.
For integer , integration by parts gives . The boundary term vanishes at both infinities because Gaussian decay dominates every power. The full-line initial values are and , the latter by odd symmetry. HenceUnlike the half-line Gaussian moment recurrence, full-line odd moments vanish and even moments are twice their half-line values. The domain of integration must be retained when transferring a recurrence between the two settings.
Put . The nonnegative integrand allows Tonelli's theorem to write the square as a double integral:In polar coordinates, , , and the Jacobian determinant supplies the area factor :Since , take the positive square root to get . The computation proves finiteness as well as the value. For an explicit limiting argument, first integrate over disks of radius ; their integrals are , which increase to as . [ref]
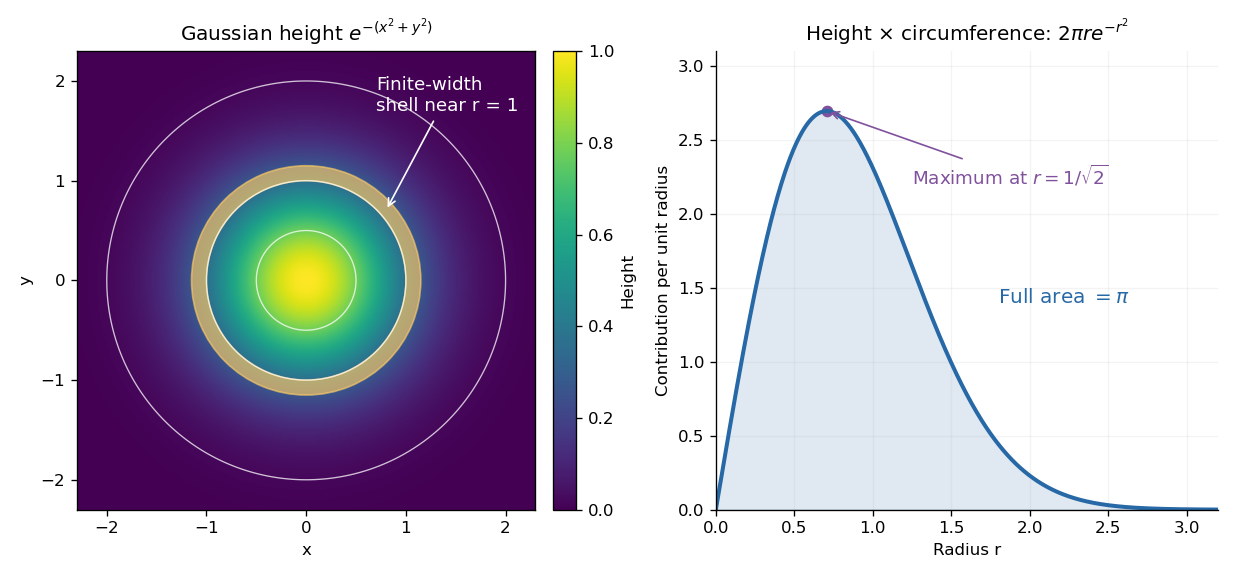
The geometric surprise is that radial shells get longer as increases, even while the Gaussian function gets smaller. Its central height is largest at zero, but the radial contribution vanishes there and peaks at . Differentiating gives , which changes sign at that radius. Keeping the Jacobian determinant is what makes the one-dimensional integral and the plane geometry agree.
For real symmetric positive-definite , complete the square with . Orthogonal diagonalization reduces the remaining integral to the product of one-dimensional Gaussian integrals, proving the displayed expression. Positivity ensures convergence and the positive determinant square root. Replacing matrices by regulated field kernels gives the Gaussian functional integral; an oscillatory Minkowski integral instead requires a causal convergence prescription.
The Dawson function obeys by differentiation. Its large-real-argument asymptotic expansion begins . This inverse-power behavior contrasts with the separate exponentially growing factors in its definition.
Define and . They satisfy and . The first is an even function, the second an odd function, and their real tails are respectively and . Their derivatives have inverse-linear tails, explaining the logarithmic matching constants in a singular perturbation.
The error function records the signed area under a Gaussian function between zero and a variable endpoint:For a negative real number , reversing the integration limits makes this integral negative. The normalization uses the Gaussian integral: the full area of is , so its positive half contributes one after multiplication by . The same definition extends to a complex number along any path from zero to , giving an entire function.[ref]
For example, , , and . A finite positive endpoint captures only part of the positive Gaussian integral; approaches one as but never reaches it at a finite real .
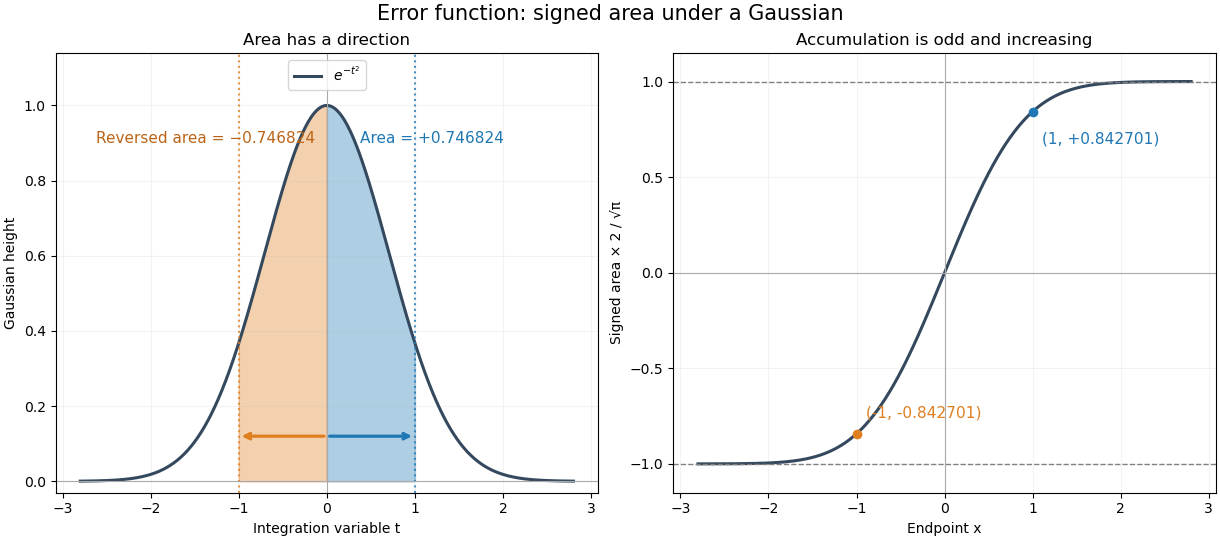
The useful idea is to name a recurring integral once instead of carrying it through every calculation. The error function and the normal distribution express probabilities and quantiles through this area, while an error-function diffusion front describes how diffusion smooths a sharp jump. The complementary error function retains the small area left in the tail.
The fundamental theorem of calculus givesThus the real-axis error function is strictly increasing, with values in . Its integrand is an even function, so the error function is an odd function, . The derivative also gives : the curve is concave for and convex for . These real-axis properties do not imply boundedness throughout the complex plane; the existing quadrant asymptotics of the error function describe a different behavior in other directions.
For a standard normal random variable , its standard normal distribution function isThe change of variables and the symmetric distribution of the standard normal random variable give the second expression. For with , standardization of a normal random variable then givesIn particular, the intervals within one, two, and three standard deviations have calculated probabilities about , , and . These values depend on a normal distribution; they are not universal coverage guarantees for an arbitrary random variable. This is the direct connection between a Gaussian function area and the familiar central intervals.
For a small upper-tail probability, use the complementary error function directly:Computing this as instead can lose the tail to catastrophic cancellation. The Gaussian tail bound gives another useful estimate without requiring an exact error function value.
Because the real error function is strictly increasing from to , its real inverse function maps onto the real line. For , the standard normal quantile is thereforeMore generally, the -quantile of a normal distribution with expected value and positive standard deviation is . This reverses the area calculation: instead of asking how much probability lies below an endpoint, a quantile asks which endpoint encloses a specified probability. The domain restriction matters; and correspond to infinite endpoints, rather than finite real values of the inverse error function.
Consider the one-dimensional diffusion equation on the whole real line,with initial value one for and zero for . This is an idealized Heaviside step function profile, not a measured material or an apparatus specification. The heat kernel gives a convolution with the initial profile:The change of variables turns the convolution into a Gaussian integral tail. The resulting similarity variable shows that the transition width grows like : multiplying elapsed time by four doubles every fixed-profile distance from the original interface.
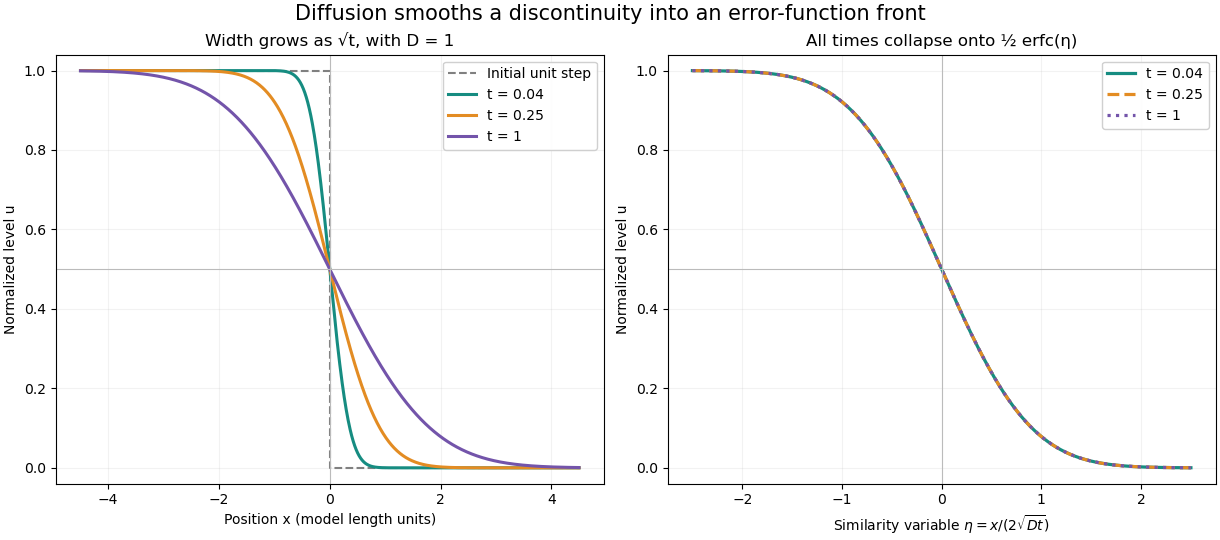
At every positive time, , while as and as . For every fixed , the limit as returns the specified initial value. The value assigned at the single initial discontinuity does not change this convolution. The error function therefore explains smoothing without pretending that a discontinuous initial profile remains sharp.
Direct differentiation checks the partial differential equation. Writing givesThe model assumes constant diffusion coefficient, no advection, and no finite-domain boundary effects. For an interpretation as heat conduction, the heat equation applies to a normalized temperature difference under its own material assumptions.
For with fixed , a horizontal tail gives . The constant dominates through ; above that angle the exponential endpoint dominates. At the boundary angle its modulus is only , so the constant remains leading. On the imaginary axis the integral is purely imaginary and grows as . The approximation is not a determination of exponentially subdominant constants in that growing sector.
The complementary error function describes the Gaussian integral area remaining beyond the endpoint. For a real ,It is an entire function for complex arguments when defined by . On the real line it decreases from two to zero, with and .[ref]
For example, is a sizeable tail, whereas is extremely small. In the tested floating-point arithmetic, a direct evaluation of gives zero because the computed error function has already rounded to one. Evaluating the complementary error function directly preserves this tail. It is the useful quantity in an upper-tail normal distribution probability and in the decaying side of an error-function diffusion front.
For large positive real , the leading asymptotic expansion isThe first corrections are multiplying the leading term. This is an asymptotic expansion, not an assertion that summing arbitrarily many terms converges at a fixed .[ref] The complementary error function tail bound provides finite- inequalities instead.
For every real ,For a short proof, put . Integration by parts givesThe last integral is positive and strictly smaller than . Using these two inequalities gives the upper and lower bounds after multiplication by . Dividing both bounds by also proves the leading asymptotic equivalence by the squeeze theorem. For small positive , the bounds remain true but can be loose; they are especially useful when the Gaussian integral tail is already small.
The Faddeeva function is an entire function built from the complementary error function. Its integral representation for is , as normalized in NIST's integral representation. Its reflection identity is , directly from the odd function property of the error function.
For a pole off the real axis, substitution into the Faddeeva function integral gives when , and when . The difference of boundary values is the residue theorem jump . In particular, for a lower-half-plane pole, , which packages a crossed residue and a nearby saddle into one smooth expression.
A Taylor polynomial replaces a function near a chosen point by a polynomial with matching derivatives. If has derivatives through order at , defineThe factorial denominator makes for . This determines a unique polynomial of degree of a polynomial at most . Order zero matches the value, order one also matches the tangent line, and order two also incorporates the second derivative. Matching more local information is useful because polynomials are easy to evaluate, differentiate, and integrate. The distinction between the finite Taylor polynomial and the infinite Taylor series is developed in OpenStax, Taylor and Maclaurin series.
For a computed example, let and expand at zero. Its first three derivatives giveAt , the linear approximation is and the quadratic approximation is , compared with . The quadratic correction captures the downward bending of the square root and reduces the absolute difference from about to .
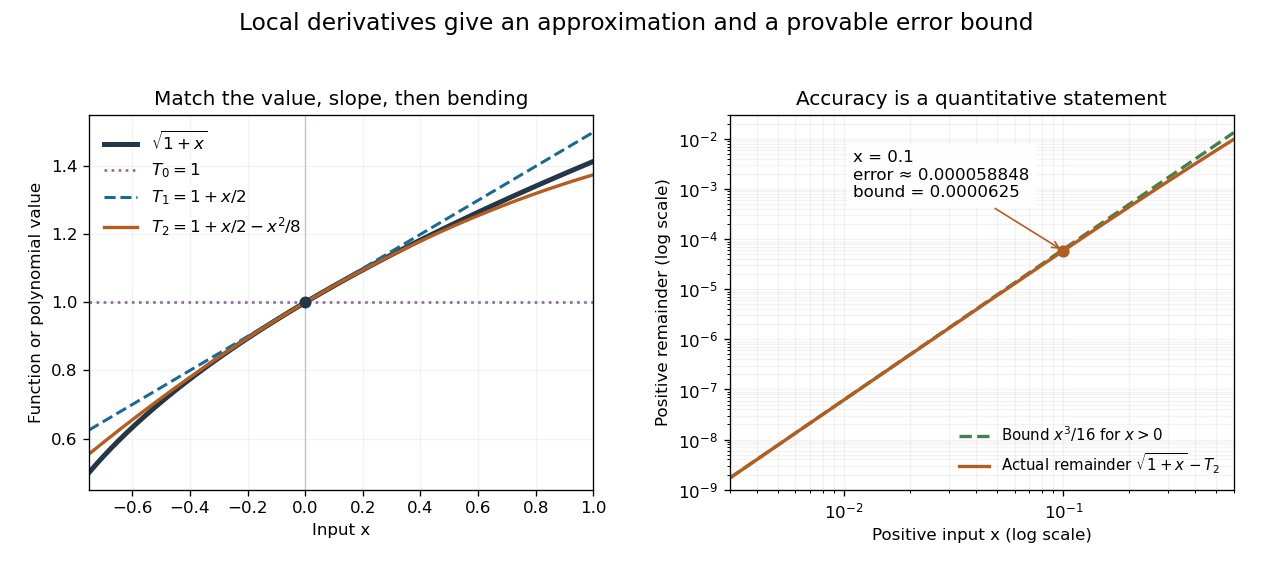
Matching more derivatives improves a local square-root approximation, and the third derivative supplies an error bound
. Details. The Taylor remainder turns this convenient approximation into a controlled calculation. On , is positive and at most . The Taylor theorem with Lagrange remainder therefore givesConsequently follows without using the displayed decimal evaluation as evidence. The Taylor polynomial and the Taylor remainder play different roles: the former supplies an answer that is easy to compute, while the latter specifies what accuracy is justified. Farther from the expansion point, the same low-degree polynomial need not remain accurate.
The quadratic Taylor polynomial of at is . Multiplying by gives , proving the exact displayed identity. Thus for every real , with equality only at one. In particular, a claim that to the right of one has the wrong sign. The Lagrange remainder also proves this direction there, since for . The exact identity is stronger: it controls the sign globally and shows the fourth-order contact at the expansion point.
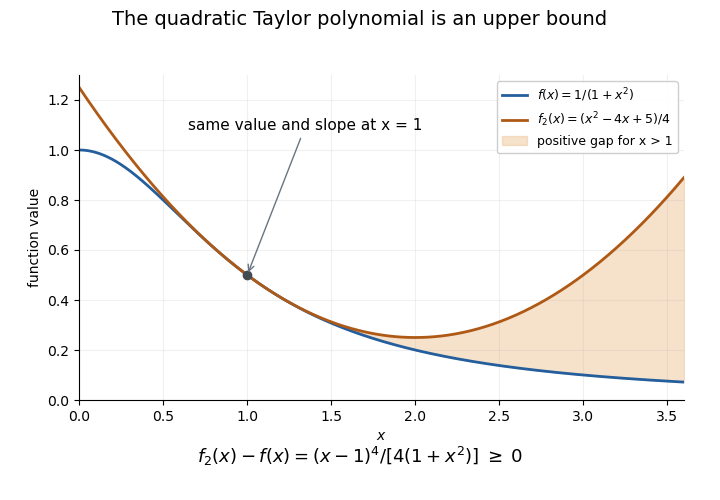
The quadratic Taylor polynomial globally majorizes the reciprocal quadratic
. Details. For positive , fixed real , and , change the inputs to with small. The ratio of the new value to the old one is exactly . Applying the binomial series to each factor and multiplying proves the displayed Taylor expansion. Positive inputs and make arbitrary real exponents well defined. A percentage change of in means , not . The mixed term is required even though there is no such term in either one-variable expansion separately.
The real exponential function converts addition into multiplication:Its values are positive, and it defines a bijection from the real numbers to the positive real numbers. The natural logarithm is its inverse function. These properties connect arithmetic with calculus: adding an amount to the input multiplies the output by a fixed factor, and the local rate of change equals the current value. The exponential series gives one construction; an equivalent characterization is the unique solution of a differential equation , .
For a concrete example, starts at and satisfies . The absolute derivative increases with , while the relative rate stays . At , and . The exponential function therefore models accumulation proportional to what is already present, rather than addition of a fixed amount at every step. A positive constant rate gives exponential growth; a negative one gives exponential decay.
Every positive real base fits the same construction through . Thus its derivative is : base is special because . The exponential function is also unchanged in form by differentiation and integration, helping explain its repeated appearance in linear ordinary differential equations. Its real definition, inverse relationship, and derivative rules are developed in OpenStax, integrals, exponential functions, and logarithms.
For fixed real , the base is positive for sufficiently large . Applying Taylor's theorem to the natural logarithm at one gives . Continuity of the exponential function then proves the displayed limit. In particular for fixed , a basic source of exponential distribution limits in probability theory.
The positive tail after term in the reciprocal-factorial series for Euler's number satisfies . The upper bound replaces each subsequent denominator factor by and sums the resulting geometric series; the lower bound retains only the first omitted term. This supplies an explicit error certificate and, with Stirling's formula, a term count of order for decimal digits. The arithmetic evaluation also has its own rounding error, distinct from this truncation bound.
A positive quantity undergoes exponential growth at constant rate when . For , the solution of a differential equation is . Every interval of duration multiplies the value by the same factor , independently of its starting value.
The interval required to double a quantity under constant-rate exponential growth. Solving with the natural logarithm gives . At per time unit, it is approximately time units; every subsequent doubling takes the same interval.
Euler's number is the value of the exponential function, approximately . It is the base of the natural logarithm. Its factorial-series tail gives an elementary proof of the irrationality of e. The compounding limit for e shows how the same constant arises from repeated small multiplications.
Start at one and apply updates, each multiplying the current value by . The final value is : one update gives , two give , ten give approximately , and one hundred give approximately . Increasing the number of steps, while reducing each increment proportionally, approaches Euler's number rather than producing unbounded accumulation.
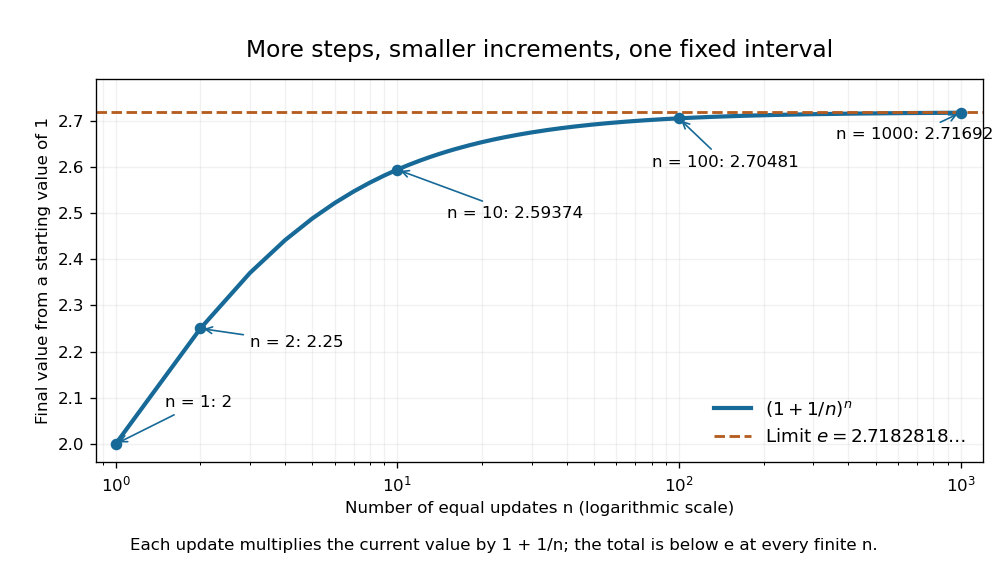
The natural logarithm makes the limit transparent. For , its integral definition gives , by bounding on . With ,The squeeze theorem gives a logarithmic limit of one; continuity of the exponential function gives . This links a discrete multiplicative rule with continuous exponential growth, without assuming that a finite number of steps equals the limiting value.
If Euler's number were , choose and multiply its factorial-series tail by . This produces an integer, but the tail is positive and smaller than . The contradiction proves that the number is an irrational number. The argument rules out a hypothetical rational remainder by placing it in an impossible integer interval.
For a positive integer , multiply the exponential series by and integrate term by term from zero to . Its uniform convergence on every compact interval justifies the operation and proves the title identity. The resulting power series converges absolutely for every real or complex , by the ratio test. Repeated integration by parts evaluates the right side as an exponential times a polynomial, with its constant chosen to make the integral vanish at zero.
The complex complex exponential function has nonzero derivative and maps the strip onto the annulus, with fibers given by translations by . It is locally conformal, but not injective. No biholomorphism from the full strip onto an annulus exists because the strip is simply connected space and the annulus has a loop of nonzero winding number. The complex exponential function is a covering map realizing that topological distinction.
For real , the complex exponential function has . Since the trigonometric factor lies on the unit circle,Thus the real part of the exponent controls its modulus, while the imaginary part controls its direction on the complex plane.
The kernel of the complex exponential function givesThe same period appears as the translation generated by the monodromy of the complex inverse sine.
For a positive real base , the logarithm is the inverse function of the exponential function :It asks which exponent produces a given positive number. Thus and . The base restrictions matter: would produce only one value, while a negative base does not define as a real-valued function for every real exponent.
The useful transformation isFor example, corresponds to in base two. Products become sums and ratios become differences. The logarithm does not generally convert a sum into a sum of logarithms. Base conversion uses the natural logarithm: . It also gives , positive when and negative when .
Historically, John Napier's 1614 Mirifici logarithmorum canonis descriptio presented logarithmic tables and their use, documented in the Smithsonian Libraries' digitized original. Tables made multiplication-heavy calculations more manageable by replacing products with addition and a lookup. The 1619 Constructio title page below belongs to a later publication from the same work on logarithms. These historical publications preceded the modern inverse function and integral presentation used here.

For integers and , the integer logarithm is the largest nonnegative integer such that . Equivalently,The equivalence follows from the monotonicity of exponentiation in its exponent and the definition of the floor function. For example, , so the base-three integer logarithm of is .
A multiplication loop maintains and accepts another factor while . Repeated squaring makes the search faster: precompute starting at , and consider these factors in decreasing . Include a factor when the accumulated product remains at most . If , the loop invariant before considering is . Accepting exactly when halves that uncertainty, proving the greedy algorithm returns . This takes arithmetic operations; it is not the same claim as this bound on bit complexity.
For positive operands in bounded integer arithmetic, test before multiplying by . Integer division makes this equivalent to while preventing integer overflow in a rejected candidate.
For positive , start at and repeatedly increment and double while . In exact integer arithmetic, the loop invariant together with or yields at exit. For fixed-width arithmetic, this proof requires every useful doubling to be representable. A signed 32-bit doubling variable becomes negative at and then zero, so the loop need not terminate for inputs above . Widening the variable to a signed 64-bit type repairs the algorithm for positive 32-bit inputs.
For the natural logarithm, define . Its derivative is , negative below one and positive above one. Thus its global minimum is , proving the bound, with equality only at one. Equivalently for ; this also follows from concavity and the tangent line at one.
For integers , rationality of is equivalent to equality of some positive integer powers . Exponentiation proves one direction and taking logarithms proves the other. Thus multiplicatively independent integers give an irrational number as their logarithm ratio. For distinct prime bases and arguments, unique factorization supplies that independence.
The logarithm is strictly concave on positive real numbers, as its second derivative is negative. Thus the Jensen inequality gives for a probability measure and an integrable positive , whenever the left side is defined. It also controls the negative logarithmic part of convex combinations of strictly positive functions.
The Cauchy principal value integral is the logarithmic integral. The offset version differs by a constant and is often used with the prime-counting function. It has .
Articles were limited to the first 100 out of 540 total.
Articles by others on the same topic

Calculus is a branch of mathematics that deals with the study of change and motion. It focuses on concepts such as limits, derivatives, integrals, and infinite series. Calculus is primarily divided into two main branches: 1. **Differential Calculus**: This branch focuses on the concept of the derivative, which represents the rate of change of a function with respect to a variable.



