For , ordinary differentiation of the two smooth components givesAt zero, use the definition of the derivative in the Euclidean norm:Thus has differentiability everywhere and . The two vectors and are orthogonal unit vectors, so the squared norm of the displayed derivative is . ConsequentlyThis discontinuous derivative of a differentiable plane curve also shows why componentwise scalar mean value theorem conclusions do not supply a single intermediate point reproducing an entire vector-valued difference quotient.
Let the mass per unit length be and the constant tension be . Small transverse displacement obeys the wave equationWith characteristic coordinates and , the equation becomes . Integrating once in each variable gives D'Alembert's formulaFor a smooth solution with vanishing endpoint energy flux, multiplication by and integration by parts giveThe fixed endpoint has . Decay of displacement alone does not guarantee either a pointwise derivative-flux limit or finiteness of the energy integral; the conservation statement is understood in the usual finite-energy class. The profile formula below proves it directly there without requiring such a pointwise limit at infinity.
The endpoint condition gives , allowing the reflected wave to be expressed through one profile:For forward time one may define the negative-argument part of this profile using the original ; no restriction on the independent initial waves is lost. Differentiation gives and . HenceThe two substitutions partition the real line at , making conservation of energy explicit.
Take outside the graph of a function, so . Since is a Hausdorff space, choose disjoint open neighborhoods of and of . Continuity makes an open neighborhood of . The product neighborhood contains and cannot meet the graph, because every with belongs to . The complement is therefore open in the product topology, provingThis is the closed graph of a map into a Hausdorff space property; no separation assumption on is required.
The map , , is continuous: the inverse image of a basic open set is . Its image is exactly the graph of a function . The continuous image of a compact space is compact, soThe compact graph of a continuous map conclusion does not need to be Hausdorff. In fact projection onto is a continuous inverse of , so the graph is homeomorphic to .
For a connected cellular embedding on the sphere, the Euler formula for a connected planar graph isThe boundary graph of a convex polyhedron has such an embedding. Counting edge ends at vertices and edge sides at faces gives . ThereforeFaces of size six contribute zero, and larger faces contribute negatively. The contribution of each triangle, quadrilateral or pentagon is at most three, soThus the small faces of a spherical polyhedral graph bound isThe tetrahedron shows that four is attainable. Connectedness and cellular faces are the standard hypotheses in this Euler formula; an arbitrary disconnected embedded graph has a different count.
Against the two pure column strategies, player one's expected payoffs are and . A mixed strategy of the opponent cannot give a smaller expectation than their minimum. The zero-sum game optimization is thereforeThe first line decreases. If , the second also decreases, and their minimum is maximized at with value . If , the second line is constantly and the first is at least , so every is optimal. For , the intersection lies at or beyond the right endpoint; the minimum increases throughout and is maximized at with value . If , the intersection lies inside the interval; the minimum increases before it and decreases afterwards. ThusFor the interior case the opponent can equalize row payoffs with first-column probability , confirming the minimax theorem value.
Let be the monic node polynomial. Suppose first that the quadrature is exact through degree . For any polynomial of degree at most , has degree at most , while every sampled value is zero. Exactness givesThus is an orthogonal polynomial of degree , proving necessity in the orthogonal-node criterion for Gaussian quadrature.
Conversely, suppose the nodes are the zeros of such a polynomial. Rescale it to be monic without changing its zeros or orthogonality. For any of degree at most , polynomial division givesOrthogonality makes ; the quadrature of is zero because . The assumed degree- exactness applies to , soHence degree- exactness is equivalent to orthogonal nodes. The given distinct-zero property ensures the node values are independent interpolation data; the degree- exactness fixes the corresponding interpolatory weights. This is the construction of Gaussian quadrature.
True. Both vector subspaces contain zero, and if , every linear combination belongs to each of and . Thus it belongs to their intersection. This proves the intersection of vector subspaces is a vector subspace.
False. Distinct vector subspaces may be nested: in , take and . Their union is , a subspace. More precisely, is a subspace exactly when one is contained in the other. If neither contains the other, choose and . Were in the union, subtracting or in the appropriate subspace would contradict those choices.
False. In let , and . Then , so , but and their sum is zero. Thus intersection need not distribute over the sum of vector subspaces. The right side is always contained in the left; this example makes the inclusion strict.
True. Choose a basis of and extend it to a basis of the finite-dimensional vector space . Put . Every basis vector belongs to , so . Linear independence of the complete basis makes a vector belonging to both spans necessarily zero. ThereforeThis constructs a direct-sum complement; it need not be unique.
Kelvin's circulation theorem states that a smooth inviscid barotropic fluid subject to a conservative body force preserves circulation around every closed material curve. Write the pressure term as with , and the body force per mass as . Then the Euler equations give . For a moving parametrization with ,The last integral is the increment of a single-valued scalar around a closed curve. ConsequentlyConstant density is a special barotropic case with . Viscosity, nonconservative forcing or baroclinic pressure gradients can invalidate this conservation law; the exterior-cylinder conclusions use the smooth inviscid hypotheses.
A simple closed loop that does not surround the cylinder bounds a surface wholly in the fluid. At time zero, Stokes theorem gives zero circulation because its vorticity is zero. The smooth impermeable exterior flow transports this loop without changing its winding about the obstacle. Pulling a loop at time back to time zero and using Kelvin's circulation theorem therefore givesThis is the contractible-loop case of irrotational circulation in an exterior domain. Equivalently, the initially vanishing vorticity remains zero under the inviscid barotropic vorticity equation.
An enclosing loop has no spanning disk wholly inside the fluid, so initial zero vorticity does not force its circulation to vanish. Kelvin's circulation theorem says only that the initial circulation is retained:For example has zero vorticity outside the cylinder but circulation around a once-enclosing positively oriented loop. Any two such loops have equal circulation, since their difference bounds an annulus in the fluid and Stokes theorem gives zero over it. More generally a loop with winding number has circulation . Thus irrotational flow need not have a single-valued velocity potential on the whole exterior domain.
A nonzero residue class is a quadratic residue if for some nonzero . If it is a square, Fermat's little theorem gives . Conversely, the map on the nonzero classes identifies exactly the pairs , giving distinct squares. They are all roots of over the field ; a polynomial of this degree has at most that many roots. Its roots are therefore precisely the squares. This proves Euler's criterionApplying it to gives . The exclusion of is the usual nonzero-residue convention needed for this equivalence.
For distinct odd primes , quadratic reciprocity statesUsing the multiplicativity of the Legendre symbol, and the supplementary law ,The first factor is because ; the second is because the reciprocity sign is positive. Thus .
For a primed inertial frame moving at speed along the positive direction relative to the unprimed frame, a Lorentz transformation isThe inverse has the opposite velocity. To avoid confusing the train speed with the ball speed, now use the primed frame for the train and write the inverse boost with train speed :The ball has on the train, so differentiation along its worldline gives the velocity-addition formulaThe time transformation is essential; simply adding the two speeds uses the Galilean rather than Lorentz relation. For positive subluminal , the result remains below , since .
The function increases for , andThus implies . Applying this to the triangle inequality for a metric proves the triangle inequality for the bounded metric transform . Symmetry and nonnegativity are immediate, and exactly when , so .
Each is compact and lies inside , so the supremum norm is finite for continuous . Every summand of lies between zero and , giving absolute convergence and . Symmetry is inherited from these norms. If , all the nonnegative summands vanish, hence on every ; their union is , so everywhere. Finallyand the subadditivity already proved give the triangle inequality term by term and then after summation. Therefore . This is a weighted metric for local uniform convergence, representing the compact-open topology.
The geometric-series sum is and its remainder is . Writing , the triangle inequality givesEquality occurs at the positive real point . ThusFor every integer , split the defining sum into a finite head and its tail. Since and ,Given , choose with . For that fixed , each of the finitely many displayed norms tends to zero, so their sum is below for sufficiently large . Hence , even though convergence is not uniform on the whole open disk.
Use the weighted inner product . For real eigenfunctions, integration by parts with the zero endpoint values givesThus . The regular separated Sturm-Liouville problem has simple eigenvalues: for a fixed eigenvalue, prescribing leaves only the initial flux free, so uniqueness of the associated first-order system makes any two eigenfunctions proportional. Distinct eigenfunctions are therefore orthogonal, and choosing their signs and scales so that givesThe positive energy form realizes as a positive self-adjoint operator in this weighted space, with compact inverse on the bounded interval. The spectral theorem for compact self-adjoint operators supplies a complete eigenbasis. This is the standard regular Sturm-Liouville eigenfunction expansion, also valid with continuous by working with the continuous flux .
For a source , expand a zero-endpoint solution of in that basis. Multiplication by and unweighted integration giveSince is not an eigenvalue, every coefficient is determined. The spectral Green function of a regular Sturm-Liouville problem is consequentlyWeighted completeness means as a distribution, so applying to this series produces the required delta source. The source integration is with , explaining the absence of an additional factor in the stated kernel.
For the subsequent operator the sign is explicitly reversed: and . To cover every real non-eigenvalue , define the homogeneous solutionIt satisfies , and . Matching the two endpoint solutions continuously at with derivative jump yieldsThe denominator is nonzero precisely off the Dirichlet eigenvalues . In particular . At , its spectral expansion givesThis odd reciprocal-square sum from a Dirichlet Green function proves .
For , put . On the curve, , so no member of this homotopy has a boundary zero. The argument principle counts the interior zeros, with multiplicity, by its winding number . For a piecewise smooth curve this isThere are no poles, and the null-homotopy of the Jordan curve in the domain permits this interior count. The loops form a continuous homotopy avoiding zero, so their integer winding number stays constant. Equivalently, for a piecewise smooth curve the integral varies continuously with and is integer-valued. In particularThis proves Rouché's theorem. The counting is with multiplicity and assumes the usual positive orientation; reversing orientation reverses both winding counts without changing the conclusion.
The function is holomorphic on a neighborhood of the closed unit disk. On , the mapping assumption gives . Apply Rouché's theorem to and . Their sum has the same number of interior zeros as , namely one counting multiplicity. ThusThe zero is simple since its total multiplicity is one. No boundary fixed point is possible because maps the boundary strictly inside.
For nonnegative integers , put . Since , the denominator has no zero on or inside the unit circle. On ,so . Consequently , and Rouché's theorem gives the same interior zero count for as for . The latter has zeros at zero and at , with the multiplicities combining when . ThereforeThis is the interior zero count for a finite Blaschke product minus a constant. If , the nonzero constant has zero zeros, so the same conclusion includes that endpoint case.
Let and . Distance preservation and polarization give . The vectors form an orthonormal basis, and . Hence for an orthogonal matrix . Every Euclidean isometry is therefore .
To decompose , if reflect in the origin plane normal to . This reflection sends to . The remaining orthogonal transformation fixes and acts on its two-dimensional orthogonal complement; repeat with , and then on the last one-dimensional complement. At most three plane reflections are needed. A translation is itself a product of two reflections in parallel planes: for , reflecting first in and then in gives that translation. Thus every isometry is a finite composition of plane reflections, the finite reflection decomposition of a Euclidean isometry.
For an isometry fixing zero, the preceding construction gives . A plane reflection's linear part has . The identity implies that a product of such linear parts has rank of at most , even if the reflecting planes are affine. For central inversion , this rank is three. The reflection length of a Euclidean orthogonal map therefore gives
For the regular tetrahedron, center it at zero. Every permutation of its four vertices determines an isometry, and the orientation-reversing ones correspond to odd permutations in : six transpositions and six four-cycles. Each transposition is a plane reflection fixing the two unswapped vertices; its plane contains their edge and the midpoint of the opposite edge. These give six distinct mirror planes.
The other six are rotoreflections: rotate by or about an axis through the midpoints of a pair of opposite edges, and then reflect in the plane through the center perpendicular to that axis. There are three axes and two senses. For vertices , the map is one such four-cycle; the other axes and inverse rotations give all six. Hence the complete orientation-reversing tetrahedral symmetry list is six mirror reflections and six quarter-turn rotoreflections.
Introduce surplus variables , slack , and artificial variables , all nonnegative. The two-phase simplex standard-form equations arePhase I maximizes . An initial basic feasible solution has basic variables and all others zero. Its simplex dictionary isLet enter. The simplex ratio test gives from the row and from the row, so leaves. After this pivot,Choose to enter; the limiting ratios are and , so leaves. The resulting dictionary isThus , attained at with . Since for every feasible Phase I point, this proves feasibility and completes Phase I.
Delete the artificial variables and restore the original objective . The resulting Phase II dictionary isLet enter; only decreases, and it reaches zero at . Pivoting givesAn optimal simplex tableau, with each row recording its equality, isBoth reduced costs in the maximization dictionary are negative. Setting nonbasic therefore givesAs a direct optimality check, implies ; the displayed point attains both equalities.
Since every eigenvalue has modulus less than one, is not an eigenvalue and is invertible. Hence the iteration has a unique fixed point . The stated consistency implication gives , and nonsingularity of identifies . This justifies using the fixed-point relation even though consistency was stated in only one direction.
Expand the initial error in the eigenvector basis, . Subtract the fixed-point equation from the stationary iterative method for a linear system and iterate:With , any norm obeys . ThusThe argument uses the given diagonalizable eigenbasis; the more general convergence criterion is spectral radius less than one.
Write , with diagonal, and use only old iterates on the right side. The Jacobi method isStrict row diagonal dominance ensures every . The exact solution satisfies the same coordinate relation. For , subtraction givesTaking the maximum and iterating provesThis direct contraction proof requires no eigenvector assumption and applies to every strictly diagonally dominant matrix with the stated uniform .
Over a commutative field, define the determinant by the signed permutation sumIt is linear in each row separately. Swapping two rows reindexes the permutations by a transposition and reverses the sign; thus a matrix with two equal rows has determinant zero. Adding times row to a different row consequently givesThese are immediate consequences of the definition, not assumptions about elementary row operations.
For the block upper-triangular matrix, a nonzero permutation term must assign every bottom row to one of the last columns, because its first entries are zero. Those rows use all the last columns; the top rows must use all the first columns. The sign and products factor into two independent -permutations, givingIn particular has determinant . For each bottom row , subtract times top row for . The top rows remain unchanged, so these additions producewithout changing the determinant. Exchange its first and last blocks of columns; the permutation has sign and gives . HenceSince and have the same parity, . Combining the two evaluations provesNo invertibility of or was used, so the proof includes singular matrices.
For steady uniform-density inviscid flow with no body force, the Euler equations read . Dotting with givesThus the Bernoulli equation states that is constant along each streamline; the constants need not be the same on unrelated streamlines.
In the slowly varying tube approximation, mass conservation gives , so . The upstream Bernoulli constant and the wall pressure law giveSubtracting the internal radius obtainsThis is choking by wall thickness in an elastic tube. The function tends to as either or , and . Its derivative isIt is positive before and negative afterwards, so the unique maximum isThe maximum is nonnegative because the arithmetic-geometric mean inequality gives ; it is zero only at . If any prescribed thickness exceeds , no positive velocity can satisfy the mass/Bernoulli conditions there, so no flow of this assumed form is possible. Equality is the double-root critical case.
For each , strict monotonicity on and , together with the two negative-infinite limits, gives exactly two positive roots. The upstream condition is as . ThereforeFor , the upstream value lies on the rising branch; for , it lies on the falling branch. Smooth continuation preserves this choice because the branches meet only at , which is excluded by the strict bound. At the upstream state is already critical: , so the requirement cannot hold, and any positive wall thickness is incompatible with the approximation. With the critical root is .
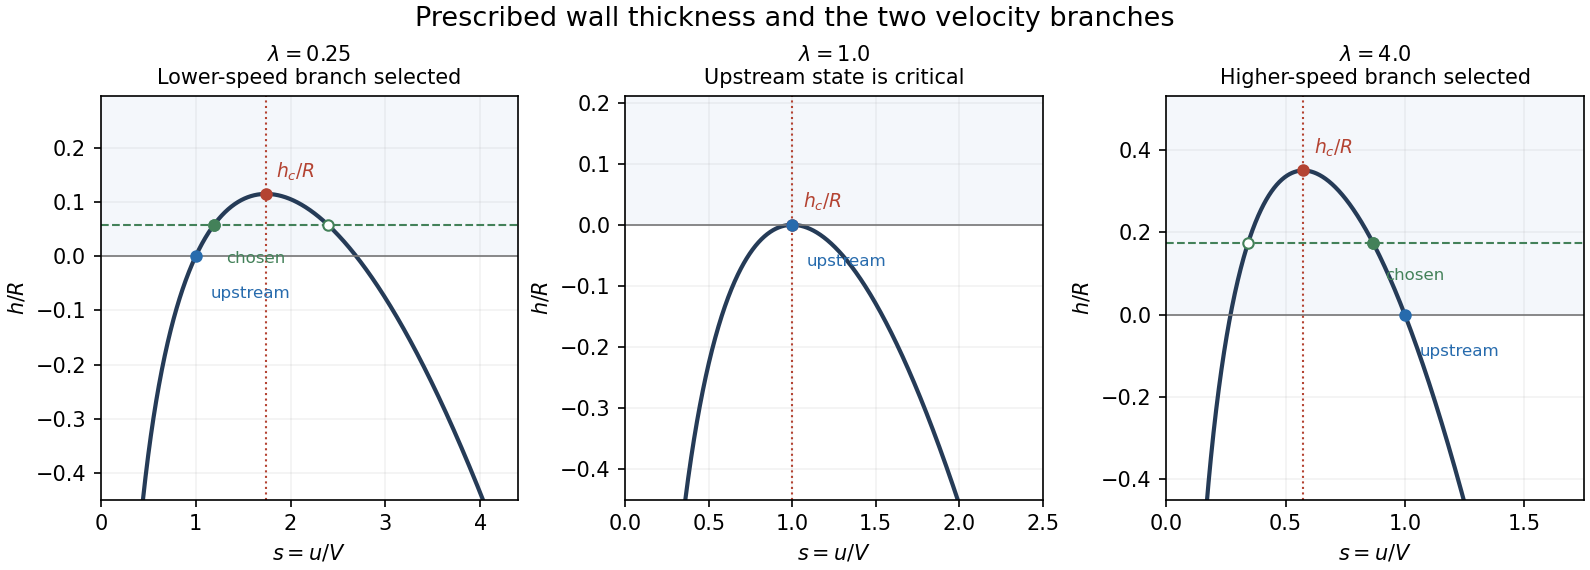

The graph shows the unique maximum and the upstream point on the three parameter regimes. Only the portion with represents nonnegative wall thickness. The vertical maximum line separates the two roots when the prescribed thickness lies strictly below the maximum.
Use the standard reduced-form convention , with when or . To reduce a positive definite integral binary quadratic form, choose a primitive integer vector at which the positive integer value is least. Complete that vector to a unimodular basis; it makes the leading coefficient that least value. A shear of the second basis vector by an integer multiple of the first replaces by , allowing . The new is the value at another primitive vector, hence . If , a shear makes without changing ; if and , the determinant-one swap reverses its sign. Thus every form is properly equivalent to a reduced positive definite binary quadratic form. This argument also gives the reduction algorithm for a positive definite binary quadratic form by successively decreasing its positive leading coefficient.
For a negative integral discriminant or , a prime is represented by some integral form of discriminant exactly whenIndeed a representing vector is primitive, since a common divisor of its coordinates would have its square divide . A unimodular change takes it to the first basis vector, giving a form and . Conversely a solution gives the positive definite form , which represents at . For odd this is the discriminant criterion for prime representation by a binary quadratic form: must be a square modulo , with parity chosen to satisfy the modulo-four condition.
For and odd , the Legendre symbol is . The supplementary laws make it positive exactly for . The prime also works directly, since has discriminant and represents . ThereforeThe class here consists only of the prime .
For a reduced form, , so . The integer checks yield the reduced forms of discriminant minus thirty-two:If one omits the boundary sign convention, also appears, but is properly equivalent to . The middle form is imprimitive and represents no odd integer. An odd integer represented by has odd and is . For to be odd, one of must be odd and the other even; substitution modulo eight gives in either case. If both are odd or both even, the value is even. Thus a prime represented by the last form is necessarily .
Conversely, a prime is represented by some discriminant- form, which reduces to one of the three displayed forms without changing its represented integers. The first and second cannot represent it, so the third must. ConsequentlyThe prime is not an exception for this particular form: its minimum positive value is , as also follows from .
The Time-dependent Schrödinger equation is . The normalized eigenstates of the Hermitian Hamiltonian with distinct eigenvalues are orthogonal, so they form an orthonormal basis of this two-state system. Substitute the expansion of and compare the two coefficients:Hence and . For the normalized test state , the Born rule givesThe complex conjugates are essential; relative phases can affect this probability even though the energy-state populations remain constant under .
In the ordered eigenbasis, , a Pauli matrix. The coefficient equations are and , with , . Differentiating the first gives , and its initial derivative vanishes. ThusThe population of is . To be an eigenstate of eigenvalue , the coefficient of must vanish. Its first positive zero isThe global phase does not change its eigenstate or measurement probabilities.
Here and . Its time evolution for an additional interval isAt , . Acting on the state from the previous part givesIt differs from the initial state only by a global phase. For every observable or projection the phase cancels between bra and ket, so the final state is observationally indistinguishable from the original isolated state. A relative phase between two components or between coherently controlled alternatives would be observable; this overall phase of the entire state is not.
Articles by others on the same topic
There are currently no matching articles.