Topics (384k) Articles (398k) Users (410) Discussions (242) Comments (383) Files (13k) New article
The coefficient of is . The Mahler expansion of continuous p-adic functions identifies -valued p-adic measures on with . If , then . A measure supported on has , because the sum of is zero for .
Let be a complete discrete valuation ring with a continuous -algebra structure. Every continuous function on with values in has a unique uniformly convergent expansion in the binomial polynomials, with . This is the coefficient-ring version of the Mahler theorem. To see that , approximate the function modulo any power of the maximal ideal by a function of period . In the expansion of , all intermediate binomial coefficients are divisible by , while kills the periodic function. Iterating makes its differences vanish modulo the prescribed ideal power. Finite differences do not increase the uniform norm, so the same conclusion holds for the original function. Binomial inversion gives agreement at the nonnegative integers, and their density in the p-adic integers gives the expansion everywhere. This gives the dual description of p-adic measures by arbitrary bounded sequences of binomial moments, and hence the Amice transform.
Write and . The first mean condition implies eventually. For , this yields , and each fixed- term tends to zero when . The second mean condition implies eventually. Writing gives for , and . Both bounding series are summable. The overlap formula for the variance of a clique count therefore gives relative variance tending to zero; the second moment method proves an -clique exists with high probability.
Underfitting occurs when a prediction rule fails to capture useful structure in the target relation. A straight-line polynomial regression fitted to a genuinely quadratic noiseless target illustrates a representational limitation. Poor prediction alone does not identify the cause: compare candidate rules using cross-validation or a validation set, while keeping the final test set reserved for assessment.
The structure containing the angiosperm female gametophyte; a fertilized ovule can develop into a seed.
For a nontrivial Non-Archimedean absolute value on , every integer has absolute value at most one. Some prime must have value less than one, or the value would be trivial on every rational number. Two distinct such primes are impossible by a Bezout identity. Prime factorization then gives the displayed formula. Distinct primes give inequivalent topologies, since powers of tend to zero only for the -adic absolute value among these values.
Take two reservoirs separated by a semipermeable membrane that passes water and retains one neutral solute. Stipulate , and , equivalent to and . Treat both chemical solutions as dilute and ideal. These are invented model conditions, not measurements or recommended biological conditions.
For pressures measured at the same height beside the membrane, define . The model predictsAt , net water transfer favors A to B. At , the opposing pressure balances the osmotic pressure difference, giving zero net transfer with unequal concentrations. At , the sign reverses and net water transfer favors B to A, toward the more dilute reservoir. Raising pressure changes the total water potential, rather than changing the membrane into a one-way gate.
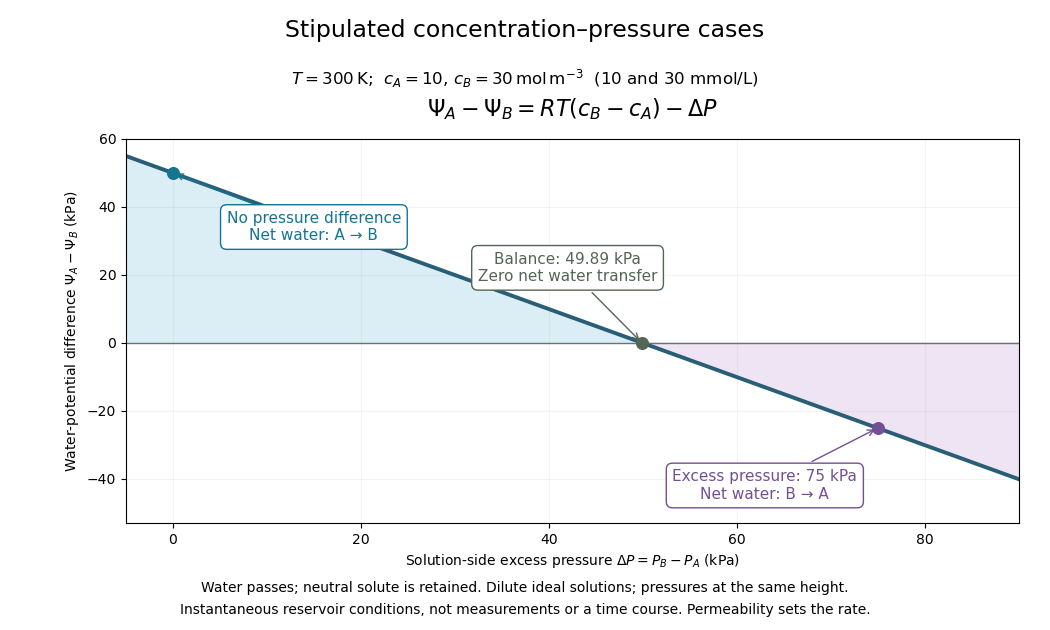
Fixed concentrations require large maintained reservoirs or an instantaneous comparison. In a closed membrane osmometer, entering water causes dilution of the receiving chemical solution and changes its volume; the final balance must use final concentrations. A supported cell wall provides another way to develop the opposing pressure, as explained under turgor pressure.
A circular distant barycentric Kepler orbit around a circular star–planet binary need not have constant star-centred osculating orbital elements. Let be the planet's fraction of the binary mass, , and . Subtracting the stellar reflex velocity produces radial and tangential perturbations , where is the planet's longitude minus the particle's longitude. The vis-viva equation gives the displayed semi-major axis variation. The eccentricity vector components follow from and . The errors are ; the spatial translation itself is only . These are changes of instantaneous orbital description, even when the assumed barycentric trajectory is fixed.
Tensor products of the assigned vectors represent strong graph powers, and tensor products of the handle have squared inner products equal to products of the original ones. The vectors assigned to an independent set are orthonormal. Bessel inequality then bounds its size by the largest inverse squared handle inner product. Taking roots and minimizing proves .
Represent unit-radius de Sitter spacetime by the spacelike unit hyperboloid in five-dimensional Minkowski spacetime. Appending its position vector as the last column of an oriented pseudo-orthonormal frame produces a matrix in . Projection to that last column identifies with the oriented orthonormal frame bundle, a principal bundle with group . The full bundle allowing both orientations is with group . Requiring a time orientation as well selects the corresponding identity components.
An oriented pseudo-orthonormal frame in Minkowski spacetime consists of its base point and a Lorentz matrix acting on a fixed reference frame. The pairs form the Poincaré group, and right multiplication by sends the frame to while fixing its base point. Thus the displayed projection is a principal bundle with group . The full frame bundle uses ; a specified time orientation restricts to the corresponding connected component.
Represent the Anti-de Sitter spacetime quadric by in . Appending its timelike unit normal to an oriented tangent pseudo-orthonormal frame identifies the frame bundle with . The stabilizer of that normal is , so projection realizes as the base of a principal bundle. For the commonly used universal cover of the anti-de Sitter quadric, pull this bundle back along the covering map; the quadric itself has a periodic timelike coordinate.
For a thermal inertial Langevin equation conditioned on fixed initial position and velocity, the centered displacement is . With the fluctuation-dissipation relation for a Langevin particle, and integrating the squared kernel gives the displayed variance. At short times it is per component; at long times it is . Averaging initial velocity over thermal equilibrium adds a ballistic contribution and gives per component.
Let , , and , . The logarithm is a centered Gaussian random variable of variance . Squaring the stochastic kernel and integrating proves this formula. The exponential moment of a Gaussian linear functional gives and the displayed long-time growth exponent. Positive moment growth with zero mean strain reflects the breadth of the log-normal distribution; it does not imply positive growth of the mean logarithm.
Ornstein-Uhlenbeck stochastic differential equation by  Codex 0 Created 2026-10-14 Updated 2026-11-05
The linear stochastic differential equation has the explicit solution . Its integrating factor is . For , an independent initial normal variable of variance makes its zero-mean Gaussian process stationary.
Exponential Brownian time change to a stationary Ornstein-Uhlenbeck process by Codex 0 Created 2026-10-14 Updated 2026-11-05
Codex 0 Created 2026-10-14 Updated 2026-11-05For , set and . This is a Brownian motion in the new filtration; its independent Gaussian increments have variance equal to elapsed time. The Itô product rule gives . Its initial value is , independent of future W increments, and its covariance function is . Consequently it is a stationary Ornstein-Uhlenbeck process. The quadratic variation of the unscaled time change is , not .
For an adapted stationary process with the displayed bounds, the Itô formula and stationarity give . The Cauchy-Schwarz inequality makes each integrand nonnegative, so equality holds almost everywhere. Then , proving for almost every time and outcome. Thus the process solves the Ornstein-Uhlenbeck stochastic differential equation and its initial value, rather than stationarity alone, determines its coupling with W.
For any step , set . The Ornstein-Uhlenbeck transition distribution gives the exact updateusing a fresh independent standard normal random variable for each interval. The update reproduces the joint probability distribution on the selected time grid. It can start from a fixed value or use Ornstein-Uhlenbeck stationary initialization. On an equally spaced grid it is an autoregressive process of order one after subtracting . Its stationary variance follows directly from .
For the stipulated example with , and the innovation variance is . Given , the next conditional expected value is about and the conditional standard deviation is about .
The Euler-Maruyama method instead approximates the same stochastic differential equation byFor its stationary variance solves , givingAt in the example, this is , about above the continuous model's stationary variance. If , this Euler recurrence has no finite stationary variance despite the stable continuous model. Exact transitions avoid this discretization error at sampled times; neither update alone determines the unresolved motion between samples.
Set and draw independently of future Brownian increments. The Ornstein-Uhlenbeck process is then a strictly stationary process, withEvery time has the same normal distribution, and the covariance function depends only on the time lag. For a Gaussian process these properties also make all its finite-dimensional distributions invariant under a common time shift. The stationary distribution balances the continual random forcing against the contracting drift.[ref]
Applied Stochastic Differential Equations by Simo Särkkä and Arno Solin. Applied Stochastic Differential Equations, Example 6.8, printed pp. 91–92, equations (6.73)–(6.76): steady-state variance and covariance
With a fixed , the covariance function instead isIn particular, it is zero when , since the initial value has no uncertainty. The second term records the fixed start; it is the general scaling of the zero-start Ornstein-Uhlenbeck covariance. The pure exponential covariance function displayed above assumes stationary initialization. For a fixed start, that function emerges as the late-time limit at fixed lag, while the one-time probability distributions approach by convergence in distribution.
For the stipulated , , , stationary initialization has variance one from the outset. Its autocorrelation is , so the correlation time is one: a lag of one reduces the autocorrelation to . Its raw second moment includes the squared expected value; it must not be confused with the covariance.
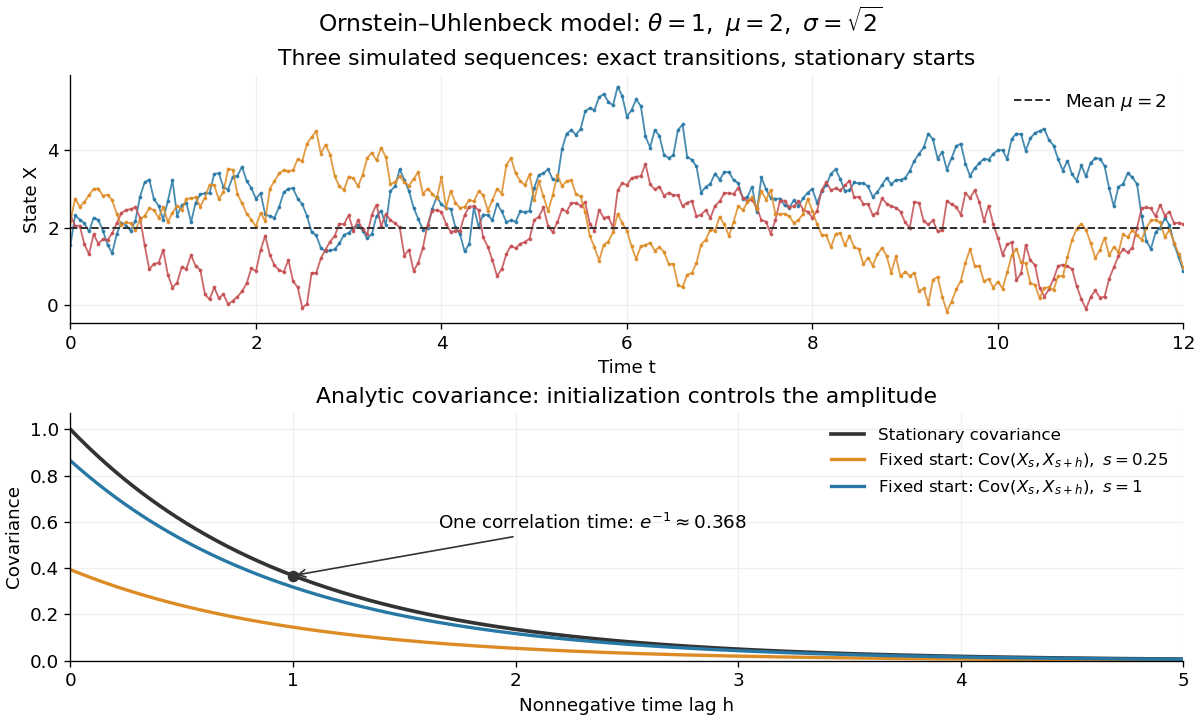
Simulated stationary Ornstein-Uhlenbeck samples and analytic covariance compared with a fixed start
. Details. The upper panel shows three simulated sequences with independent stationary initial values and exact transitions at spacing . Joining their points only guides the eye; it does not simulate a continuous sample path between those points. The lower panel shows analytic covariance functions: the stationary curve and, for comparison, for fixed initialization at two different ages . These are simulated samples and model curves, not measured trajectories or empirical covariance estimates.
For a fixed initial value , the Ornstein-Uhlenbeck process has the normal distributionThe two parameters of are the expected value and variance, not the standard deviation. At the variance is zero and the value is fixed. More generally, its transition kernel over any interval of length has conditional expected value and conditional variance when the current value is . The coefficients depend on elapsed time; the initial probability distribution determines whether the resulting stochastic process is stationary.[ref]
In the stipulated example , , , , the expected value at time two is and the variance is . The initial distance from two has fallen by a factor , but the standard deviation has grown to about . Approaching the reference level in expected value is compatible with growing uncertainty from a perfectly known initial value.
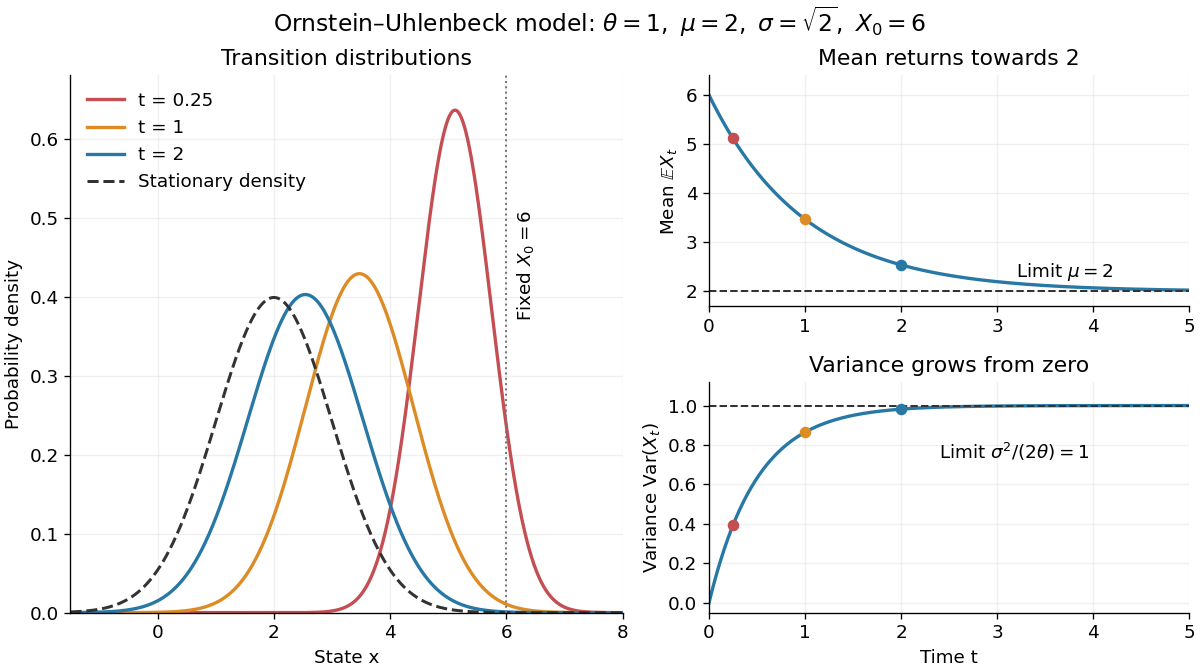
Ornstein-Uhlenbeck transition densities, mean relaxation and variance growth from a fixed initial value
. Details. The solid probability density functions use times , and ; the dashed curve is the limiting normal distribution with expected value two and variance one. The curves are exact model predictions. There is no ordinary density for the fixed value at time zero.
A short derivation uses the integrating factor . The Itô product rule gives , henceThe stochastic integral has zero expected value. The Itô isometry gives its variance as . Its deterministic integrand makes it a Gaussian random variable, yielding the displayed normal distribution. Shifting the integration interval gives the same transition kernel from any later time.
Pinned article: Introduction to the OurBigBook Project
Welcome to the OurBigBook Project! Our goal is to create the perfect publishing platform for STEM subjects, and get university-level students to write the best free STEM tutorials ever.
Everyone is welcome to create an account and play with the site: ourbigbook.com/go/register. We belive that students themselves can write amazing tutorials, but teachers are welcome too. You can write about anything you want, it doesn't have to be STEM or even educational. Silly test content is very welcome and you won't be penalized in any way. Just keep it legal!
Intro to OurBigBook
. Source. We have two killer features:
- topics: topics group articles by different users with the same title, e.g. here is the topic for the "Fundamental Theorem of Calculus" ourbigbook.com/go/topic/fundamental-theorem-of-calculusArticles of different users are sorted by upvote within each article page. This feature is a bit like:
- a Wikipedia where each user can have their own version of each article
- a Q&A website like Stack Overflow, where multiple people can give their views on a given topic, and the best ones are sorted by upvote. Except you don't need to wait for someone to ask first, and any topic goes, no matter how narrow or broad
This feature makes it possible for readers to find better explanations of any topic created by other writers. And it allows writers to create an explanation in a place that readers might actually find it.
Figure 1. Screenshot of the "Derivative" topic page. View it live at: ourbigbook.com/go/topic/derivativeVideo 2. OurBigBook Web topics demo. Source. - local editing: you can store all your personal knowledge base content locally in a plaintext markup format that can be edited locally and published either:This way you can be sure that even if OurBigBook.com were to go down one day (which we have no plans to do as it is quite cheap to host!), your content will still be perfectly readable as a static site.
- to OurBigBook.com to get awesome multi-user features like topics and likes
- as HTML files to a static website, which you can host yourself for free on many external providers like GitHub Pages, and remain in full control

Figure 2. You can publish local OurBigBook lightweight markup files to either OurBigBook.com or as a static website.
Figure 3. Visual Studio Code extension installation.
Figure 5. . You can also edit articles on the Web editor without installing anything locally. Video 3. Edit locally and publish demo. Source. This shows editing OurBigBook Markup and publishing it using the Visual Studio Code extension. 
- Infinitely deep tables of contents:




All our software is open source and hosted at: github.com/ourbigbook/ourbigbook
Further documentation can be found at: docs.ourbigbook.com
Feel free to reach our to us for any help or suggestions: docs.ourbigbook.com/#contact