
Hyperbolic cosine Created 2026-09-24 Updated 2026-10-14
The hyperbolic cosine is the even functionIt has derivative and second derivative , so it is a strictly convex function. Its unique global minimum is , and its image is . For example, . On the unit hyperbola, the hyperbolic cosine is the horizontal coordinate; as a graph against , it is a symmetric bowl.
Its Taylor series beginsThe positive fourth-order term explains why the bowl resembles a parabola near its minimum yet differs from one away from it. Restricting to gives the inverse hyperbolic cosine.
Gaussian function Created 2026-09-24 Updated 2026-09-24
A Gaussian function has the form with . Its integral and moments reduce by translation and scaling to the Gaussian integral.
Logarithm Created 2026-09-24 Updated 2026-10-20
For a positive real base , the logarithm is the inverse function of the exponential function :It asks which exponent produces a given positive number. Thus and . The base restrictions matter: would produce only one value, while a negative base does not define as a real-valued function for every real exponent.
The useful transformation isFor example, corresponds to in base two. Products become sums and ratios become differences. The logarithm does not generally convert a sum into a sum of logarithms. Base conversion uses the natural logarithm: . It also gives , positive when and negative when .
Historically, John Napier's 1614 Mirifici logarithmorum canonis descriptio presented logarithmic tables and their use, documented in the Smithsonian Libraries' digitized original. Tables made multiplication-heavy calculations more manageable by replacing products with addition and a lookup. The 1619 Constructio title page below belongs to a later publication from the same work on logarithms. These historical publications preceded the modern inverse function and integral presentation used here.


Variance function Created 2026-09-24 Updated 2026-10-14
Scaled centered risk under concave utility Created 2026-09-24 Updated 2026-09-24
If is concave and , thenis concave in . By Jensen inequality, ; concavity then makes nonincreasing on .
Optimized affine shift of concave utility Created 2026-09-24 Updated 2026-10-14
Let be a vector space of random variables and supposehas an optimizer for every . If is increasing and concave, then is increasing and concave. For concavity, combine optimizers at two values using the same convex coefficient as the values themselves.
Four-state reflecting absorbing random walk Created 2026-09-24 Updated 2026-11-05
For the chain with absorbing, equal-probability nearest-neighbour moves between , and a probability- self-loop at , starting from the expected Absorption time is , the Probability of visiting before is , and the expected number of visits to before absorption is .
Scattering slope of a transmission spectrum Created 2026-09-24 Updated 2026-09-24
Atmospheric scale height Created 2026-09-24 Updated 2026-11-05
The atmospheric scale height measures how quickly pressure decreases upward. In an isothermal ideal gas with nearly constant gravitational acceleration, hydrostatic equilibrium givesHere is the Boltzmann constant, the temperature, the mean particle mass, and the gravitational acceleration. Rising by one atmospheric scale height reduces pressure and number density by a factor . Hotter, lighter gas has a larger atmospheric scale height; stronger gravity compresses it.
For a thin exoplanet atmosphere, a feature spanning such heights contributes roughly to the exoplanet transit depth. This explains why light molecular hydrogen-rich envelopes are favourable for transit spectroscopy. It is the atmospheric application of the general scale height.
Thermal eclipse depth Created 2026-09-24 Updated 2026-10-06
For blackbody star and planet, define the planet-star contrastA complete exoplanet secondary eclipse removes the planet's light from the combined out-of-eclipse light. Its exact normalized depth is . The common approximation requires . This thermal model omits reflected light and spatial variations.
Geometric albedo Created 2026-09-24 Updated 2026-11-05
The geometric albedo measures a body's brightness at full phase relative to a perfectly reflecting, diffusely scattering flat disc of the same projected area, illuminated identically. It is therefore a directional brightness comparison. For an unresolved spherical planet at separation , the full-phase reflected contrast is under the usual distant-source approximation.
An optical exoplanet secondary eclipse can constrain this contrast after accounting for planetary thermal radiation. The geometric albedo differs from Bond albedo, which measures reflected power over every direction and wavelength. Strong backscattering can even make a directional geometric albedo exceed one without violating conservation of energy; total reflected power remains bounded by the incident power.
Heralded exact quantum period finding when the period divides the register size Created 2026-09-24 Updated 2026-11-05
Suppose a function on has least period and is injective on each period. A Fourier sample gives the candidate denominator . If equality of function values can be tested efficiently, then is the full period exactly when , so each successful run is certified. A sample succeeds with probability , and an inverse-polylogarithmic lower bound for this ratio permits amplification to constant success probability with polynomially many repetitions.
Canonical divisor of an even-degree hyperelliptic curve Created 2026-09-24 Updated 2026-09-24
Compactification of y squared equals x to the eighth minus one Created 2026-09-24 Updated 2026-09-24
The affine germ surface over the plane with the eight roots of unity removed is compactified by adding the eight simple branch points above those roots and two unbranched points above infinity. The degree-two map to the Riemann sphere has total ramification eight, so the Riemann-Hurwitz formula gives genus three.
Forward-start call option Created 2026-09-24 Updated 2026-10-31
A forward start option whose call option strike is fixed at time as , with expiry and . Its terminal financial payoff depends on the intermediate stock price as well as the final price. Two paths ending at the same price can therefore have different payoffs, so a recombining stock tree must retain enough history to value the contract.
In a homogeneous dividend-free Black-Scholes model, let be the European call option price with current stock one and strike over the remaining duration. Homogeneity gives value when the strike is fixed. The discounted stock is a martingale, so risk-neutral pricing before that date givesThe same argument holds in a homogeneous binomial options pricing model with the corresponding remaining-step call value. It depends on the normalized future pricing rule being independent of the stock level at the fixing date.
Binomial call-price recursion Created 2026-09-24 Updated 2026-11-05
Let a binomial options pricing model multiply the stock price by or in each period, with and bank account gross return . The unique one-step risk-neutral probability is . If is the time-zero price of an -period call option starting at with strike , thenThis is conditional expectation after the first move, with one period of discounting. The terminal payoff's positive homogeneity gives for , henceThe coefficients are positive because the no-arbitrage inequalities put strictly between zero and one. This strike-rescaling recursion is useful when the shorter-maturity call curve is available. The physical up probability does not enter the recursion.
Put-call parity Created 2026-09-24 Updated 2026-10-14
Put-call parity fixes the price difference between a European call option and a European put option on the same underlying stock, with the same strike price and expiry . Assume no dividends or other payments from the stock before or at expiry, a known constant continuously compounded interest rate , and a frictionless market. Borrowing and lending are available at that same interest rate; short selling of the stock, European call option, European put option, and zero-coupon bond is permitted. Settlement is certain, and the buy-and-hold portfolios below may be held until without interim funding restrictions or forced liquidation. These assumptions exclude transaction costs, taxes, borrowing fees, and execution or settlement risks from the arbitrage argument.
At expiry, the two positive parts cancel their corners:Thus a European call option and a short European put option together have the same terminal financial payoff as one stock share with a debt of . A particularly readable claim replication uses two portfolios with nonnegative terminal amounts: portfolio A holds one European call option and a risk-free zero-coupon bond paying at ; portfolio B holds one European put option and one stock share. The zero-coupon bond costs today, since the discount factor is . There are no intermediate cash flows. For every terminal stock price,For the strike price , even the following very different outcomes leave the two portfolios equal:
| Terminal stock price | A: European call option + zero-coupon bond | B: European put option + stock |
|---|---|---|
The law of one price forces in this setting: otherwise buy the cheaper portfolio and sell the more expensive portfolio using short selling. Their terminal obligations cancel in every scenario, while the initial price difference can grow in the bank account. Hence absence of arbitrage givesWith a constant per-period interest rate over discrete periods, the same reasoning gives . This is a different compounding convention; is not the continuously compounded interest rate .
For an illustrative stock price , strike price , expiry one year away, interest rate per year, and given European call option price , put-call parity requiresBoth portfolios therefore cost approximately . The inputs specify no stock price dynamics: is supplied for illustration, not calculated from the Black-Scholes model. Put-call parity determines the European put option price conditional on that European call option price; it does not determine both prices by itself. At zero interest rate, the same and give the exact result .
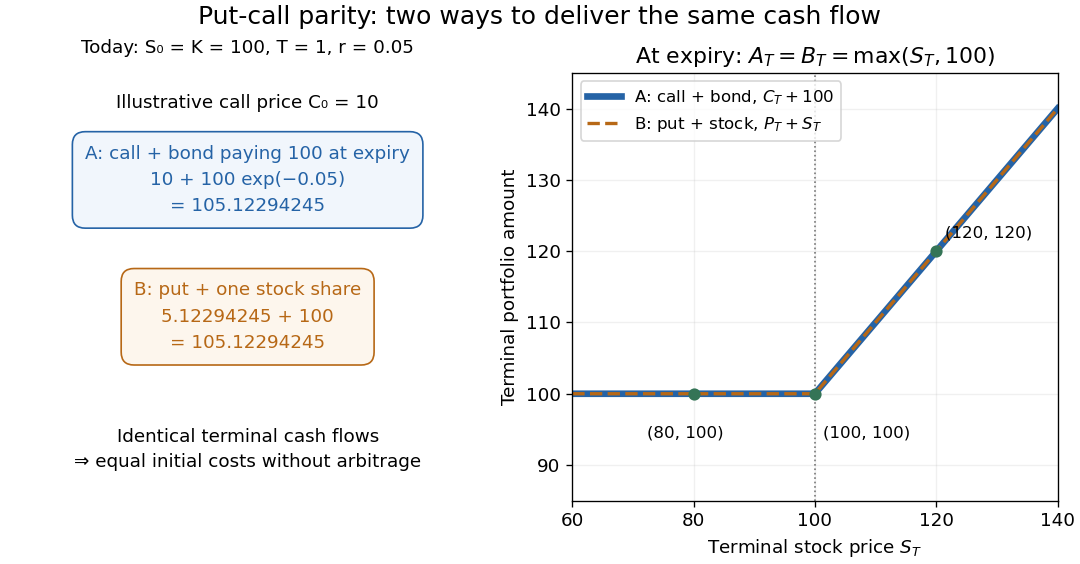
Two portfolios with identical terminal cash flows and equal initial costs under put-call parity
. Details. 
To compute both directions of arbitrage, keep all the preceding inputs except the quoted European put option price. If it is , portfolio B costs while portfolio A costs . Buy A, sell B, and place the initial surplus in the bank account. At expiry, A and the obligations from selling B cancel exactly, leaving in every scenario. If the European put option instead costs , buy B for and sell A for ; the initial surplus is approximately , growing to . Both constructions start with zero external capital. They are model calculations under the stated frictionless market assumptions.
The beauty of put-call parity is that uncertain individual financial payoffs produce an exact relation between today's prices. No forecast of the terminal stock price and no probability distribution are needed. It provides a consistency check and lets claim replication exchange one contract for a combination of others. Dividends introduce extra cash flows, and American put options can be exercised early, so the displayed European equality cannot simply be transferred to those contracts. K. Foster's [ref]
https://kfoster.ccny.cuny.edu/classes/spring2010/eco275/lecturenotes5.html. CCNY lecture notes on option values (2010), Put-Call Parity section
explain the matching portfolios; Jun Pan's [ref]https://www.mit.edu/~junpan/Jun_Pan_Teaching_Notes.pdf. MIT Financial Markets teaching notes, Arbitrage Pricing and Dynamic Replication section (PDF p. 130)
discuss put-call parity and its dividend adjustment.An original modern research source is Hans R. Stoll's [ref]
https://doi.org/10.1111/j.1540-6261.1969.tb01694.x. The Relationship Between Put and Call Option Prices
, The Journal of Finance 24(5), 801-824 (December 1969). Stoll studied the relation between contract prices and tested it against market data; this was a relation between prices rather than a formula fixing each price individually. Robert C. Merton's [ref]https://doi.org/10.1111/j.1540-6261.1973.tb01357.x. 1973 comment
, 28(1), 183-184, highlighted the importance of excluding premature exercise for an exact arbitrage equality. This distinction explains why the exercise assumption belongs in the statement of put-call parity. Three-four-one inequality for Euler products Created 2026-09-24 Updated 2026-11-05
For every complex number with ,Applying this to each prime-power term in logarithms of Euler products proves thatfor and every completely multiplicative bounded by one.
On shell Created 2026-09-24 Updated 2026-11-05
A classical field configuration is on shell when it satisfies the specified Euler-Lagrange field equations. A relation holding only after those equations are used is an on-shell identity; an off-shell identity holds for arbitrary admissible configurations without imposing the equations.
For a free plane wave of a massive scalar, the field equation gives . This connects the classical equation meaning to the on-shell momentum condition for a free external particle. Internal propagator momenta in a Feynman calculation need not obey that mass-shell relation, even though conservation at vertices remains enforced. Conserved Noether currents are generally conserved on shell, whereas some differential identities follow independently from the equations of motion.
Planar girth edge bound Created 2026-09-24 Updated 2026-09-24
If every face of a connected planar graph has size at least , double-counting edge-face incidences and using Euler's formula gives
There are unlisted articles, also show them or only show them.