
Mixture identifiability 2026-10-14
Simultaneously applying a permutation to the mixture weights and mixture components leaves unchanged. Thus identifiability of named components requires a convention, such as ordering distinct component means; label switching describes the associated inferential issue.[ref]
Even after choosing label names, identical mixture components reveal only their combined mixture weight, and an inactive mixture component has undetermined statistical parameters. Adding mixture components increases flexibility but can cause overfitting; judge predictions using cross-validation, rather than interpreting every fitted component as a discovered population.[ref]
Mixture Models. §21.1.6, printed pp. 445-446: probabilistic clustering and evaluation on future data
Observed and latent mixture labels 2026-10-14
In a finite mixture model with hidden membership, the component label is a latent variable and is observed. If an actual recorded label specifies which mixture component generated , then is observed and its likelihood contribution is . With the label hidden, the observed likelihood contribution is the sum . A hard assignment chosen from mixture responsibilities is an inference under the statistical model, not an additional recorded label.
Two-Gaussian mixture example 2026-10-14
Stipulate an original Gaussian mixture distribution with mixture weights , , component means , , and component variances both equal to one. These are chosen statistical parameters, with no observed sample or fitting. If is the standard normal distribution probability density function, thenIn the figure, the two colored curves are weighted probability density functions, with areas and . Adding their heights at every gives the black curve. Neither colored curve stops at a dividing line.
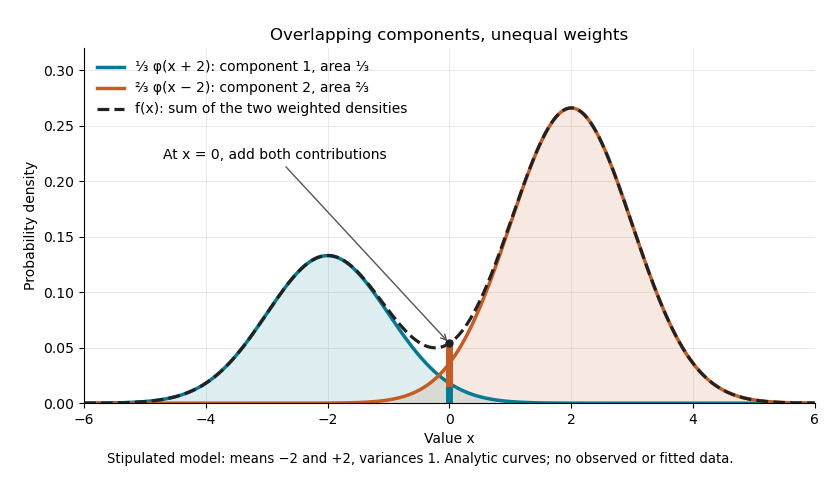

The law of total expectation and law of total variance give the total mean and variance:All of the extra variance comes from variation between component means. Equivalently, the second moment is , so the variance is .
A mixture distribution is different from a deterministic linear combination of random variables. If independent and are drawn and , then has a normal distribution with the same mean but variance , rather than . Every draw of uses both random variables. A draw from the mixture distribution instead uses , where the mixture allocation indicators are independent of and select exactly one of them. The expression for adds densities, not simultaneous random outcomes.
Mixture allocation indicator 2026-10-14
Generate a finite mixture model by drawing a categorical variable with , then drawing from the mixture component . The indicator random variables satisfy : exactly one mixture component generates each draw. The joint probability distribution obeys , and the law of total probability gives the mixture distribution after summing out .[ref]
For independent draws from this statistical model, draw a fresh for each . Drawing one shared latent variable for an entire collection is a different joint probability distribution: its individual marginal distributions can match the same mixture distribution while its observations are dependent.
Mixture component 2026-10-14
A mixture component is the conditional distribution of given a component label . Its probability density function integrates to one; its weighted contribution to the mixture distribution integrates to the mixture weight . Thus a mixture component is a distribution, rather than a region assigned to it by a clustering rule.
Constant nonzero drift is impossible on a finite Markov chain Created 2026-10-14 Updated 2026-11-05
For a real function on a finite state space, a state minimizing satisfies , so strictly negative drift cannot hold at every state. Equivalently, telescoping the expected value would give , contradicting boundedness of . Constant negative drift is useful before a target is reached; it must be restricted to the states outside that target.
Markov chain ergodic theorem Created 2026-10-14 Updated 2026-11-05
For an irreducible finite Markov chain with stationary distribution , the fraction of visits to any state converges almost surely to , for every initial state. More generally, the empirical average of a function of the state converges to its average under . Aperiodicity is needed for convergence of the one-time distributions, but not for this empirical-frequency conclusion. Regeneration at returns to a state proves the conclusion by applying the strong law to independent excursion lengths and excursion rewards.
Regular functor 2026-10-14
A functor between regular categories is regular if it preserves finite limits and regular epimorphisms. It then preserves image factorizations, since finite-limit preservation preserves monomorphisms. A representable functor is regular exactly when is projective with respect to regular epimorphisms. Regularity of a functor does not alone imply faithfulness or reflection of isomorphisms.
Choose a uniform -subset and the graph consisting only of its clique. Acceptance by two approximating set families but rejection by their intersection requires two minimal witnesses whose union has size greater than . At least one has size greater than . The sunflower bound for minimal members of a Razborov-closed family and give .
Independently colour each vertex with one of colours and join differently coloured vertices. This complete multipartite graph has no -clique. If a forced set is rainbow but its witnesses are not, condition on the colours of . The disjoint petals make those failure events conditionally independent. For each witness of size at most , the probability of a colour collision is at most . If this is at most , one closure step causes an error with probability at most . There are at most possible steps; apply the union bound.
Frozen-temperature solutal interface dispersion Created 2026-10-14 Updated 2026-11-05
For an interface perturbation with instantaneous interface kinetics, take the liquid concentration perturbation proportional to . Here is the coefficient of curvature-induced melting-temperature depression. The advection-diffusion equation and interfacial mass conservation giveFor a growing normal mode the unique decaying liquid branch has . Writing , its rate is . Instability requires . The Gibbs-Thomson effect suppresses sufficiently short waves. A quasistatic solute diffusion approximation neglects the perturbation time derivative in the liquid equation and changes this growth rate; prescribing the thermal field alone does not justify that extra approximation.
Tangent-line finite-field Kakeya construction Created 2026-10-14 Updated 2026-11-05
Work in the affine plane over a finite field of odd characteristic. The union of the affine lines , for , contains a line of every finite slope. Completing the square givesFor a fixed , the union therefore contains exactly the values of for which is a square, including zero. Adding the vertical affine line completes all directions. The resulting finite-field Kakeya set has cardinalityIts density tends to one half as grows through odd prime powers. Geometrically the finite-slope lines are the tangents to the parabola , because the tangent at has the displayed equation.
Inside an algebraic closure, choose compatible roots . The fields exhaust all finite extensions by finite extensions of the complex Laurent series field. Restriction from a degree- field to a degree- field for sends an exponent modulo to its reduction modulo . The absolute Galois group is their inverse limit, namely the profinite completion of . This is a procyclic group, rather than the direct-limit torsion group of all complex roots of unity.
Spectral projection of a self-adjoint matrix 2026-10-14
For a finite-dimensional Hermitian matrix , its spectral projection is the orthogonal projection onto the eigenspace for . In an orthonormal eigenbasis, the displayed sum is over every basis vector with that eigenvalue. The projection is independent of the choice of basis within a repeated eigenspace. For distinct eigenvalues ,This is the spectral decomposition grouped by distinct eigenvalues: decompose a vector into orthogonal pieces, then scale each piece. For the matrix ,Thus and : the two pieces add back to . Squaring the matrix simply squares each scalar, , and similarly the matrix exponential is . Spectral projections of a self-adjoint matrix turn repeated matrix calculations into scalar calculations on fixed vector subspaces.
Order of an element of a finite cyclic group Created 2026-10-14 Updated 2026-10-18
For a positive integer and a congruence class in the additive finite cyclic group , the order of a group element isIndeed, write , and . Returning to zero after steps means , equivalently . Since and are coprime, this holds exactly when ; the least positive such is . This argument also covers , since .
For , the orders of are respectively . The translation in a group has the same period from every starting element. Consequently its cycles each have length and there are of them. They are exactly the cosets of the cyclic subgroup generated by , which explains both the lengths and the number of components in the picture.
Hyperoctahedral group Created 2026-10-14 Updated 2026-11-05
The signed symmetric group consists of permutations of commuting with sign change. It is the Coxeter group of type .
Longest element of a Coxeter group 2026-10-14
The longest element is the unique element of maximal Coxeter length in a finite Coxeter group. It is an involution and satisfies .
Cyclic group of order four and Klein four-group Created 2026-10-14 Updated 2026-10-31
The finite cyclic group and the Klein four-group are both abelian groups of order four. In , composition is addition modulo four. In , label the elements and add each coordinate modulo two. For example, and .
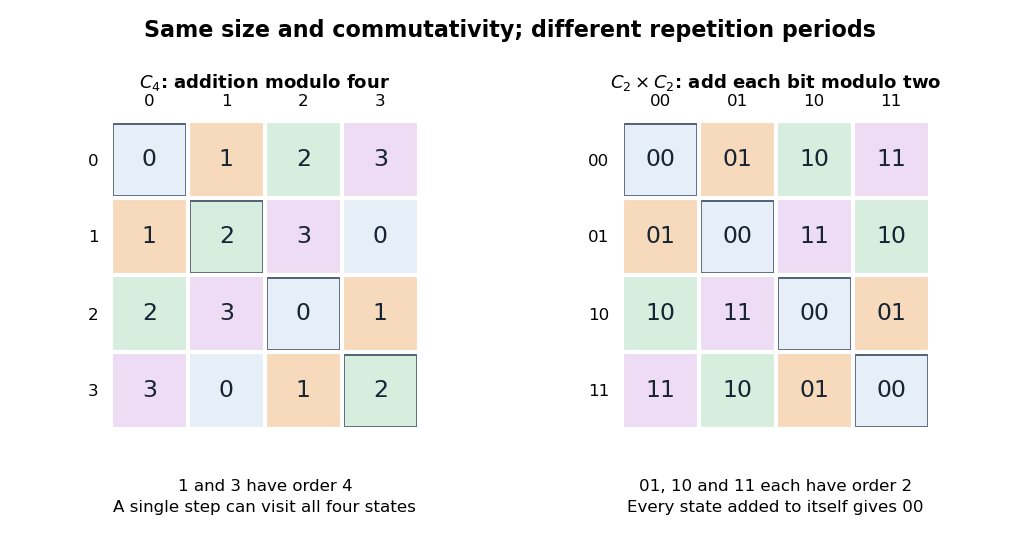
Two abelian groups of order four have different addition tables
. Each cell is the row element plus the column element. Diagonal cells record adding an element to itself. In , only and return to zero after two additions. In the Klein four-group, every diagonal cell is the identity element . The symmetric tables show commutativity, while the different doubling behavior distinguishes the groups. Details.
The order of a group element is preserved by a group isomorphism: an equation holds exactly when its image satisfies the same equation. In , both and have order four. In , each nonidentity element has order two. Hence these groups are not isomorphic, despite having the same order of a finite group. No relabelling can repair this discrepancy.
For a geometric model of , take the symmetries of a non-square rectangle: the identity element, reflection in its horizontal axis, reflection in its vertical axis, and rotation through . The two reflections commute, and their composite is the half-turn. Every nonidentity motion is its own inverse element. This makes the two binary switches concrete: choosing whether to apply each reflection specifies all four motions. The case of abelian groups of prime-square order generalizes this distinction from to any prime .
Normal ultrafilter on small subsets 2026-10-14
An ultrafilter on is normal when each function with on a -large set is constant on a -large subset. This is the small-subset version of normality; together with fineness and kappa-completeness it gives the measure characterization of a supercompact cardinal.
Connected-component presheaf of a functor 2026-10-14
For a functor , precomposition by induces , hence a map of categorical connected components in the opposite direction to . This defines a presheaf on . Its category of elements is the intermediate category in the final-discrete-fibration factorization.
There are unlisted articles, also show them or only show them.