All questions and optional branches are covered, including the inline Roman parts of question 8. Real and complex solution domains and the limitations of an integrating-factor reduction are stated explicitly.
The complex exponential identity givesThus the locus is a circle of radius centered at , traversed counterclockwise twice as runs through the specified interval. Its period as a parametrized curve is . Near , the Taylor expansion gives and , so locally . There is a smooth horizontal tangent, not a cusp: is nonzero at each passage through the origin.
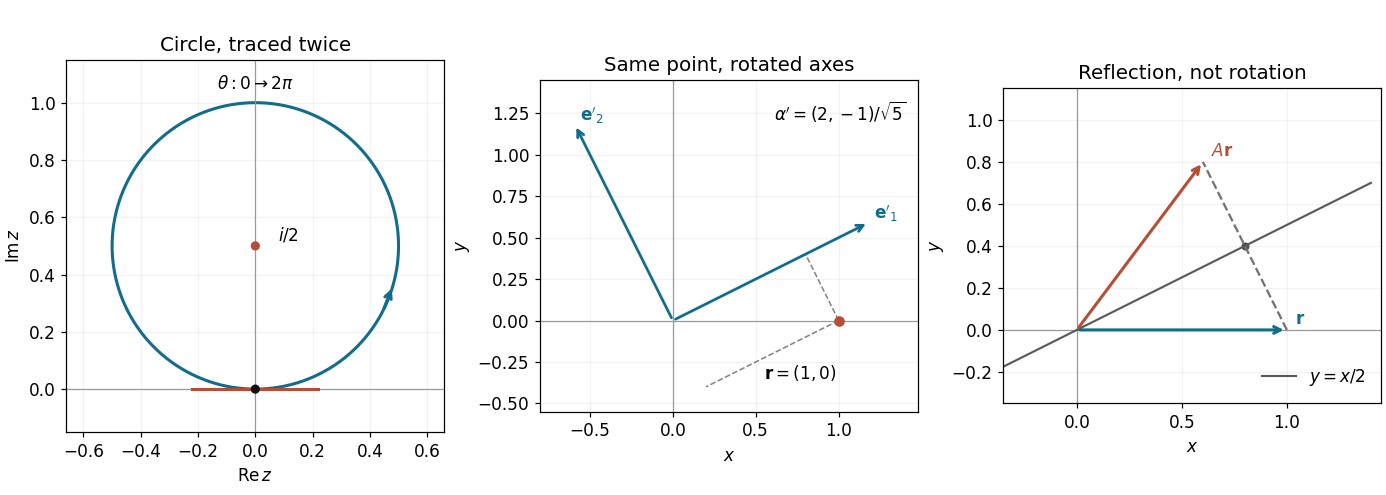
A twice-traversed complex circle, a passive rotation of coordinate axes, and reflection in the line y=x/2
. Details. Using the hyperbolic functions identities and , divide by and put . The equation becomes , henceTaking all branches of the complex logarithm givesIf is required to be real, there are no real solutions, since cannot be negative. The complex branches are essential to the unrestricted answer.
In the matrix product, . A nonzero summand in a product of upper triangular matrices requires both and . If , no such index exists, so the product is upper triangular. If , only survives, givingThis also shows inductively why the diagonal of an integer matrix power consists of the corresponding powers of the diagonal entries.
For the upper triangular matrix , direct matrix multiplication givesThe real diagonal entries are therefore . Their off-diagonal multiplier is , so . A required matrix isIt is the unique real upper triangular cube root. Allowing complex diagonal cube roots produces other complex matrices; uniqueness is asserted only over the real numbers.
Subtracting twice the first equation from the second gives . The third equation gives , and substitution in the first then gives . Consequently . The complete real solution set of this linear system isThere is no parameter value allowing both and . In either exceptional family, forces ; in the remaining case, . The exceptional values must be handled before dividing by their factors.
The displayed orthogonal matrix transforms the coordinates of a fixed vector, rather than actively moving that vector. Write . Then , so the new unit basis vectors, expressed in the old orthonormal basis, are the columns of :The axes have rotated counterclockwise through , while the coordinate column transforms by the opposite rotation. For the example point , its new coordinates are . Reconstruction gives , confirming that the point is unchanged. The middle panel of the figure in part 1 shows these axes and the signed projections. Since and , lengths and orientation of the basis are preserved.
Let be a unit vector along the fixed line. The orthogonal projection parallel to the line is ; a reflection keeps that component and reverses its orthogonal complement. ThereforeIts eigenvalues are along and along . It preserves lengths and unsigned areas but reverses orientation. For example, maps to , with their midpoint on the reflection line and their separation perpendicular to it; the right panel of the figure in 1 illustrates this.
Use the Characteristic polynomials of AB and BA, which also account for the zero eigenvalue and algebraic multiplicities. The block determinantequals both and , by taking the two Schur complements. For , set and multiply by to obtainBoth sides are polynomials, so agreement away from zero proves equality there as well. Their roots, with multiplicity, are the same. The familiar eigenvector argument works directly only when , because then ; it should not be used to discard the zero case.
The two affine lines meet at . Translating their intersection to the origin, , , removes both constant terms and gives the homogeneous first-order differential equationOn a patch with , put . Then , and separation of variables givesThus one local real implicit form isThe arctangent branch must be continued on the chosen solution patch. More geometrically, set and take a continuous local argument ; then . This form extends through where the original slope is defined. The intersection itself is excluded because the original right-hand side is there, and points with do not define a finite derivative. No real constant- solution was lost, because has no real zero. Translating the intersection works precisely because the two affine linear forms then become homogeneous linear forms.
The linear span is , a vector subspace of . Its dimension is zero if both vectors vanish, one if at least one is nonzero and they are linearly dependent, and two if they are linearly independent. The corresponding geometric sets are the origin, a line through the origin, and a plane through the origin.
Contract the Levi-Civita symbol identity . Using Einstein summation convention,This Lagrange identity for the cross product includes zero and parallel vectors without a separate division by their norms.
The set is the kernel of the linear map . It contains zero, and linearity gives whenever , proving closure under linear combinations. If , it is a plane through the origin; if , it is all of . An arbitrary plane need not be a vector subspace: for example omits the zero vector. An affine subspace and a vector subspace are not interchangeable.
The dimension formula for a sum of subspaces givesSince the sum lies in and each plane has dimension two, the possibilities areThe first case means the planes coincide; two distinct planes through the origin intersect in a line.
Taking cross products of the two independent spanning vectors gives plane normal vectors proportional to and . Their cross product is , so the intersection is the line , with . The closest point to is its orthogonal projection,The squared distance is , givingBoth plane normals are orthogonal to , and , checking the geometric constraints.
The matrix exponential power series is absolutely convergent for a finite matrix, so taking the conjugate transpose term by term is valid. Since ,The absolute convergence also justifies the Cauchy product. In , the coefficient of is proportional to , which is zero for and one for , by the binomial theorem. Consequently ; the reversed product is also . This proves that the exponential is unitary directly from the power series, without invoking diagonalization.
First check that the proposed space is closed under the stated operations: , and summing gives a finite result. For any finite , the Cauchy-Schwarz inequality givesThe left side is an increasing, bounded sequence of real numbers. Its limit exists, proving absolute convergence of . This justifies termwise addition and scalar multiplication in the defining sum. Symmetry and bilinearity follow, while , with equality only when every . Thus it is a real inner product on the real l2 sequence space.
The state update matrix isIts eigenvalues are and , with eigenvectors and . The initial column decomposes as . Applying and reading the second component givesThe alternating term decays because its eigenvalue has modulus below one. The convergence of an adjacent-term averaging recurrence gives the same result by a first-order recurrence for successive differences.
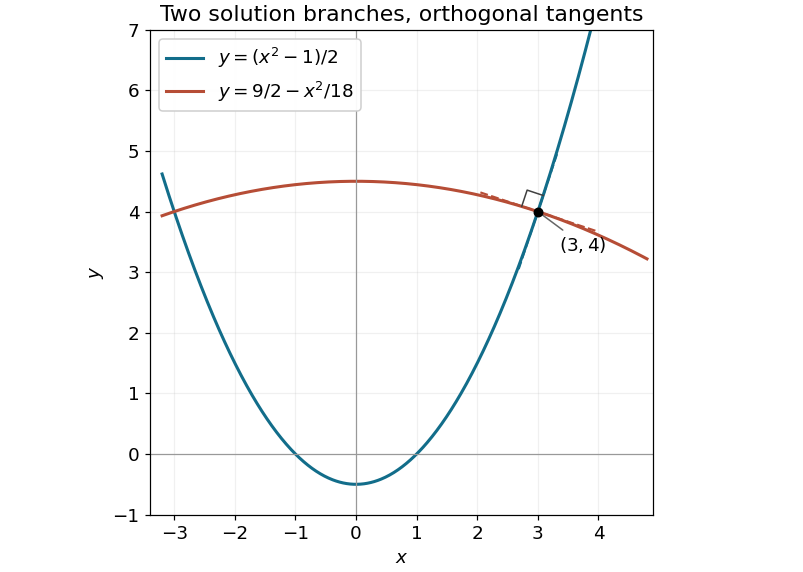
Work over the reals with , and put . The algebraic equation implies andDifferentiate this identity and use ; cancellation gives . Hence , with nonzero real , and substitution gives the complete familyThere is no extra real singular branch lost in the cancellation, since . At a point with , the permitted constants satisfy , givingThese are distinct, real and nonzero, so exactly two integral curves pass through each such point. This does not contradict an Picard-Lindelöf theorem: the implicit equation permits two different slopes and is not one specified explicit first-order ordinary differential equation. Each choice of the smooth slope branch separately defines a locally unique curve.
The two real slope roots of are distinct because their discriminant is . Vieta's formulas give , so the tangent vectors and have zero scalar product. Whenever the coefficients define local solution curves, the two families are therefore orthogonal trajectories.
For the stated example at , the slopes are and . In the family from part a, the constants are and , givingBoth curves pass through , and verifies the right angle.


An integrating factor directly solves a linear first-order equation; a general second-order equation needs an additional reduction. There are several sufficient cases, with all divisions restricted to intervals where their denominators are nonzero.
If and , divide by to obtain . The integrating factor is andIf and , put . Then is first order, with integrating factor ; solve for and integrate once more for .
A further reducible class has , for thenOne integration produces a first-order equation for , whose integrating factor after division by is .
Multiplication can always put a regular second-order equation into self-adjoint form by choosing , sinceHowever, the remaining term generally prevents one integration from solving it. The limitations of integrating factors for second-order equations explain why this formal transformation alone is not a general solution method. These sufficient classes do not purport to classify every specially solvable coefficient choice.
Differentiate the constraint to obtain and eliminate from the other equations. Adding the resulting equations gives , and substitution then gives . Its integrating factor is , so ; the initial value fixes .
The remaining equation is . Its integrating factor is , giving ; the initial value fixes . Finally use the constraint:The acceleration is , which is not constant. Thus a constant net force cannot maintain this motion for a particle of constant mass, by Newton's second law. This conclusion concerns the net force in the stated inertial-coordinate interpretation; a time-dependent force can produce it.
Articles by others on the same topic
There are currently no matching articles.