For , the positive constant- surfaces in elliptic cylindrical coordinates satisfyThey are confocal elliptic cylinders with focal lines . For a generic fixed , eliminating givesBecause , a fixed selects the half-branch with the signs of and fixed by and . These are hyperbolic cylinders. The degenerate surface is , , extended in . At the cross-sections are the two exterior horizontal rays; at they are vertical half-axes.
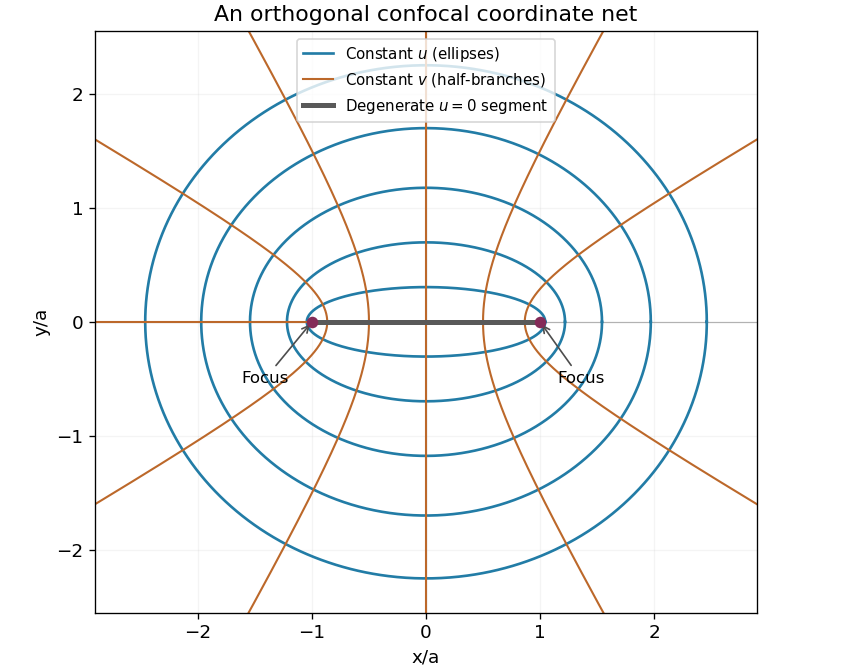

Differentiate the position vector to get the coordinate tangent vectorsTheir pairwise dot products vanish. Their squared lengths are , and one. This proves orthogonality and gives the scale factors of orthogonal coordinates:The Riemannian metric is . Away from the focal lines, divide the coordinate tangent vectors by their lengths to obtain the local orthonormal unit vectors . For physical vector field components , the formulas for vector calculus in elliptic cylindrical coordinates areThe gradient of a scalar function has components . Apply the divergence formula to this gradient; Laplace's equation becomesThe formulas apply where ; the focal lines require a limit or another coordinate chart.
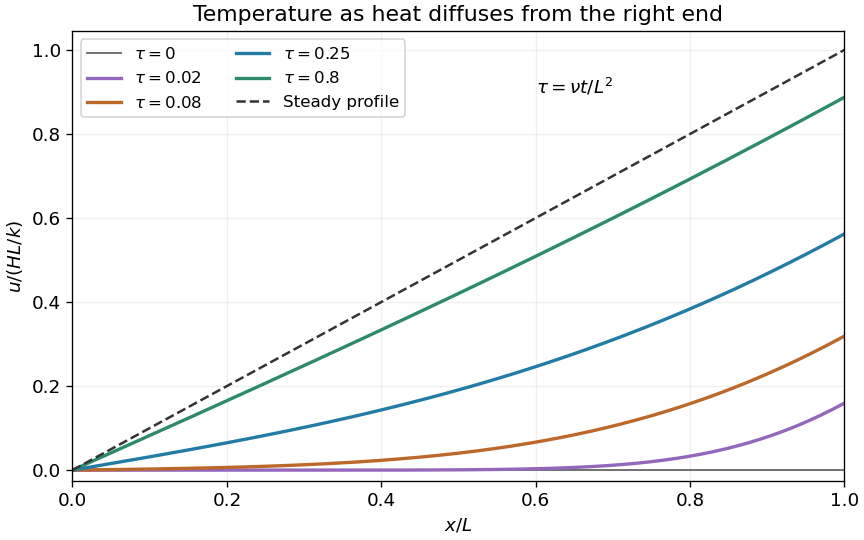
With temperature measured relative to the fixed-temperature end, the heat equation and its data areHere is thermal diffusivity and is thermal conductivity. The sign of the derivative condition describes incoming heat flux at : the outward conductive heat flux is .
Choose the stationary solution satisfying and . Hence . Subtracting it gives the homogeneous problemThis boundary lifting leaves a Dirichlet boundary condition at one end and a Neumann boundary condition at the other, as in the fixed-temperature and fixed-flux heat equation on an interval.
For a nonzero separated solution , separation of variables gives and . The endpoint conditions require and . Thus the mixed Dirichlet-Neumann modes on an interval have , . Their squared L2 norms are , so the initial Fourier coefficients areThe integration uses and . ThereforeAt positive time the series can be differentiated termwise and satisfies both homogeneous endpoint conditions for . At time zero it recovers , so recovers the initial zero temperature. If , the prescribed derivative at is incompatible with differentiating the initial zero profile; the temperature is still continuous there, while its spatial derivative has a corner layer. At long times the decaying modes leave .
Heating a bar through one end while the other end stays at zero temperature
. Original dimensionless temperature profiles at several diffusion times. The eventual linear profile has the imposed unit derivative at the heated end. Details.
Use the Fourier transform convention , with inverse factor . For functions in L1 space, their convolution is . Fubini's theorem applies because the absolute double integral is . Substituting therefore proves the convolution theorem:For the specified rectangular pulse, the support condition is . Its Fourier transform isThe convolution is the length of the overlap of and . Thus it is the triangular pulseThe transform's value at zero is four, given by its continuous extension. In this convention, the Parseval identity for square-integrable functions isFor the rectangular pulse the left side is two, giving the sinc-squared integralFor the triangular pulse, . Apply the same Parseval identity with transform to obtain the sinc fourth-power integralBoth integrands have removable singularities at zero and integrable tails.
The spectral theorem gives a real orthonormal eigenbasis for a real symmetric matrix . Distinct eigenspaces are orthogonal; within a repeated eigenspace, choose an orthonormal basis, for example by Gram-Schmidt orthogonalization. Put these eigenvectors in the columns of . Then andFor a change of variables , choose . Since , the quadratic form becomes ; the are precisely the eigenvalues of .
In the numerical case, the off-diagonal entries are half the cross-term coefficients, soA direct eigenvector calculation gives the unit eigenvectors , , , with eigenvalues two, three and minus six. They are pairwise orthogonal. Therefore the required orthogonal diagonalization isand the transformed quadratic form is .
If for a Hermitian matrix and a nonzero eigenvector, then . The scalar on the left equals its complex conjugate because , while . Thus is real. If also , thenConsequently distinct eigenvalues force , proving orthogonality of their eigenvectors.
For a unitary matrix, preserves the norm induced by the standard Hermitian inner product. If with , then , so .
Since and are real symmetric matrices, . Expanding the unitarity condition givesEquality of the entrywise real and imaginary parts yieldsThese are the identities for the real and imaginary parts of a symmetric unitary matrix.
Let . The commutation relation gives , so preserves the eigenspace of with eigenvalue . Because it is a nondegenerate eigenvalue, the eigenspace is one-dimensional, and for some real . This includes . Thus the eigenvectors of form a common eigenbasis, andWriting the corresponding unit-modulus eigenvalue of as givesThe pairing refers to the same common eigenvector; independent reorderings of the two real spectra would lose this information. The simultaneous diagonalization can also be constructed without requiring simple eigenvalues by diagonalizing within each eigenspace of .
For the normalized second-order linear differential equation , an ordinary point has analytic near . At a regular singular point, which is not ordinary, and are analytic. Ordinary points admit two independent convergent power series solutions. Regular singular points instead call for the Frobenius method, which permits leading powers and, in some cases, logarithms.
Here zero is an ordinary point. Substitute into the Hermite differential equation and equate coefficients:The even and odd initial coefficients are independent, givingThese are the power series solutions of the Hermite differential equation, with the present parameter equal to twice the parameter in that article. The ratio of successive terms within each nonterminating parity is asymptotically , so both series have infinite radius of convergence.
For a nonzero polynomial of degree , its highest coefficient in forces . Conversely at that value the matching parity terminates. HenceThe polynomial solutions are scalar multiples of the Hermite polynomials. Two examples are ; direct substitution verifies both. The other independent solution generally remains nonpolynomial.
Multiplication by puts the eigenvalue problem into Sturm-Liouville form, , with weight . If correspond to distinct eigenvalues , subtract their multiplied equations and integrate to getThe upper boundary term vanishes by the Dirichlet boundary condition. For a bounded solution near zero, has a limit because is integrable. A nonzero limit would force a divergence in , so that limit is zero; integration then gives . The lower boundary term therefore also vanishes, proving the weighted orthogonality.
Set . For , , and finiteness of gives . Thus with zero values at zero and . The radial Dirichlet spectrum in three dimensions givesThe zero and negative eigenvalues yield only the zero solution under these boundary conditions. Also .
For the forced equation, the same substitution gives . The Fourier sine series of on has coefficientsExpanding gives , henceThe value at zero is defined by a limit. In fact , so uniform convergence holds even there, by comparison with . An independent check comes from solving the constant-coefficient equation directly:It satisfies both endpoint conditions and the forcing for , and its finite origin limit agrees with the series. For the homogeneous boundary value problem has no nonzero solution, so the solution is unique.
Substitution of into the homogeneous Euler-Cauchy equation gives , so . Use the solution that vanishes at zero and that decays at infinity. Their Wronskian is . The half-line Green function for the first cylindrical harmonic is thereforeIt is continuous at , its first derivative has jump , and it solves the homogeneous equation elsewhere. Thus for integration with ordinary measure . The boundary conditions hold for each fixed .
Integrating against the forcing givesSince the two integrals are and , respectively,A Taylor expansion gives near zero, while at infinity. This verifies the two endpoint limits; direct differentiation verifies on . The differential expression itself is singular at zero, so the endpoint condition is imposed by continuity. No nonzero combination of and satisfies both homogeneous endpoint conditions, proving uniqueness.
Vary by with . The first variation of the functional isThe boundary term from integration by parts is zero. The fundamental lemma of the calculus of variations therefore gives . For , independently vary and with zero endpoint variations; the two Euler-Lagrange equations areFor the optical path, Fermat principle makes stationary. In cylindrical coordinates its integrand is , with . There is no explicit dependence. The Beltrami identity for several dependent variables givesThe conserved quantity is the axial component of the optical momentum of a ray. As , squaring and inverting yieldsNow suppose and seek a path of radius . The angle is a cyclic coordinate, so is conserved. At fixed radius this is strictly increasing in , forcing constant. The radial Euler-Lagrange equation reduces toConsequently the helical rays in a radially graded refractive index haveA real nonzero helix exists at such a radius when , and its helical pitch is . If , the solution is instead a straight axial light ray. Thus radial dependence permits constant-radius rays for suitable profiles; an arbitrary radial profile need not support a nonzero real helix. This qualification is necessary, for example when the refractive index increases with radius.
Choose homogeneous Dirichlet boundary conditions, , and nonzero admissible functions with finite and positive . Variations obey the same zero endpoint values. At a stationary Rayleigh quotient, set . ThenThe boundary term vanishes, and the fundamental lemma of the calculus of variations gives the Sturm-Liouville equation . Thus stationary functions are eigenfunctions. Conversely, multiply that equation by and integrate by parts to obtain ; its first variation then vanishes by the same calculation. This proves that stationary values are the corresponding eigenvalues. Homogeneous Neumann boundary conditions also make the displayed boundary terms vanish; general Robin boundary conditions can require a boundary contribution to the quadratic form.
For , , on , the polynomial trial function satisfies the endpoint conditions. Its Rayleigh quotient usesso the polynomial estimate is . The trigonometric trial function givesand hence . Both are upper bounds on the lowest eigenvalue, by the Rayleigh-Ritz method; neither trial is an exact eigenfunction, so the inequalities are strict.
Their closeness has a useful explanation beyond their similar single-arch shapes. Both trial functions are symmetric under , forcing . The reflection-symmetric trials for a linearly weighted Rayleigh quotient therefore reduce this problem to a constant multiple of the ordinary Dirichlet energy quotient. The sine is the best trial within this symmetric class, and the polynomial's value is only a factor larger. The unrestricted lowest eigenfunction can be asymmetric because the weight is asymmetric.
Articles by others on the same topic
There are currently no matching articles.