Let . Since the kernel of a linear map and its image agree, the rank-nullity theorem gives . Thus is even. Every lies in , so . The minimal polynomial therefore divides . It cannot be , and it cannot be since ; hence the minimal polynomial is .
Choose and write using the direct sum of vector spaces . Neither component is zero: otherwise would lie in one of the zero intersections or . They are linearly independent, so is a two-dimensional vector subspace. Uniqueness of the direct-sum decomposition gives and . Also , but cannot be contained in because . Hence is one-dimensional. This constructs the required common plane for three pairwise complementary subspaces.
An ideal hyperbolic triangle has its three vertices at infinity, with sides given by geodesics. In curvature its angles are zero and its area is , using the hyperbolic triangle area formula .
To calculate the area of a hyperbolic disc, use the Poincare disc model centered at the origin. Hyperbolic radial distance is , so its Euclidean radius is . The metric area density is , givingEvery hyperbolic triangle, including ones with ideal vertices, has area at most . But . A hyperbolic triangle is geodesically convex, so if it contains a complete hyperbolic circle, it also contains the enclosed hyperbolic disc, its geodesic convex hull. This would violate the area comparison. Therefore no hyperbolic triangle contains a complete circle of radius two.
For a holomorphic function, compute its complex derivative along the real and imaginary directions. The real direction gives , while division by an imaginary increment gives . Equating real and imaginary parts proves the Cauchy-Riemann equations:For the specified real part, and . Integrating gives ; the other relation in the Cauchy-Riemann equations then forces . Thus the harmonic conjugate and the holomorphic function are
Use and metric signature . Since , the four-velocity and four-momentum areThese use the proper time and Lorentz factor; the mass shell identity is .
Initially the parent four-momentum is . By four-momentum conservation, the remaining single particle has energy and three-momentum . Applying its mass shell identity gives , henceThe positive root is selected for the rest mass; physically admissible decay data also give nonnegative remaining energy.
The divergence of this axisymmetric velocity field is . Thus it satisfies incompressibility. The apparent axis singularity in the azimuthal component is removable, since as .
Only the axial vorticity component is nonzero:The cross product is . Its components are independent of and , so its curl also has only an axial component:Meanwhile and , givingThus the required steady vorticity equation holds with . This is the balance between vortex stretching and viscous diffusion in a Burgers vortex.
Subtract the exact solution from the Jacobi method to get , hence . Convergence from every initial vector is equivalent to . If every eigenvalue has modulus below one, a Jordan block has powers that are finite sums . The polynomial factor in is dominated by geometric decay; for , the block is nilpotent. Consequently .
Conversely, for a complex eigenvector with eigenvalue , . Convergence for real errors also implies convergence for their complexification, so this tends to zero only if . Therefore the iteration converges from every starting vector if and only if , where is the spectral radius.
For the specified matrix,Its eigenvalues are , so . Hence is the convergence range. The original coefficient matrix has determinant , so the endpoints also violate its assumed nonsingularity.
An unbiased estimator satisfies for every parameter value. Under the standard full-column-rank assumption on the design matrix, the Gaussian log-likelihood for the normal linear model, up to terms independent of , is . Its maximum is the ordinary least squares minimum. Differentiating gives , and full column rank makes positive definite. ThusSince , its expectation is , proving unbiasedness. Estimating an unknown as well does not change the maximizing coefficient vector.
The printed hypotheses give but do not explicitly require full column rank. Without that condition the maximum-likelihood estimators are not unique: they are with , as in rank-deficient ordinary least squares. If , the observation distributions at and are identical. Every estimator then has the same expectation at both parameters, so no estimator can be unbiased for both entire coefficient vectors. This proves nonidentifiability prevents unbiased coefficient estimation. The stated estimator and unbiasedness claim require the usual full-rank condition.
The point is nonnegative and makes all three inequalities equalities, with objective value . To certify global optimality, combine the first upper bound with coefficient , the second with coefficient one, and the lower bound with coefficient :This is a weak duality certificate for the linear program. The feasible point attains the bound, so the optimal solution is and the maximum is . Equality forces each of the three constraints to be active; their simultaneous equations have this unique solution.
The dual space is , the vector space of all linear functionals with pointwise operations. For finite , choose a basis and define its dual basis by . Every linear functional is , and evaluation on each proves that the are linearly independent. Thus . This dimension formula is a finite-dimensional assertion.
On the space of polynomials of degree at most , define the evaluation map . Its kernel is zero: a nonzero degree-at-most- polynomial cannot have distinct roots. Since domain and codomain both have dimension , is an isomorphism. The evaluations therefore form a basis of the dual space. The linear functional has a unique expansion in that basis, proving the existence and uniqueness of the requested weights.
Explicitly, use the Lagrange interpolation polynomial basisThe differentiation weights from nodal evaluations are . If a node is zero, no singular reciprocal formula is needed: differentiate the finite product directly. For the sole weight is zero.
In a principal ideal domain, an ascending chain of ideals stabilizes: its union is an ideal , and its generator belongs to one member, which then contains the union. This proves the needed ascending chain condition. If a nonzero nonunit had no finite irreducible factorization, split it into two nonunits and select a factor that still has no such factorization. Continuing would give a strictly ascending chain of principal ideals, because with a nonunit implies . This contradicts the chain condition, so factorization exists.
An irreducible element generates a maximal ideal: any intermediate ideal is with , and irreducibility forces or to be a unit. Therefore is a prime element. In any two irreducible factorizations, the first prime factor divides a factor of the other, hence is associate to it. Cancel and continue. This proves every principal ideal domain is a unique factorization domain.
In , the multiplicative field norm is . The only units are . There is no element of norm two, so every element of norm four is irreducible: a factorization into nonunits would require norms two and two. Consequentlyis a pair of genuinely different irreducible factorizations. Neither nor is associate to .
Take the Eisenstein integers , where and . Since , the embedded subring is , whose additive index in is two. Its larger ring has Eisenstein-integer norm and is Euclidean. Indeed, write a complex quotient in the real basis and round both coordinates to integers. The coordinate errors satisfy , giving . Thus division leaves a remainder of smaller norm. A Euclidean domain is a principal ideal domain, because division by a nonzero element of least norm in an ideal leaves zero remainder. This gives the requested index-two embedding into a principal ideal domain.
Let . It is continuous and takes values in . The finite sums are continuous and their tails obeyfor every real . To prove continuity without invoking an unproved uniform-limit theorem, fix and . Choose with , then use continuity of to make near . The triangle inequality then gives . Thus is continuous; it is the scaled Takagi function .
For the general secant claim, differentiability gives , where for sufficiently small , with . Since the two endpoints straddle ,Hence the secant limit is , including cases where an endpoint equals . This proves secants straddling a differentiability point.
Now take the nested dyadic intervals , . They straddle and shrink to it. For every , and are integers, so the corresponding summand vanishes at both endpoints. For , all corners of that summand lie on the dyadic grid of mesh ; on the chosen open interval it is linear with slope . Therefore its total secant slope isRefining to the nested interval preserves the slopes of all old terms and adds exactly one new term of slope or . Thus for every , so cannot converge. This contradicts the secant consequence of differentiability at any . Therefore is nowhere differentiable. At dyadic the intervals chosen on its right satisfy the same argument. The printed reference to a denominator is naturally read as mesh , or denominator , as used here.
Suppose converges to . Continuity gives , and uniqueness of limits in a metric space gives . Hence every convergent sequence in the graph has its limit in the graph, proving is closed.
If were not continuous at , there would be and with . A compact metric space is sequentially compact, so some subsequence converges to . The closed graph then contains its product limit , forcing , contrary to the lower bound. Thus is continuous, the compact-codomain form of the closed graph theorem for compact spaces.
Take and for . Its graph is , a union of two closed sets, since multiplication is continuous. But does not tend to , so the function is not continuous.
Choose the principal branch of a multivalued function, , for . The integrand has simple poles at and a branch cut along the negative real axis. Its residues arewhose sum is .
For , close the Bromwich contour to the left using a rectangle with outer real part and horizontal edges at imaginary parts , indenting the cut and zero. On every distant edge, , and . Each edge has length and , so its integral is . The small circle of radius about zero contributes . The tails of the original vertical integral are absolutely bounded by as well.
On the upper and lower banks at , the square roots are and , respectively. With the upper bank traversed toward zero and the lower bank away from zero, their combined integral isThe cut integral converges near zero since is integrable, and at infinity by exponential decay. The residue theorem, followed by and , therefore givesFor , close the Bromwich contour to the right. There are no enclosed poles or cuts, and there. The same distant-edge estimates show for .
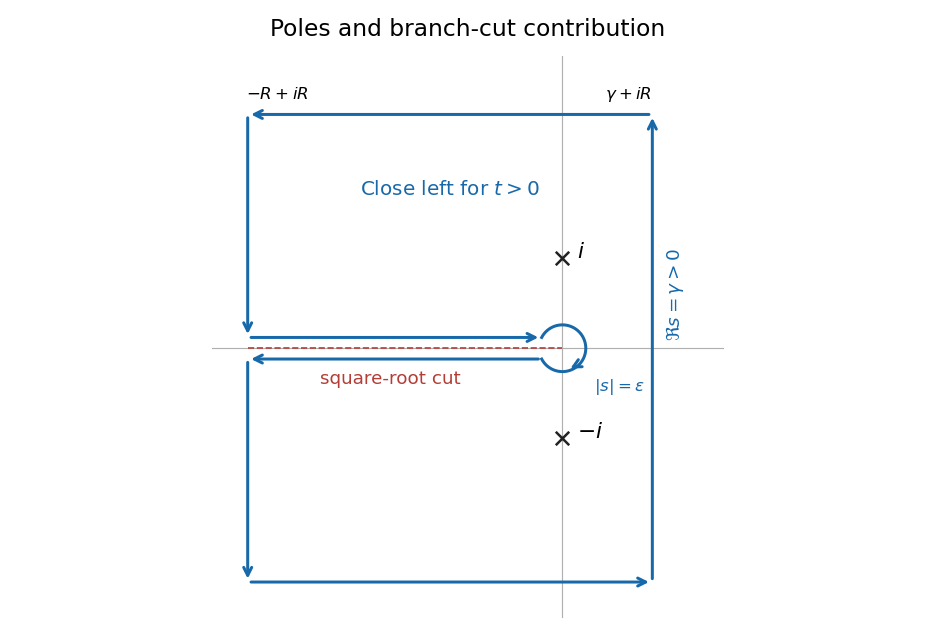
Left-closing Bromwich contour with the principal square-root cut, two pole residues, and a small indentation at zero
. Details. 
For the large- expansion, . Scaling and using the given integral yields . Integration by parts twice gives the next coefficient . The remainder is bounded by . Thus, without needing a globally convergent termwise integration of the local power series,In particular, the requested two leading terms are , interpreted as an additive asymptotic expansion. This is Bromwich inversion with a square-root branch cut.
Write with . Substitution into the ordinary differential equation givesUnless the series terminates, its coefficient ratio is , so it converges for every finite . A coefficient first vanishes exactly when is a nonnegative integer , and then , . Thus is a polynomial precisely for , in which caseis the normalized Laguerre polynomial.
Multiplying the differential equation by gives . Multiply by , subtract the equation with the indices exchanged, and integrate over . The boundary term vanishes both at zero and infinity. ThereforeThis is the weighted orthogonality of the Laguerre polynomials.
Their leading coefficients show . Since have distinct degrees, they form a basis of that polynomial space. Hence , and comparison of leading coefficients gives . Likewise the degrees of and for run through and , respectively. A nontrivial linear combination cannot cancel its highest-degree term, so these functions are linearly independent.
For , this gives the basis of the cubic polynomial space, establishing the specified expansion. Its weighted integral is : integrates to one, and are orthogonal to , and integrates to zero. At the two roots of , the expansion reduces to . Solving these two equations for givesFor explicit verification, the recurrence gives , . Thus , are distinct positive roots and , . This is the two-node Gauss-Laguerre quadrature rule, exact for every cubic.
The parity operator acts by . For an even potential, differentiating twice and using proves on the parity-invariant domain of the Hamiltonian operator. Therefore each energy eigenspace is invariant under . The projectors and split it into even and odd subspaces, giving a basis of simultaneous eigenstates. An odd state obeys , hence .
The infinite walls impose , with the wavefunction zero outside. It is continuous at the central delta potential. Integrate the stationary Schrödinger equation over ; the energy integral tends to zero and the Dirac delta function contributes . This givesFor the given piecewise positive-energy form, . Replacing by swaps the two pieces and leaves their values unchanged, proving . The value at zero is , and the one-sided derivatives are and . The jump condition gives . The wall at gives , henceFor the undivided wall equation instead gives the usual free even roots. For , set and . In every interval there is exactly one root: writing gives , whose two sides are respectively strictly decreasing and increasing. These are all positive even roots; the quadratic form is nonnegative, so there are no negative eigenvalues. Thus and .
The printed limit of this absolute energy difference is false. The exact quantization equation gives , so but . ConsequentlyThus the high-energy shift from a central delta barrier is a finite positive constant, not zero. The corrected vanishing statement is the relative shift , or the wave-number difference . Physically, highly energetic particles are weakly affected in relative terms by a fixed point barrier. The free even wavefunction normalized in has density at the origin, so the barrier's first-order expectation is , matching the exact limit.
Odd states vanish at zero, so the delta term and the derivative jump both vanish. Their normalized wavefunctions and energies arewith zero wavefunction outside. They do not depend on . These even and odd sectors describe the central delta barrier in a symmetric infinite well.
In electrostatic equilibrium, the electric field inside a perfect conductor is zero. Apply the Faraday's law to a thin rectangular loop crossing the surface, with its long sides tangential and its short sides shrinking to zero. It yields continuity of the tangential electric field. Since its interior value is zero, . Earthing fixes the electric potential at the plane to zero. For completeness, a thin Gauss law pillbox gives ; the normal component can be nonzero because of induced surface charge. These are the electrostatic boundary conditions at a conductor.
The charge and its proposed image charge give the exterior electric potentialAt the terms cancel, so everywhere on the plane and its tangential derivatives vanish. Thus the image construction satisfies the earthed-conductor boundary conditions. It has the correct point-charge singularity, is harmonic elsewhere in , and decays at infinity; electrostatic uniqueness identifies it with the exterior solution.
At instantaneous height , the image charge is a distance below the real charge, giving force with . Multiplying by and using rest at givesThe induced-conductor potential energy is , not the full energy of a pair of independently movable charges. On the falling branch, integrate the reciprocal speed:The last integral is by . Hence the fall time of a charge toward a grounded plane in the electrostatic Newtonian model isFor there is no force and the particle remains at rest.
Use the steady inviscid, hydrostatic, slowly varying channel approximation, without a hydraulic jump. Conservation of volume flux per unit width gives . The free-surface Bernoulli equation isDividing by yieldsThe parameter here is the squared upstream Froude number. For nonzero discharge, regarding as a function of , its derivative is . It has its unique maximum at , where the local Froude number is one. Substitution gives . This maximum is the hydraulic control over a smooth hump.
The upstream flow is subcritical flow, with . On this branch , so the depth decreases as the bed rises; the velocity increases. Since the crest height is below , the depth remains above and never becomes critical. Over the falling side of the hump the depth increases again to downstream. The free surface falls over the hump: on the subcritical branch.
The upstream flow is supercritical flow, with . Now , so the depth increases over the rising hump and the velocity decreases, while the free surface rises. Since , the depth stays below . On the descending bed it decreases back to downstream, remaining supercritical throughout.
At the crest the two depth branches meet at . For a smooth nondegenerate maximum of the bed, is proportional to , while expansion of the depth relation gives . A differentiable flow through the crest therefore switches branches rather than following the cusp obtained by staying on the same branch. Subcritical upstream flow becomes supercritical downstream; supercritical upstream flow becomes subcritical downstream.
When and the bed returns to zero, put . The head equation becomes , orThe root is the original subcritical branch. The other positive root is smaller and lies on the supercritical branch, givingThis is the smooth transcritical, shock-free solution. A downstream hydraulic jump would require further downstream conditions and energy loss. A degenerate flat crest can also require a branch-selection condition; the standard critical-control interpretation uses a nondegenerate smooth crest. For , , so a positive hump is incompatible with the prescribed upstream critical head. If , the head equation is the still-water relation ; a crest of height dries out, so the wet transcritical-flow interpretation requires .
A critical region is the set of sample outcomes on which a test rejects its null hypothesis. Its power function is ; its size of a statistical test is . Randomized tests replace the indicator of by a rejection probability .
The Neyman-Pearson lemma states that for two simple hypotheses with densities , the test that is one where , zero where , and randomized on equality to have null rejection probability , maximizes power among tests of size at most . Here . To prove it, let be any competing test. Pointwise, , since both factors have the same sign off the equality set. Integrating givesThis proves the lemma, including equality-set randomization and points where .
Take the exponential parameter to be its rate: for . For , the joint likelihood ratio is , decreasing in . Hence for the most powerful test isThere is no boundary randomization because has a continuous gamma distribution. Its density follows by repeated convolution: . Integrating by parts gives the exponential-rate likelihood-ratio test powerThe threshold is the unique positive solution of this formula at with value . Differentiating the finite sum yieldsThus the power function is strictly increasing, and its supremum over is . Therefore the same test has size for the composite null . Since the threshold does not depend on the particular larger rate, it is also uniformly most powerful against all . The endpoint sizes zero and one have their trivial constant tests.
Read the maze as two four-cycles: outer vertices , inner vertices for modulo four, edges , , and , together with edges from every to the target . The starting vertex is an outer vertex. Outer degrees are three and inner degrees are four.
For the ordinary random walk on a graph, symmetry gives a common expected hitting time from an outer vertex and from an inner one. First-step conditioning givesThus and , yielding and the requested starting mean moves.
For the non-backtracking random walk, the current vertex alone does not form a Markov chain. Use states recording previous and current vertices. Before hitting , its transitions are with probability for each neighbor . Add a starting state with no preceding vertex, choosing its first neighbor with probability , and an absorbing hit state. This specifies the full Markov chain.
Its directed edges aggregate into types , determined by the two vertex layers. From the next type is or with probability each. From it is with probability and the absorbing state with probability . From it is always . From it is , or the absorbing state with probability each. Every nonabsorbing type has a positive uniformly bounded chance of hitting within at most three more moves, so its mean time is finite.
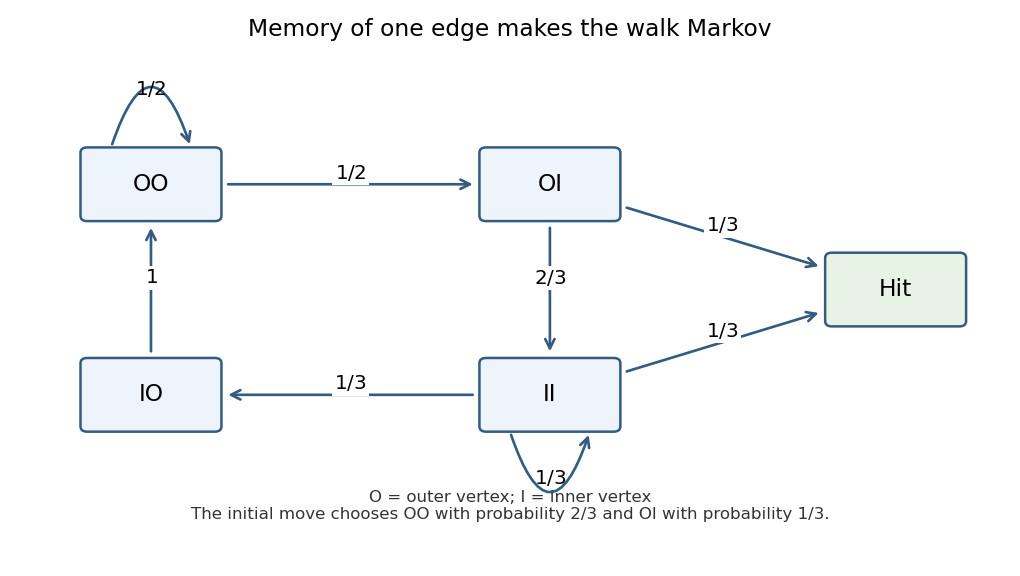
Transition probabilities between the four directed-edge types of the non-backtracking maze walk and its absorbing target
. Details. 
Let their remaining mean times be in that order. The first-step equations areSolving gives , , , . The first move from the initial outer vertex reaches type with probability and type with probability , so the intelligent starting mean isThis hitting a hub from two four-cycles calculation reduces the mean from to , saving moves. Excluding immediate reversal removes wasteful two-step returns, although it does not guarantee that the next move is toward the target.
Articles by others on the same topic
There are currently no matching articles.