Source: released examination bundle,
Part C 2007 11.pdf, pages 345–350. The complete scanned paper, including both halves, is covered. No mark allocations are printed.Put and write the outer asymptotic expansion as . Equating powers in the differential equation givesThe first two equations give and . Since , an integrating factor yieldsHere are matching constants; boundary conditions have not yet been imposed.
In a layer of thickness , the third-derivative and first-derivative terms have sizes and . Their dominant balance requires , soThe local fast modes are exponentials with rates . A mode decaying into the interval can occur at either endpoint: at zero and at one. The zero fast exponent represents the matching outer component. The term is lower order on either fast scale, and even smaller near zero; it creates no further independent layer thickness.
For the left inner coordinate , the equation becomes . At leading order the solution that matches a bounded outer expansion is ; the growing exponential is excluded. The boundary value gives . Since is finite, the possible derivative must vanish, so and .
At the next order, . Its boundary value is zero, giving , while its physical derivative at zero is . Hence , and the left inner expansion is .
At the right endpoint put . The equation is . Matching the outer expansion at one and imposing giveAt the next order, . The solution with no growing exponential, the correct matching polynomial, and isIndeed the operator sends to and sends to .
Add the two decaying inner corrections to the outer solution, subtracting their common matching parts. Since , the composite asymptotic expansion isIt reproduces all three boundary conditions to the retained algebraic orders, with exponentially small interactions between endpoints. The right endpoint has an boundary layer in . The left correction has only amplitude in , but its derivative is and is necessary for the derivative boundary condition. Thus the left layer is a weak derivative boundary layer; if “genuine” refers specifically to an order-one change in the function itself, only the right layer is genuine in that sense. Both nonzero corrections belong in the expansion through .
For an asymptotic sequence , the asymptotic expansion condition is that every fixed truncation has remainder smaller than its last retained term:This limit is taken as in the specified direction or sector. The number stays fixed while taking that limit. The infinite series need not converge for any nonzero parameter.
Let . Repeated integration by parts using the factor givesBoundary terms at infinity vanish, and . ThereforeFor every fixed , this is as , provingFor each fixed the displayed infinite series diverges, since successive term magnitudes have ratio . Its usefulness is precisely that of an asymptotic expansion, not a convergent power series.
By the assumed local equivalence, the remaining part is asymptotic to . Substitute :The last step uses the Gaussian integral and monotone convergence of the upper limit to infinity. Hence
A fixed small-angle approximation alone is insufficient because its error is multiplied by . Introduce the shrinking cutoff , which satisfies but .
On , the Taylor expansion gives uniformly. Thusuniformly there, and the two central integrals are asymptotically equal. On , choose a fixed with for . The sine-integral tail is at most ; the Gaussian tail has the same exponential bound with . Both are , while the central Gaussian integral is asymptotic to . HenceThis justifies the localized Laplace method rather than interchanging a nonuniform approximation with integration.
Matching powers of gives , , and , with and homogeneous initial data for every higher correction. ThusThere is no resonant fundamental forcing at first order. At second order,The first term resonates with the homogeneous oscillator. Solving with the initial data givesConsequently the regular perturbation approximation is for fixed . The first secular term is , at order . It makes the regular expansion nonuniform on times of order .
Use the fast time and slow time . A possible intermediate scale has no leading modulation: the absence of first-order resonance imposes independence of that scale. WriteAt first order choose the nonresonant particular solutionwith any needed fundamental homogeneous correction assigned consistently when matching the initial data. At second order,The coefficient of on the right is . A bounded oscillatory correction requires this resonance coefficient, and its conjugate, to vanish. The quadratic oscillator phase-modulation condition is thereforeIt resums the secular phase accumulation into a slow modulation instead of leaving it as a growing term in the correction.
Write . The modulation equation gives and . Matching the leading initial conditions gives , . ThereforeThe leading amplitude remains two and has no slow growth or decay. The frequency changes from one to ; expanding this shifted cosine recovers the second-order secular term from part (i).
There are bounded first-order waveform changes as well. If they are retained while matching , one may write , where . Thus the first harmonic's coefficient is , with a mean shift and a second harmonic. These bounded shape corrections are distinct from the constant leading amplitude in the zeroth-order multiple-scales solution.
At a vertex with exterior turning angle , the interior angle is . A local conformal map from a half-plane therefore behaves as , so its derivative has local exponent .
On each real boundary interval between prevertices, is constant because the image is a straight side. Across a prevertex its change is the exterior turning angle. Taking , the product has exactly these changes. Dividing by that product removes the corner singularities and leaves a holomorphic nonzero function with constant boundary argument. Schwarz reflection and the regular behavior at infinity make it constant. This gives the Schwarz-Christoffel formulaThere are three freely normalizable real prevertices, because an automorphism of the upper half-plane has three real parameters. After those are fixed, the remaining prevertex parameters are determined by the polygon's shape through the side-length conditions. They are not further independent normalization choices.
If the last prevertex is at infinity, absorb its constant scale into and omit its finite factor:For a bounded polygon, , so this derivative behaves like , consistent with the corner described in the local coordinate .
Use the branch of that is positive for , . The right-half-plane slit mapis holomorphic in the upper half-plane, with derivative , the required Schwarz-Christoffel formula form. Its derivative has no interior zero.
To verify the image and global injectivity, factor the construction. Squaring maps the upper half-plane bijectively onto . Thus ranges over . The positive-real-part square root maps this onto the right half-plane with the interval removed; reciprocation maps it onto the right half-plane slit along . This also identifies the slit tip as a boundary point; the strict inequality in the printed slit description must be understood with that boundary convention.
Approaching the real axis from above givesIn particular maps to the lower infinite prime end , to the tip , and to the upper infinite prime end . The real-axis point at infinity maps to zero on the vertical wall.
Let , so , choosing the analytic branch with ; for example . Let be the source point. For the convention , the Dirichlet Green function in the upper half-plane is obtained by an opposite-sign reflected source:It vanishes for real , has the logarithmic singularity , and is harmonic elsewhere. Conformal invariance of two-dimensional harmonic functions now givesThe branch specified above maps every boundary bank to the real axis, so the Green function vanishes on both slit banks and the vertical wall. Local conformality preserves the coefficient of the logarithmic singularity. If the convention is instead , negate this expression.
Orient the smooth contour so the plus side is to its left. Assume the density is Hölder continuous near the observation point and the integrals converge at any other endpoints. The Cauchy principal value isSubtract from the numerator. The resulting quotient is locally integrable, so its limits from the two sides coincide. For the remaining constant density, straightening the contour gives a half-circle contribution . Division by yields the Sokhotski–Plemelj formulaFor the requested real integral assume and , ensuring integrable endpoints and an interior principal-value pole. Put . Choose analytic off , positive for , and at infinity. Its two boundary values are .
The jump is . The Cauchy representation for this decaying analytic function is therefore . Taking the mean of its two boundary values removes the half-residue terms and gives
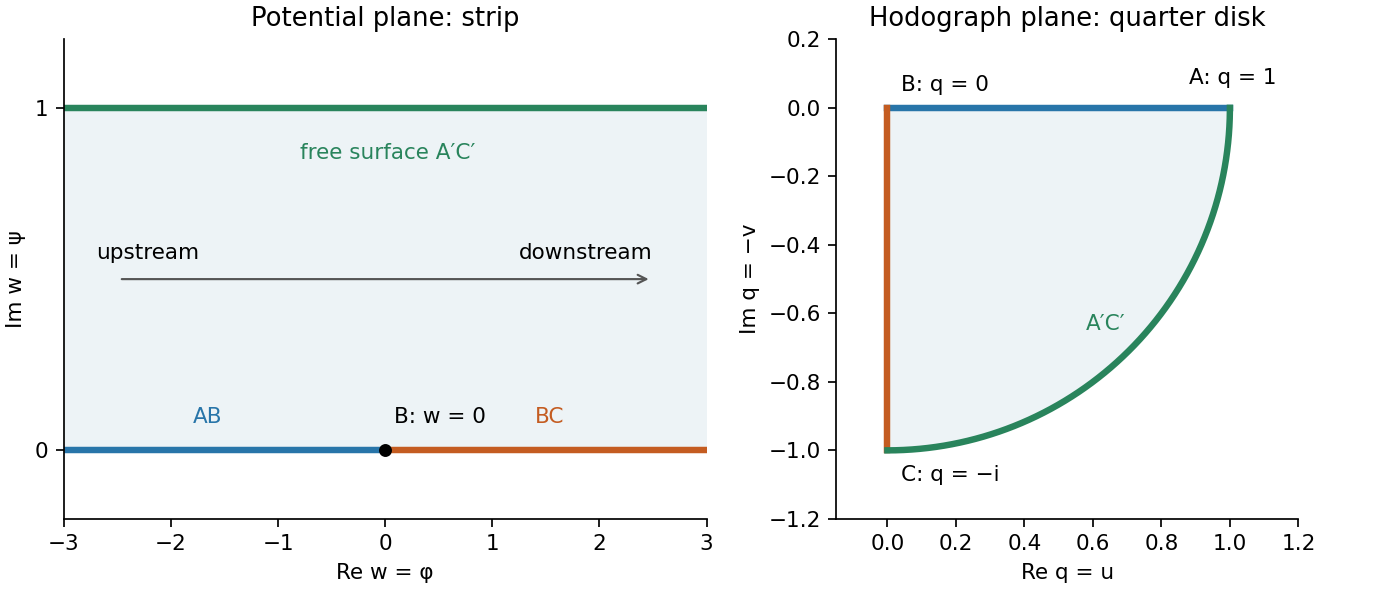
The complex potential of a two-dimensional potential flow maps the fluid region to the strip . Its lower boundary is the wall, with at ; upstream is and downstream is . The free streamline is the upper strip boundary.
Write . The horizontal wall gives positive real velocities running from to the stagnation value at . The vertical wall gives negative imaginary velocities from zero to . On the free surface , with the angle turning continuously from zero to . Thus the hodograph plane domain is the fourth-quadrant quarter of the unit disk, bounded by those two radii and the unit-circle arc.
The following successive conformal maps straighten it. First maps to the lower half unit disk. Next maps to the third quadrant, since and . Finally maps onto the upper half-plane. The three wall landmarks go to respectively.
The strip map also maps onto the upper half-plane, with these same landmarks . The unique half-plane automorphism fixing all three is the identity. ThereforeThe free surface maps to the negative real axis in either construction, as required by its streamfunction value one. This completes the right-angle free-streamline hodograph map construction.
Glue the two analytic functions on their overlap, where their values agree. Since , the two half-planes cover the whole complex plane. The gluing therefore defines an entire function. It is bounded outside a sufficiently large disk by the two given infinity bounds, and bounded on the remaining compact disk by continuity. The Liouville theorem then gives one common constant.
For the standard canonical Wiener-Hopf factorization, first assume the nonzero kernel has Index of a Wiener-Hopf kernel zero and a continuous analytic logarithm tending to zero at both ends of the strip, with sufficient decay for the Cauchy projections. Choose . Let be the line oriented left to right, with its factor used above that line; let be the line oriented left to right, with its factor used below that line.
For , closing the rectangle between the two lines and using the Cauchy integral formula givesThus . Multiplying gives in the overlap. The canonical factors are analytic, nonzero, and normalized at infinity in their respective half-planes, so part (a) yieldsContours may be shifted within the strip without changing their factors on the appropriate side. When necessary, a subtracted Cauchy kernel fixes convergence and the common normalization constant.
The printed hypotheses omit the index and factor-growth qualifications; alone does not ensure them. An explicit counterexample is on , with and . Both functions are analytic and bounded at infinity in their prescribed half-planes, and the relation holds. If admissible analytic factors made their common product a nonzero constant, would force constant and hence proportional to , impossible because has a pole at in the plus half-plane. The natural factors , instead give the nonconstant common polynomial . Thus the boxed constant conclusion is the intended index-zero result, not a consequence of the literal assumptions alone.
Let . On the negative half-line, the integrand magnitude is bounded at infinity by a constant times , which is integrable as when . On the positive half-line the corresponding bound is , integrable when . ThusOn compact subsets strictly inside these half-planes, the same exponential domination absorbs every power of . Differentiation under the integral is therefore valid and proves holomorphy, rather than only absolute convergence. The bars here denote the printed one-sided Fourier transforms, not complex conjugation.
Use the Fourier convention . Transforming the differential equation givesDefine analytic above the downward cut from zero, and analytic below the upward cut from . More explicitly take and . In the strip , put . Then and ; at , , fixing the choice throughout the strip. The decaying mode is .
The positive-half-line boundary value has transform for . Thus and . The transformed boundary relation isLet . Splitting off the pole at zero givesThe left side is analytic in the lower domain up to : its apparent pole at zero is removable. The right side is analytic for . By the supplied boundedness of and , both sides tend to zero at infinity in their half-planes. The gluing and Liouville theorem argument therefore makes their common value zero. ConsequentlyChoose the inversion contour oriented left to right, with any fixed . It passes above the pole at zero and below the branch point at . Fourier inversion gives exactlyThus the appropriate value is . The other proposed value reverses the residue of the boundary step and violates its prescribed positive value.
There is also a far-field qualification in the source. The formula is the intended bounded mixed-boundary solution, but it does not tend to zero along every path to infinity. This can be checked explicitly: in parabolic coordinates , , with , the mixed-boundary convection-diffusion solution in parabolic coordinates isIndeed and ; the identity proves the differential equation. At the boundary value is one, and at its normal derivative is zero. Its traces are for and for , whose one-sided transforms are the expressions derived above.
At a fixed angle away from the positive axis, and . But at fixed and , and . Hence the radial decay statement cannot hold uniformly as printed; the intended decay is away from the downstream boundary layer. The exact expression also identifies its thickness as .
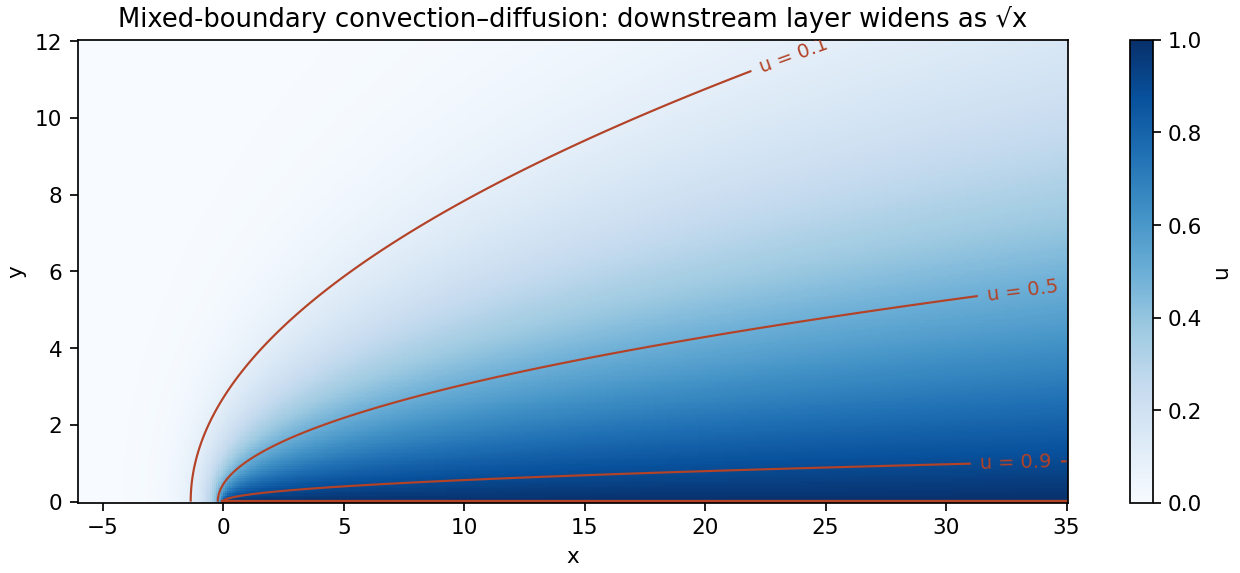
The exact mixed-boundary solution decays away from the downstream boundary layer
. Details. For , the real and imaginary parts of the exponent divided by areThus constant-phase contours satisfy . Through zero, gives the six rays . The three rays have decreasing real part of the exponent and are steepest descent contours; the alternating three are steepest ascent rays.
Through one, the phase is . Its branch passing through that point can be writtenwith the cube root continuous from . The exponent is , so increasing from zero gives descent and decreasing gives ascent.
Deform the finite interval into the ray , , followed by the reverse of the descent branch from one. The integrand is entire, so Cauchy's integral theorem permits the deformation.
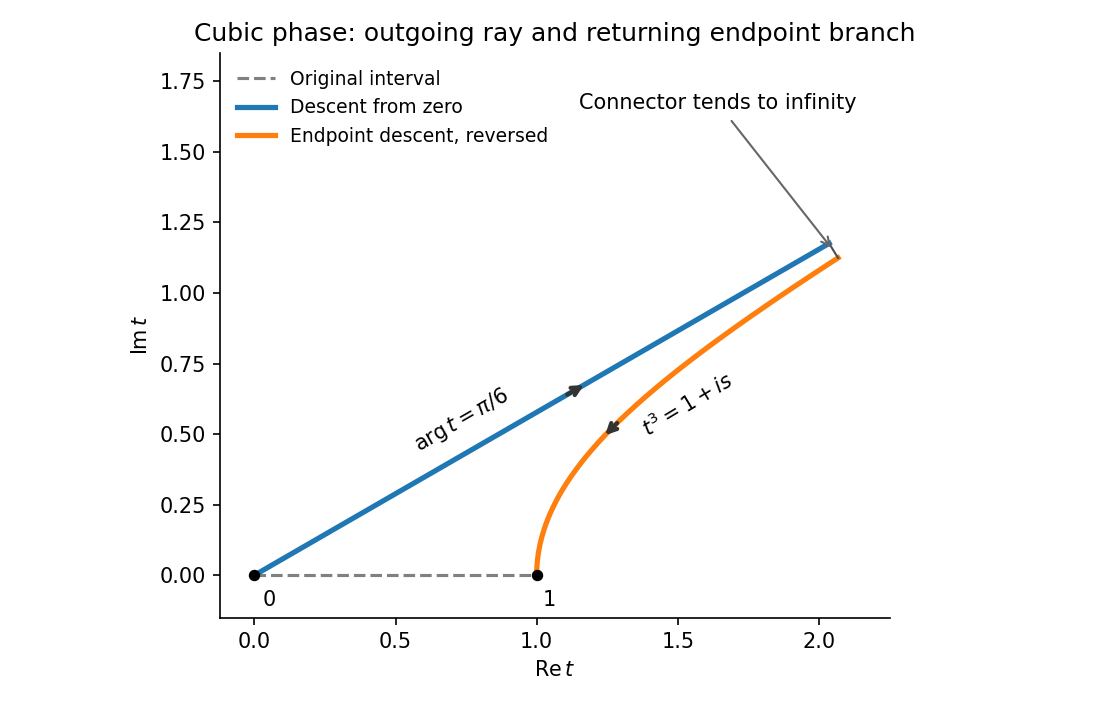
For a precise connector at infinity, use , . Its length is and the exponential has modulus . Its contribution is therefore . This avoids relying on an undifferentiated claim that every large circular arc decays.
A saddle point of the exponential phase occurs where . Hence the only saddle isIt is degenerate: the second phase derivative vanishes there, while the third is . This cubic degeneracy produces the scale. The other endpoint is not a saddle, since the phase derivative there is .
On the selected steepest descent contour put , . Then and . Its exact contribution isUse the Gamma function integral and its recurrence to obtainThere is no remainder here: the complete infinite descent ray was integrated exactly.
The endpoint branch has and . Its reversed orientation in the deformed contour givesAt ,Watson's lemma, or elementary Laplace's method with a Taylor remainder, now yieldsAdding the exact cubic-saddle contribution gives the two leading termsIf the next term is retained, it is . The different powers reflect a degenerate saddle at zero and an ordinary endpoint at one.
Set and write . The equation becomesA dominant balance must compare all three coefficients, rather than just the two derivative terms.
For , balancing diffusion and drift gives . Their common coefficient tends to infinity, so the reaction term is smaller and the leading inner equation isThis derivative is integrable at infinity, allowing an ordinary localized endpoint adjustment. Thus the thickness is in this range.
For , makes all three terms comparable. Keep all of them:One decaying solution is , and reduction of order gives the other. This is a square-root-thickness layer with all terms retained.
For , the first variation scale is . Keep diffusion and reaction, and drop drift at this scale:This leading motion is oscillatory, not a monotone decaying boundary-layer profile. To describe localization one must also resolve the slower damping envelope. Removing the first derivative in the original equation bygivesNear the endpoint the wavelength is , while the envelope changes on . Hence an oscillatory endpoint region is possible, but it has distinct wavelength and envelope scales; calling the diffusion-drift balance alone its leading equation would incorrectly discard the reaction term. This generalizes the oscillatory endpoint with a quadratically vanishing drift.
For , the diffusion-drift balance would require , which gives no shrinking positive power scale. At every shrinking scale the singular drift dominates diffusion, so no regular finite-amplitude diffusion boundary layer of the preceding kind occurs. The coefficient itself is singular at zero; singular endpoint solutions are a different issue from a bounded boundary-layer correction.
Put . The dynamical system isThe nullclines are and . There are no equilibria, since they never intersect. To the right in the plane means , and to the left means . The arrows point upwards above and downwards below it.
Near the repelling critical manifold , an orbit can move on the slow scale, with . More precisely the slow trajectory has . Away from this narrow region, changes rapidly on ; an change of in a fast layer has .
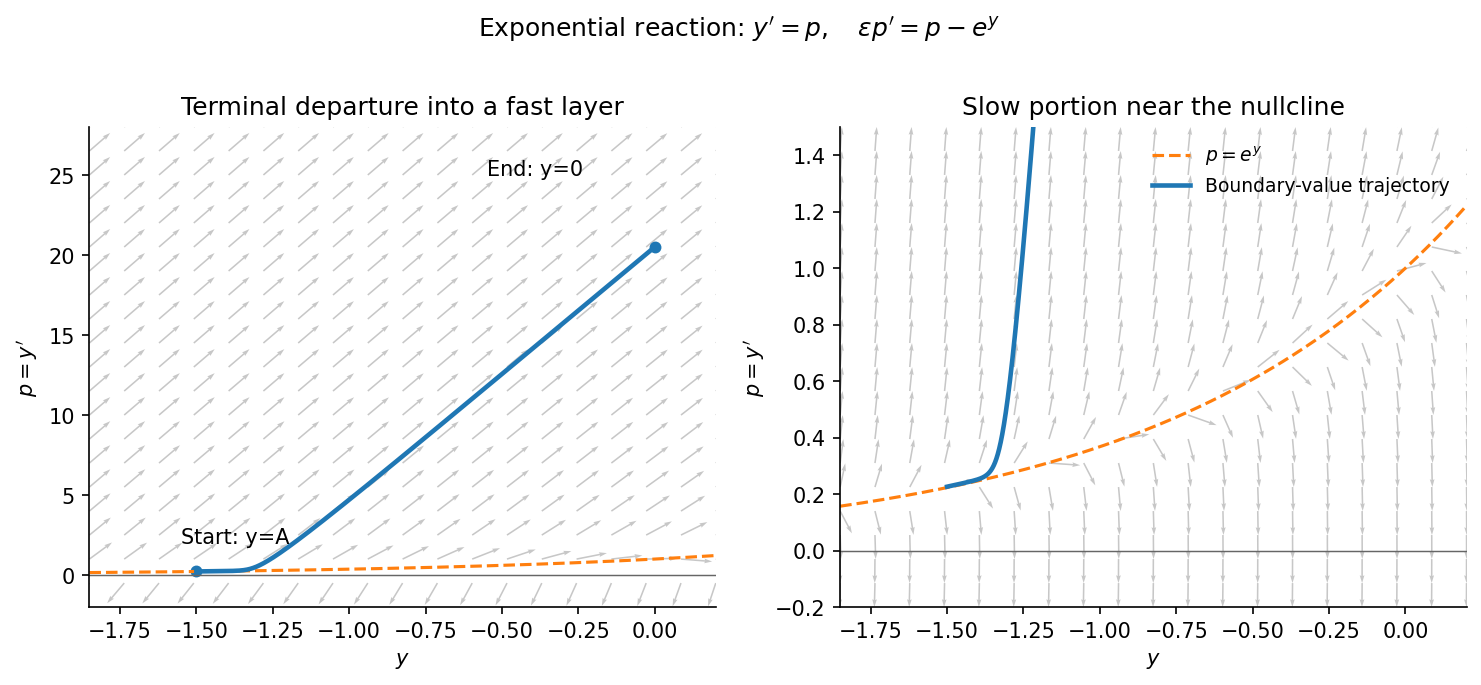


For example, take a fixed . A trajectory starting at can shadow the slow curve, then depart upwards so that rapidly increases to zero at the right endpoint. This gives a terminal outflow boundary layer at , of width . For , the outer trajectory reaches a positive value near one, and the terminal adjustment is downwards: the orbit turns below the nullcline, crosses , and returns to . The boundary layer is still at . These directions follow from the phase portrait and agree with the matched solution below.
In the outer expansion, omit to get . Integrating and imposing the left boundary condition givesThis is regular throughout . Its right-end value is , generally different from zero.
At set . The equation is , so the leading inner expansion is . Matching as gives , while gives . ThusThe common part is . Subtract it once when forming the additive composite expansion:There is one generic boundary layer, at the right endpoint, of width . A left-end exponential would grow into the interval and cannot supply a decaying matching correction. At the displayed layer amplitude vanishes; the leading outer solution already meets the right condition, though a smaller correction can still be needed at higher order. The composite meets exactly and up to an exponentially small term.
Choose in the WKB approximation and substitute . The leading equation isso take . At the next order,givingup to an absorbed constant. Label the recessive and dominant branches respectively byThe formal outer solution is . The point zero is a simple wave turning point: vanishes and the WKB amplitude diverges.
The boundary condition at infinity selects , with to be fixed by matching. This statement concerns the actual recessive branch. One cannot literally send in the truncated small- formulas: their ordering fails when is no longer small, and their common Gaussian factor would then spuriously suggest that both branches decay.
To justify the selection, remove the first derivative exactly with . ThenThe coefficient is positive for , so it has distinct dominant and recessive branches. For very large , the dominant branch restores growth of exponential rate , while the recessive branch decays. Matching to this recessive branch removes .
Balance against near the wave turning point. With , their equality requires , hence . The rescaled equation isIts leading equation is the Airy ordinary differential equation . ThusLet ; then . The left boundary condition becomes , orThis determines one linear relation before the far-boundary matching condition is used.
In the overlap region , write . The supplied Airy function asymptotics giveThe outer prefactor tends to one in this overlap. ThereforeThe recessive condition gives and . Hence the leading inner answer isAway from the turning point, the matched WKB approximation isA useful multiplicative composite expansion through the turning region is : it is finite and normalized at zero and matches the displayed outer expression for fixed positive . It is a small- approximation across the turning point, not a claim of relative uniform accuracy out to arbitrarily large .
Write the complex potential of a two-dimensional potential flow as , and the complex velocity as . The lower solid wall has . The upper solid wall and its continuing free streamline have constant equal to the far-field volume flux per unit depth, namely . Consequently the potential domain is the infinite stripThe points correspond to , to , and is by the chosen potential normalization.
In the hodograph plane, the horizontal wall has real positive, the vertical wall has imaginary positive because the physical velocity is downward, and the fluid free boundary has . The upstream reservoir velocity tends to zero, the outgoing velocity is one, and the velocity at is . Thus the hodograph is the first-quadrant unit quarter disk, with at , at , and at .
For the potential strip, exponentiation followed by a Möbius transformation givesSince lies in the upper half-plane, so does . The map sends to , to infinity, and to zero.
For the first-quadrant hodograph plane, successively square , apply , and then use a negative square:The first map takes the quarter disk into the upper half of the unit disk. The fractional transformation takes this to the second quadrant, whose negative square is the upper half-plane. The boundary points map to , as required. Uniqueness of the normalized conformal map therefore identifies the two expressions:
On the free streamline choose with . The lower endpoint of this parameter interval is , and approaches . The fractional expression in the map isHence , and the branch on the upper edge of the potential strip isDifferentiate to obtain . Since , the chain rule givesThe sign and interval are consistent with the free surface moving to the right and downward from .
Separate the real and imaginary parts of the derivative and integrate from :Because and , these integrals areAs , and . This must equal the outgoing stream depth , so
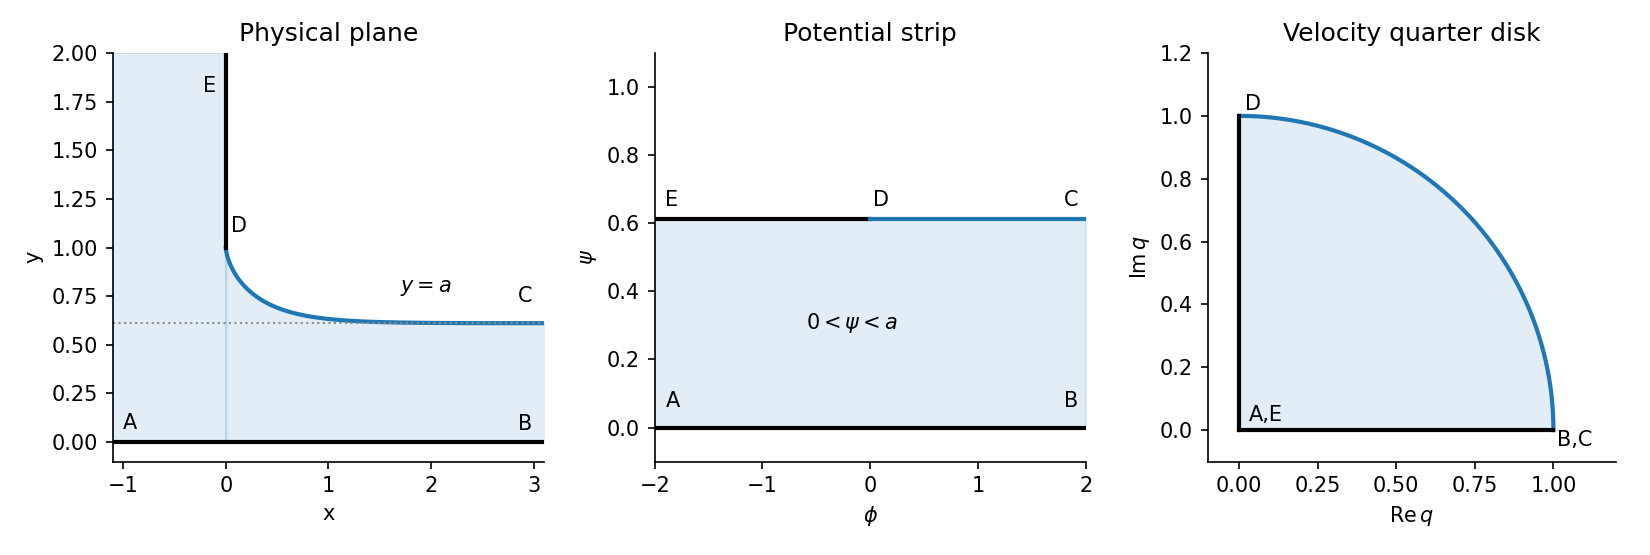
Draining free surface and its potential-strip and hodograph representations
. Details. 
The solution has a vertical tangent at and approaches the horizontal line downstream, agreeing with both solid-wall and free-streamline conditions.
Orient the contour so that the plus side is on the left; for a positively oriented simple closed contour this is its interior. If is a smooth arclength parametrization with , define the Cauchy principal value by deleting a symmetric interval and taking . This pairs the two singular sides at equal local arclength.
Near , write . The second term divided by is regular because is analytic there. For the constant term, indent the contour on either side of by a small semicircle. Its limiting contribution to the Cauchy integral is , while the remaining contour tends to its principal value. This proves the Sokhotski–Plemelj theorem:In particular and for the given integral equation.
Define inside and outside. Its jump is , and it vanishes at infinity. ThereforeIndeed, the difference between the two sides has no jump, extends analytically across the smooth contour, and vanishes at infinity; Liouville's theorem makes it zero. Applying the Sokhotski–Plemelj theorem again,Thus the normalized closed-contour singular integral operator is its own inverse.
For an admissible Laplace integral solution, differentiation under the integral sign and integration by parts giveChoose endpoints for which the boundary term vanishes. Setting the density in braces to zero givesTwo suitable contours are the rays and , with a continuous square-root branch on each ray. The Gaussian decays at infinity, and tends to zero at the finite endpoint. The integrals converge for every finite .
To check independence rather than merely exhibit different paths, defineWith unit normalization, the two solutions satisfy and . Their Wronskian at zero is , so they form an independent pair.
Strictly, the printed necessity claim requires an injective contour-transform class as well as vanishing endpoint terms. An arbitrary contour representation may contain a null weight in a contour Laplace representation, so a nonzero solution alone does not force every representing to have the displayed form. The calculation constructs the canonical density and two valid independent solutions; it does not assume uniqueness for unrestricted contour densities.
Extend to be zero for . Define for andThen the full-line equation is . Use the Fourier transform conventionUnder the corresponding growth bounds, the positive-support transform is analytic above a horizontal line and the negative-support transform below a horizontal line. If both functions have suitable subexponential growth, the basic domains are respectively the upper and lower half-planes; exponential decay can enlarge these to overlapping strips. The convolution theorem gives .
The Wiener-Hopf method factors into functions analytic and nonzero in the respective domains. After multiplicative or additive separation, the two sides continue to one entire function, whose growth determines a polynomial by Liouville's theorem. Real-axis zeros must be assigned consistently with the inversion contour, rather than divided out without specifying a side.
For , direct integration gives , soRearrange the Wiener-Hopf factorization asThe left side has the positive-support analytic continuation and the right side the negative-support one. Their growth, from the supplied bounds, makes the common continued function a constant . ConsequentlyFor this kernel, on the negative axis is a multiple of , so the latter transform is analytic for . The common strip can therefore be chosen as . In particular the inversion line must pass above both real poles of .
Set . ThenThis is the transform, on , ofEquivalently, Fourier inversion closed below the inversion line for picks up the two real poles with clockwise orientation.
As a direct check, let . Since , the equation gives . At zero, differentiation of the integral gives , so ; this sets the sine and cosine coefficients equal. Direct substitution, or the transforms above, then verifies the full integral equation, not merely its differentiated form.
For each fixed , the next term must be negligible relative to its predecessor:The ratios are understood where their denominators are nonzero near the limiting point, or equivalently through the little o notation definition. For example form an asymptotic sequence.
For every fixed truncation index , the remainder must be smaller than the last retained term:This is an asymptotic expansion relative to the sequence in part (i). The number of retained terms is fixed before taking the limit. The associated series need not converge for any nonzero parameter; its role is to give successively smaller truncation errors. If is an asymptotic sequence, the same condition can be stated as a remainder when the next expansion condition is available, but the displayed little o notation formulation is the defining one.
Take and . Then , so . However,for every , and this ratio does not approach one. Thus asymptotic equivalence need not survive exponentiation. A small relative error between large exponents can leave a nonvanishing additive error. This is the distinction in asymptotic comparison of exponential functions.
Articles were limited to the first 100 out of 183 total.
Articles by others on the same topic
There are currently no matching articles.