A densely defined operator on a Hilbert space is self-adjoint when it equals its adjoint operator, including equality of their operator domains:For a bounded linear operator defined on the whole Hilbert space, this is equivalent tofor all vectors . For an unbounded self-adjoint operator, the domain condition is essential: the inner-product identity on alone gives only a symmetric operator.
Let on a Hilbert space, with time-independent self-adjoint operator , and conserved quadratic energy . If , set with and . This gives . For , and , soby the Cauchy-Schwarz inequality. Since , . Positivity of follows from and . Thus a negative direction of the restoring energy yields an exponentially growing solution without a normal-mode expansion or a variational spectral theorem. If is positive definite, conserved instead controls the energy norm; a bound in the original Hilbert space norm additionally follows from a coercive lower bound on .
A densely defined semibounded symmetric operator on a Hilbert space has a canonical semibounded extension that is a self-adjoint operator obtained by closing its quadratic form. After shifting the lower bound to zero, complete the initial form domain in the norm ; the associated closed form determines the Friedrichs extension. For the positive Laplace-Beltrami operator on a polygonal surface, this specifies the finite-energy realization at corners. Different choices of the initial form domain impose Dirichlet boundary conditions, Neumann boundary conditions, or mixed boundary conditions; the extension does not choose the boundary condition independently of that domain.
For a bounded self-adjoint operator , a spectral Weyl sequence at consists of unit vectors with . Such a sequence exists exactly at points of the spectrum of a bounded operator. If no sequence exists, the shifted operator is bounded below, with closed range and zero kernel. Self-adjointness then makes its range dense, so it is invertible. This spectral criterion is different from the equidistribution Weyl criterion.
A singular Weyl sequence for a bounded self-adjoint operator at is a spectral Weyl sequence that also converges weakly to zero. Such a sequence exists exactly when is in the essential spectrum of a bounded self-adjoint operator. An infinite-dimensional shifted kernel gives a weakly null orthonormal sequence. If that kernel is finite-dimensional but the shifted range is not closed, choose approximate null vectors in the kernel complement and extract a weakly convergent subsequence; its limit belongs to both kernel and complement, so is zero.
A densely defined linear operator on a complex Hilbert space is self-adjoint when its adjoint operator has exactly the same domain and agrees there. Symmetry only requires and does not guarantee self-adjointness. A self-adjoint operator is a closed operator with real spectrum. Domains matter for differential operators and unbounded multiplication operators.
Positivity makes bounded below with dense closed range for every , excluding negative spectral values. Conversely if the spectrum is nonnegative, has spectrum in by the resolvent spectral mapping identity. The numerical-range endpoint approximate-eigenvalue theorem gives , and positive-form Cauchy-Schwarz inequality gives . For , .
Symmetry gives when is nonreal. Closedness makes the range closed; its orthogonal complement is , so it is also dense and hence surjective. This proves the resolvent estimate and reality of the spectrum. Equality of the adjoint domains is needed in the range argument.
For a self-adjoint operator , solving requires to be orthogonal to every , because . When the range is closed, this condition is also sufficient: and closedness gives . In finite dimensions the range is automatically closed. This Fredholm solvability condition determines amplitude equations by projecting perturbative forcing onto critical eigenfunctions.
A self-adjoint operator is positive definite when for every nonzero vector in its domain. In finite dimension it is invertible and has positive eigenvalues. In infinite dimension, strict positivity of individual quadratic-form values need not give a bounded inverse; the stronger uniform bound with supplies coercivity.
For maps and between finite-dimensional inner product spaces, with , the operator is positive definite. Its quadratic form is , whose zero set is . This uses the adjoint operator relation .
On , the bounded self-adjoint operator is strictly positive. Yet lies in and would require the non-square-summable vector . A positive uniform lower bound, rather than strict positivity alone, guarantees a bounded inverse for a bounded self-adjoint operator.
Every self-adjoint operator on a finite-dimensional real or complex inner product space has an orthonormal eigenbasis, and all its eigenvalues are real. In orthonormal coordinates, a real symmetric matrix has the form , with an orthogonal matrix and a real diagonal matrix. A complex Hermitian matrix instead has , with a unitary matrix and its conjugate transpose. These are the self-adjoint cases of the spectral theorem; Axler gives the real and complex finite-dimensional statements in Section 7B.[ref]
https://linear.axler.net/LADR4e.pdf. Sheldon Axler, Linear Algebra Done Right, fourth edition, Section 7B, Theorems 7.29 and 7.31; accessed 2026-10-11
An orthonormal eigenbasis turns a seemingly coupled linear map into independent scalar multiplications while preserving lengths and angles. If and , thenThe last identity removes every cross term from the quadratic form. The eigenvalues tell us whether it is positive, negative, or mixed in sign, and the eigenvectors identify the corresponding directions. This connects positive-definite matrices, quadratic forms, and the Hermitian Rayleigh quotient range.
For a fully computed example, takeDirect multiplication gives and . Their dot product is zero and each has norm one. ThusWriting changes into . Its level set is therefore an ellipse with semiaxis lengths and , along and . The coordinates change, but the ellipse does not: orthogonal diagonalization reveals its existing geometry.
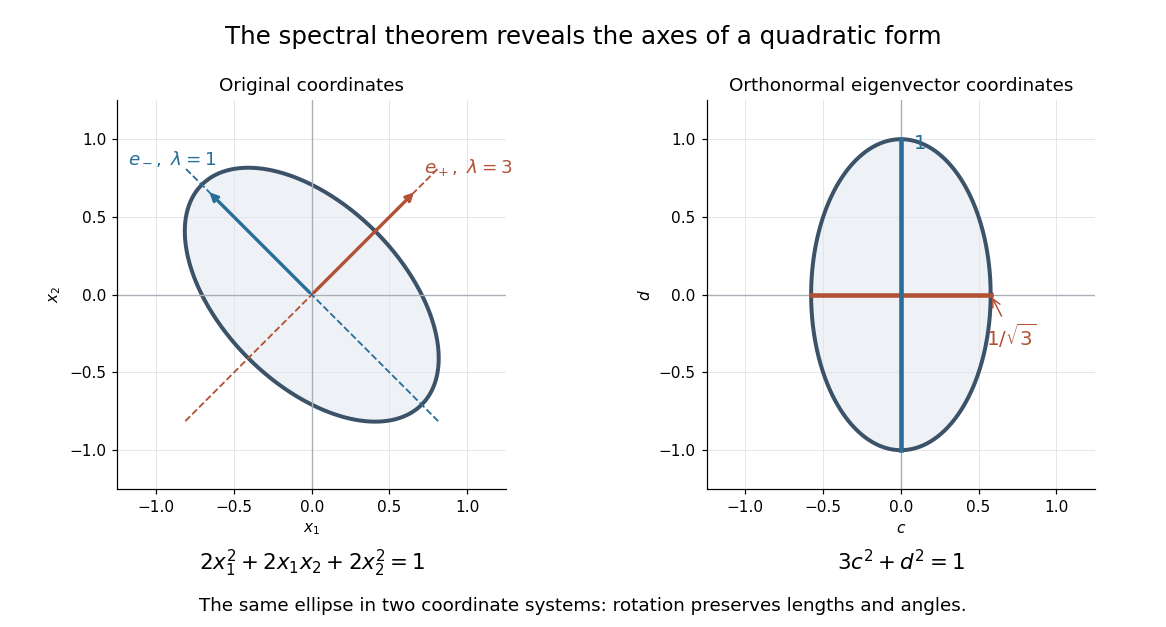
An orthonormal eigenbasis removes the cross term from a quadratic form and reveals the axes of its ellipse
. Details. For distinct eigenvalues, orthogonality follows at once from self-adjointness: . Within a repeated eigenspace, choose an orthonormal basis; arbitrarily chosen eigenvectors of the same eigenvalue need not be orthogonal. One outline of the full argument finds an eigenvector, observes that its orthogonal complement is invariant, and repeats in that smaller space. Merely having real eigenvalues is weaker: has two real eigenvalues, but its eigenvectors and are not orthogonal.
A Hermitian operator on a -dimensional Hilbert space, with distinct eigenvalues all belonging to , must occupy this entire grid. This follows from the pigeonhole principle: the set of possible values and the set of distinct eigenvalues have the same cardinality. Its minimum eigenvalue is zero, so the operator is necessarily singular. Distinctness therefore does not imply invertibility; it forces a one-dimensional kernel in this specific complete-grid setting.
An orthonormal eigenbasis of a linear operator is an orthonormal basis consisting of eigenvectors. Each vector can be reconstructed from its scalar components along those mutually perpendicular unit directions. With the convention that the inner product is linear in its first argument,The finite-dimensional spectral theorem supplies such a basis for a self-adjoint operator. In its two-dimensional example, the coordinates of are along and along . The operator multiplies those coordinates by and , and reconstruction gives .
Repeated eigenvalues permit different orthonormal choices within one eigenspace, so the basis need not be unique. The spectral projection of a self-adjoint matrix onto that entire eigenspace is unique: it keeps the geometrically meaningful component without choosing individual axes inside it.
For a finite-dimensional Hermitian matrix , its spectral projection is the orthogonal projection onto the eigenspace for . In an orthonormal eigenbasis, the displayed sum is over every basis vector with that eigenvalue. The projection is independent of the choice of basis within a repeated eigenspace. For distinct eigenvalues ,This is the spectral decomposition grouped by distinct eigenvalues: decompose a vector into orthogonal pieces, then scale each piece. For the matrix ,Thus and : the two pieces add back to . Squaring the matrix simply squares each scalar, , and similarly the matrix exponential is . Spectral projections of a self-adjoint matrix turn repeated matrix calculations into scalar calculations on fixed vector subspaces.
On polynomials with weighted inner productthe operatoris self-adjoint because . Its eigenvalues on polynomials of degree at most are ; its eigenvectors are scalar multiples of the Laguerre polynomials.
At eigenvalue zero the Laguerre differential operator on polynomials gives , equivalently . Thus and the displayed solutions follow from the exponential integral. For any , all solutions with can be written . The choices and are linearly independent despite sharing that one prescribed value.
The second branch grows as at infinity and has a logarithmic singularity at zero. It is consequently excluded from the regular weighted square-integrable eigenproblem with weight . Only the constant zero mode remains in that self-adjoint realization. A normalization at one interior point alone is not enough to select a unique second-order solution.
For polynomial solutions of the Laguerre differential equation, put . The equation gives . Integrating by parts gives the displayed identity; the factor kills the endpoint at zero and exponential decay kills the endpoint at infinity. Its left side is symmetric in , so subtracting the swapped identities proves orthogonality for distinct degrees. This provides a direct energy proof of orthogonality for the Laguerre polynomials without assuming their norm formula.
The ordinary Laguerre polynomials, normalized by , are orthonormal for the weighted inner product displayed above. Their coefficient formula is . To prove the relation, use Rodrigues' formula and integrate by parts times against . For its th derivative vanishes. At zero every derivative of of order less than vanishes, and at infinity the exponential kills every polynomial boundary term. For , , so the integral is . Symmetry covers . Thus these are orthonormal without an extra normalization factor.
The generating function holds for and fixed . From Rodrigues' formula, . Sum first over , using , and then over to obtain the exponential function. The absolute-value double series is finite for , justifying the rearrangement. Alternatively, the weighted inner product and the Laplace transform of a Laguerre polynomial extract the coefficient .
For the ordinary Laguerre polynomial , apply the Laplace transform to each term, using for . The binomial theorem givesThis proves the formula for every nonnegative integer . In particular has transform .
Set . Direct differentiation gives . Apply the Leibniz rule to differentiate times:Hence . By Rodrigues' formula, , so the next two derivatives are and . Substitution gives the displayed Laguerre differential operator on polynomials eigenvalue equation. This derivation also covers .
The Laguerre polynomial normalized by has coefficients . By the Leibniz rule, this is equivalent to Rodrigues' formula, . For any polynomial of degree below , applications of integration by parts give . All endpoint terms vanish: derivatives of of order below vanish at zero and decay at infinity. Since , the same calculation givesThus these orthogonal polynomials are already an orthonormal set for the weighted inner product with weight .
For integers , the standard Rodrigues' formula has the endpoint value and squared norm displayed above. The lowest-power term after differentiations is , giving the endpoint value after division by . For the norm, integrate by parts times against the same polynomial; its leading coefficient is , so the final derivative is . All boundary terms vanish and the remaining Gamma function integral is . Normalizing the value at zero to one divides the polynomial by and its squared norm by the square of that factor. Only when or do these normalizations already coincide.
Articles by others on the same topic

In the context of linear algebra and functional analysis, a self-adjoint operator (also known as a self-adjoint matrix in finite dimensions) is a specific type of linear operator that has a particular property regarding its adjoint.

