In Cartesian coordinates, use the Levi-Civita symbol and the Einstein summation convention to expandThe contraction of the two symbols uses the Kronecker delta, and the final step is the product rule. Thus the convective acceleration identity isPut . The curl of a gradient vanishes, and the curl of a cross product identity givesSince the divergence of a curl is zero, taking the curl of the first identity yieldsTwice continuous differentiability suffices for the mixed-derivative identities used here.
Away from the axis, cylindrical coordinates put the field in the line vortex formThe only potentially nonzero component of its curl isThe other components vanish because there is no axial dependence and no radial or axial velocity. Thus the curl is zero for ; the field is singular on the axis, so a classical curl there is not defined.
For a spanning surface avoiding that axis, the smoothness hypotheses of Stokes theorem hold and give . If the enclosed planar region contains the axis, the singularity prevents applying that theorem directly. Excise a small disk about the origin. The resulting annulus has zero curl, so its outer circulation equals the counterclockwise circulation on the small circle:This sign assumes positive, counterclockwise orientation. Clockwise orientation gives ; more generally the value is times the winding number about the origin. A curve through the origin is excluded because its integral is singular. In the distribution interpretation the missing vorticity is concentrated on the axis as , explaining the nonzero circulation despite zero classical curl away from it.
Since the endpoints represent the same point of the tube, both density and diffusive flux must match. For a positive diffusion coefficient , the periodic boundary conditions areFor separation of variables, periodic spatial modes solve and have time factors . The constant mode has no decay. The periodic diffusion on a circle solution is thereforewhere the Fourier coefficients areThe expression for includes .
The specified profile is even, so . Its mean follows from , giving . For , two integrations by parts giveConsequentlyAll nonconstant normal modes decay for , so the density becomes uniform:The conserved total amount is . The initial cusp at zero is compatible with an L2 space solution and is immediately smoothed by diffusion. At there would be no relaxation, so positivity is needed for this long-time conclusion.
Expand the radial modified Helmholtz equation as . Setting gives , soBoundedness at zero requires , whereas boundedness at infinity requires . The respective adapted homogeneous solutions are thereforeThe first has limit one at zero. Their Wronskian is . Since the highest-derivative coefficient of is , the Green function must have first-derivative jump . The radial modified Helmholtz Green function on the half-line isIt is continuous at the source, and its derivative jump is , giving . For fixed source it tends to as and decays at infinity. This kernel is for the original operator and ordinary measure ; multiplying the equation by would change the source normalization.
For the compact source, split the integral at when . The needed antiderivatives areThuswhile for the result is . Simplifying givesThe continuous value at zero is , and . Both and match at , so no extra Dirac delta appears there. The only homogeneous solution bounded at both ends is zero, establishing uniqueness.
Split the Fourier transform integral at zero:By Fourier inversion applied to this pair, or by the residue theorem, the other transform isFor example, inversion with gives ; evenness supplies the desired sign convention.
Take the spatial Fourier transform of the Laplace equation. For it gives . Removing the exponentially growing solution and matching the boundary givesAt this formula is interpreted by continuity; a single transform value does not alter the inverse integral. The previous transform pair identifiesthe Poisson kernel for the upper half-plane. The convolution theorem therefore gives the Poisson integralThis is the bounded harmonic solution for bounded decaying data, or the corresponding solution in an appropriate Fourier class. Such a growth condition matters if vertical decay is interpreted only pointwise: the nonzero harmonic function vanishes on the real axis and tends to zero for fixed as , but grows rapidly in and has no ordinary spatial Fourier transform. It can be excluded by requiring boundedness; the stated pointwise limits alone would not establish uniqueness.
For the interval data, direct integration gives the Poisson extension of interval boundary dataAs it approaches for , zero for , and at . At those jump points the prescribed isolated values cannot be attained by a continuous extension; they do not affect the integral. The solution decays vertically, with for fixed and large .
An eigenvalue and associated eigenvector satisfy . The characteristic polynomial has degree equal to the positive matrix size. The fundamental theorem of algebra gives a complex root, at which is singular and therefore has a nontrivial kernel. Hence every nonempty square complex matrix has an eigenvector.
A nondiagonalizable example is the Jordan block : its only eigenvalue is zero, and its eigenspace is one-dimensional. A Hermitian matrix satisfies and has an orthonormal eigenbasis by the spectral theorem. One proof finds an eigenvector, notes that its orthogonal complement is invariant, and repeats. Its eigenvalues are real becausewhere .
With all eigenvalues negative, is invertible. Its same complete eigenbasis givesSome powered eigenvalues can coincide, but the original eigenvectors remain a complete basis. Writing , the convergent matrix exponential series givesThus the matrix inverse from a decaying matrix exponential isThe identity printed in the original PDF is missing a minus sign. Already for the one-by-one matrix its integral is , whereas its inverse is . Equivalently, integrating gives , confirming the correction without diagonalization.
Complete the square in the quadratic form:The real invertible linear transformationsets , , , giving . The same transformation givesIts signature is . By Sylvester's law of inertia no real invertible change of variables can turn this second form into a sum of three positive squares.
The trace of a square matrix is . Expanding a product and interchanging its finite sums givesHence every commutator has trace zero. Taking the trace of gives . Over the complex numbers, with , this forcesFor that value, choose , or any commuting pair. For every nonzero the trace contradiction proves nonexistence. The finite matrix size is essential to this trace argument.
Differentiate the eigenvalue equation along the assumed smooth normalized eigenbranch:Since is real symmetric, . Multiplying the differentiated equation by and using cancels the terms containing :Thus the finite-dimensional Hellmann–Feynman theorem givesEquivalently, differentiating the normalization gives and eliminates those terms from the derivative of . The proof needs the smooth eigenbranch assumed in the question; the smallest eigenvalue need not be differentiable at an arbitrary crossing without that assumption.
Evaluate the derivative along real and imaginary increments. For a holomorphic function, both give the same value:Equating real and imaginary parts yields the Cauchy-Riemann equations
Differentiate the Cauchy-Riemann equations and use equality of mixed partial derivatives, which holds because holomorphic functions are smooth:Thus both parts are harmonic functions.
The Cauchy-Riemann equations give . ThereforeThe gradient is normal to a regular level set, so these curves intersect orthogonally wherever their gradients are nonzero. At a stationary point, where both gradients vanish, a regular curve tangent need not exist; the algebraic identity remains valid.
The rotation from the Cauchy-Riemann equations is invertible. HenceThus their stationary points coincide, including degenerate ones.
For a harmonic function, put and . Since , its Hessian matrix isA nonzero determinant is therefore negative, and the two real Hessian eigenvalues are . At a stationary point the quadratic term of the Taylor expansion has both signs. Consequently every such nondegenerate stationary point is a saddle point. This is the nondegenerate stationary points of a planar harmonic function criterion. The same argument applies to , whose stationary points coincide with those of . A zero Hessian determinant is outside this second-order classification.
Assume the image of the domain of lies in the domain where is holomorphic. The complex chain rule givesso the composition is holomorphic, including at points where . Its real part is therefore a harmonic function.
A direct verification uses the composition of harmonic conjugate pairs. The multivariable chain rule givesThe Cauchy-Riemann equations imply ; parts (i) and (ii) remove the last three terms. Since is harmonic in its own variables,
In monic form the Chebyshev differential equation has and . Both are analytic near zero, so it is an ordinary point. At , and are analytic; at , and are analytic. Thus both endpoints are regular singular points.
Insert and equate coefficients. The recurrence relation isExplicitly the factors are for and for . The lowest equation for forces . For , one may choose to select an even solution, independent of the odd solution. The leading coefficient is free in either chosen parity branch.
For a nonterminating branch the consecutive parity-term ratio tends to . Hence the ratio test gives convergence for , and radius of convergence one. Terminating branches are polynomials with infinite radius. For an integer, choose of the same parity as : the recurrence stops once , producing a degree- Chebyshev polynomial. Normalization at gives all nonzero coefficients through degree three:
Set . Direct differentiation gives , so the equation becomes . For , . A polynomial has finite derivative at , and therefore , forcing . Also , so . For , the transformed solution is affine in and the same derivative condition removes its linear term. ThusThe endpoint values follow by continuity. The finite-derivative condition is what excludes the independent nonpolynomial branch, rather than normalization alone.
For fixed endpoint values, the Euler-Lagrange equation is . Along a stationary curve, the chain rule givesWhen , the Beltrami identity therefore takes the requested sign convention
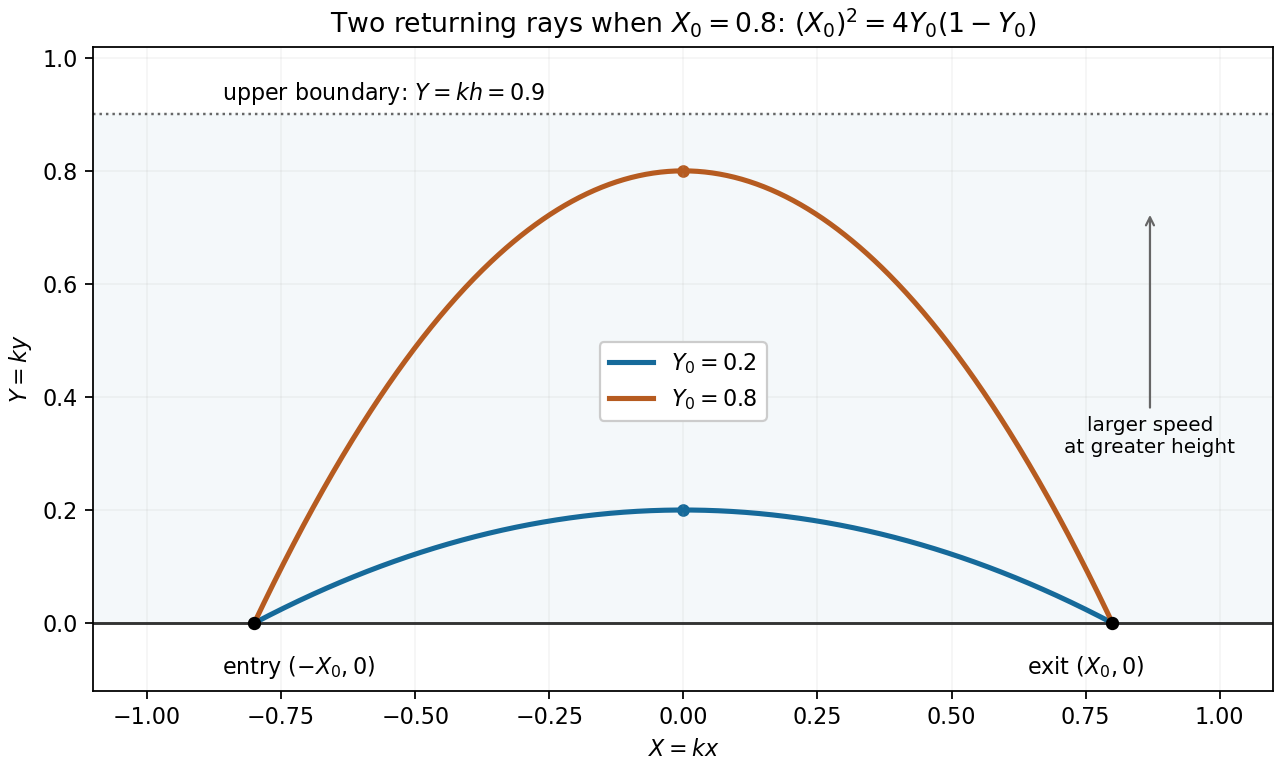
By Fermat principle, the elapsed-time integrand for the given speed is . ThusThe constant is negative for a finite regular ray. Squaring gives . At a maximum height , the slope is zero, so . HenceSeparate variables on either side of the turning point. Integration gives the parabolic light rays in a reciprocal-square-root speed profileThe quadratic opens downwards, with its greatest height at . The positive index condition holds throughout the layer because . Vertical rays are a separate zero-horizontal-momentum case, outside the regular graph representation ; they are not returning rays of the type considered below.
Equal endpoint heights at force . Setting givesFor nonzero separation, a real returning ray requires and has candidate turning heightsOnly choices satisfying are rays wholly within the specified layer. Depending on its thickness there may be two, one, or no admissible choices; at zero discriminant the two algebraic candidates coincide. The entry and exit points at are interpreted as limiting boundary points of the open medium.

Use the real weighted inner product and the energy bilinear form . Integration by parts, the endpoint conditions, and the Sturm-Liouville problem giveThus orthonormality in the stated expansion givesand hence the Rayleigh quotientThe expansion is understood for nonzero admissible functions with finite norm and energy.
For a general endpoint-preserving variation , explicitlysoThe fundamental lemma of the calculus of variations shows that stationarity is exactly the eigenvalue equation with . Conversely an eigenfunction has vanishing first variation and quotient equal to its eigenvalue. Completeness gives the same weighted-average formula for any nonzero admissible expansion, even one with zero ground-state coefficient. Since every ,This is the Rayleigh-Ritz variational principle.
For the interval problem, the normalized Dirichlet eigenfunctions and their eigenvalues, with the paper's zero-based indexing, areFor , direct integration gives and . ThereforeThe sine expansion and Rayleigh quotient of a parabolic Dirichlet trial follow from the coefficient integralConsequently the requested expansion hasEquivalently . In particular : the first excited eigenfunction is antisymmetric about , whereas the trial function is symmetric. Since , the final ratio is exactlyThe first nonzero correction is , not . Reindexing only the nonzero terms would change the meaning of the requested ratio and is not used here.
Multiplying by makes the first two terms a total derivative:The resulting Sturm-Liouville form isEquivalently, an integrating multiplier must satisfy , which reduces to and gives up to a constant. The coefficient is positive for and vanishes linearly at the left endpoint; the weight is positive throughout. The boundedness condition removes the logarithmic local branch, giving the no-log boundary condition at a linearly vanishing Sturm-Liouville endpoint.
The appropriate weighted inner product and Sturm-Liouville operator areFor two functions obeying the endpoint conditions, integration by parts gives the Lagrange identity for a Sturm-Liouville operatorAt , both and vanish. At , the factor tends to zero while the functions and their first derivatives remain bounded. Thus the boundary form vanishes at both ends.
This gives the regular self-adjoint differential operator realization: its singular-end condition is , together with . The bounded classical eigenfunctions satisfy exactly this no-log choice. More precisely the operator domain is the maximal differential-operator domain in the weighted space with these separated endpoint conditions; the preceding calculation verifies its self-adjoint boundary form, rather than merely the differential expression's formal symmetry.
Let be an eigenfunction, allowing complex values for the reality argument. The self-adjoint differential operator identity and integration by parts giveThe boundary term vanishes for the same reasons as in part ii. The denominator is real and positive; the numerator is real and strictly positive because and . Hence the Rayleigh quotient isThe positivity uses a nondegenerate interval .
For real eigenfunctions , multiply their Sturm-Liouville problems crosswise and subtract. Integration givesAt , both eigenfunctions vanish, while at their bounded values and bounded first derivatives multiply a factor tending to zero. The right side is zero. Distinct eigenvalues therefore give the orthogonality of Sturm-Liouville eigenfunctionsFor complex eigenfunctions, replace by , in accordance with the weighted inner product.
Use separation of variables, , in the Laplace equation in polar coordinates. Dividing by givesSingle-valued -periodic angular factors have integer . For , they are , and the radial equation has solutions . The zero angular mode gives . These separated products give the requested solutions; arbitrary sums may use independent coefficients for each radial-angular combination.
Boundedness at the origin removes the logarithm and all negative radial powers. The boundary function is even, so its sine Fourier coefficients vanish. With the convention , its Fourier coefficients areThus the bounded interior harmonic extension isFor the series and its derivatives converge locally uniformly, so it is harmonic. It is a rotated and scaled instance of the harmonic measure of a semicircle in a disk. For example, summing the power series for the complex arctangent, or differentiating the following expression, gives the equivalent real formThis also proves boundedness directly.
At the two jumps, the boundary interpretation matters. At every continuity point the radial limit equals the prescribed value. At , the radial limit is , the midpoint of the two one-sided values. Consequently for there is no harmonic solution continuous on the closed disk with exactly the printed boundary values. The standard bounded Dirichlet problem imposes the trace away from the jumps, or almost everywhere; assigning zero separately at those two boundary points does not alter the interior solution.
For uniqueness let . Formally the divergence theorem applied to givesFor continuous zero boundary data, this immediately forces . With the actual discontinuous data, one should justify the two exceptional points rather than assume finite Dirichlet energy there. Let and choose a cutoff which is zero within of those points, one beyond , and linear in logarithmic distance between. Its gradient satisfies . Applying the divergence theorem to givesThe resulting energy tends to zero. Hence on every compact subset and is constant; its zero boundary trace on the open arcs makes it zero. This is the logarithmic cutoff proof of harmonic uniqueness with finitely many boundary exceptions.
For the exterior harmonic extension of disk boundary data, boundedness instead excludes and the logarithm. The same boundary coefficients giveThis is , using inversion in a circle. Its limit at infinity is . To see why that value is forced independently of this construction, average any bounded exterior harmonic function over a circle. The mean satisfies , hence is . Boundedness forces , and the boundary mean fixes . A constant limit at infinity must therefore be .
Finally suppose two bounded exterior solutions have this limit. Their difference tends to zero. Under planar inversion in a circle, it is bounded and harmonic near the origin, so the isolated point there is removable. Its local expansion gives , in the original exterior. Apply the preceding divergence theorem energy argument on , with logarithmic cutoffs at the two boundary jumps. After removing those cutoffs, the inner boundary term vanishes; the outer one is . Letting forces , and the zero limit gives . Thus the bounded exterior solution is unique as well.
The outgoing Green function for the three-dimensional Helmholtz equation satisfiesIts normalization follows by integrating over a small ball about : , so its outward derivative has flux . Apply Green's second identity in the variables:The terms cancel. Thus the surface integral equals for , and zero for outside the closed volume. Equivalently, remove a small source ball and evaluate its flux before taking its radius to zero. A source on the boundary would require a different limiting formula and is not part of this calculation.
For the upper half-space, take a half-ball of radius . Interpret the first far-field condition as , and the radiation limit in its usual direction-uniform sense, namely the Sommerfeld radiation conditionThis is the finite-bound interpretation of the PDF's first condition. For fixed and real ,Indeed , and its radial derivative is . On the large hemisphere the integrand can therefore be rewritten asIts area is , so its integral tends to zero. The planar integral, taken over expanding disks if needed, consequently equals for and zero for .
The outward unit normal vector on the bottom plane is . Denote this planar integral byFor reflect the source point to . On the plane,Adding and cancels the boundary values of and gives . Thus the Neumann representation for a radiating Helmholtz half-space isThe negative sign is consistent with using the upward derivative rather than the outward normal derivative. If that upward derivative is zero everywhere on the plane, the integral is zero. Hence throughout the upper half-space in the specified radiating class; taking a difference also gives uniqueness for prescribed Neumann boundary data.
Put and . The denominator of the complex rational function becomesThe quadratic formula gives its two zeros, hence the two poles:Their product is , so . To locate them one also needs to exclude the possibility of both lying on the unit circle. Here their moduli are explicit:Both are simple poles: takes the nonzero values and at them. In particular their residues are and .
For the real integral, use the change of variables . As runs from to , this traverses the unit circle once counterclockwise, andThus . Only is enclosed. The residue theorem, or Cauchy integral formula after subtracting its simple-pole part, givesThe real denominator is positive because . As an independent check, write ; a period shift reduces the answer to the existing reciprocal affine sine integral.
Differentiate the spatial Fourier transform under the integral, and integrate the second spatial derivative by parts twice. For sufficiently decaying temperature and first derivative, the boundary terms vanish:Hence the transformed heat equation is the ordinary differential equation
Solving the transformed ordinary differential equation with its initial condition gives . The Fourier inversion theorem therefore yieldsFor the Gaussian multiplier suppresses large spatial frequencies, which explains the smoothing produced by heat conduction.
The convolution theorem turns the product into a spatial convolution. Its kernel isComplete the square:After rescaling the variable, the supplied translated Gaussian integral givesThis is the heat-kernel solution for diffusivity one. Its kernel integrates to one, preserving the total temperature integral, and approaches a Dirac delta function as . Its variance is ; the factor is appropriate to , rather than the alternative convention with diffusivity .
For the Gaussian initial data for the heat equation, substitute the initial profile into the heat-kernel solution. Completing the square in givesThe remaining Gaussian integral yieldsThe centre stays at and the squared width grows linearly with time.
For the interval pulse, the convolution reduces to . Using and the error function givesThis is the translated and scaled heat equation with interval-indicator initial data. At its jump points the limits are ; away from them the initial data are recovered pointwise.
For fixed at late time, both error function arguments are small. Since ,The estimate is uniform for . Equivalently, on this fixed interval the Gaussian in the convolution is .
The spreading distance is more apparent on the growing spatial scale. For the Gaussian pulse the exponent is order one when . For the interval pulse, set with and fixed . Uniformly for bounded , its convolution givesThus both nonzero pulses spread over a distance , while their heights are and their total integrals remain constant. More quantitatively, the variances of their normalized profiles are and , respectively, confirming the same width law.
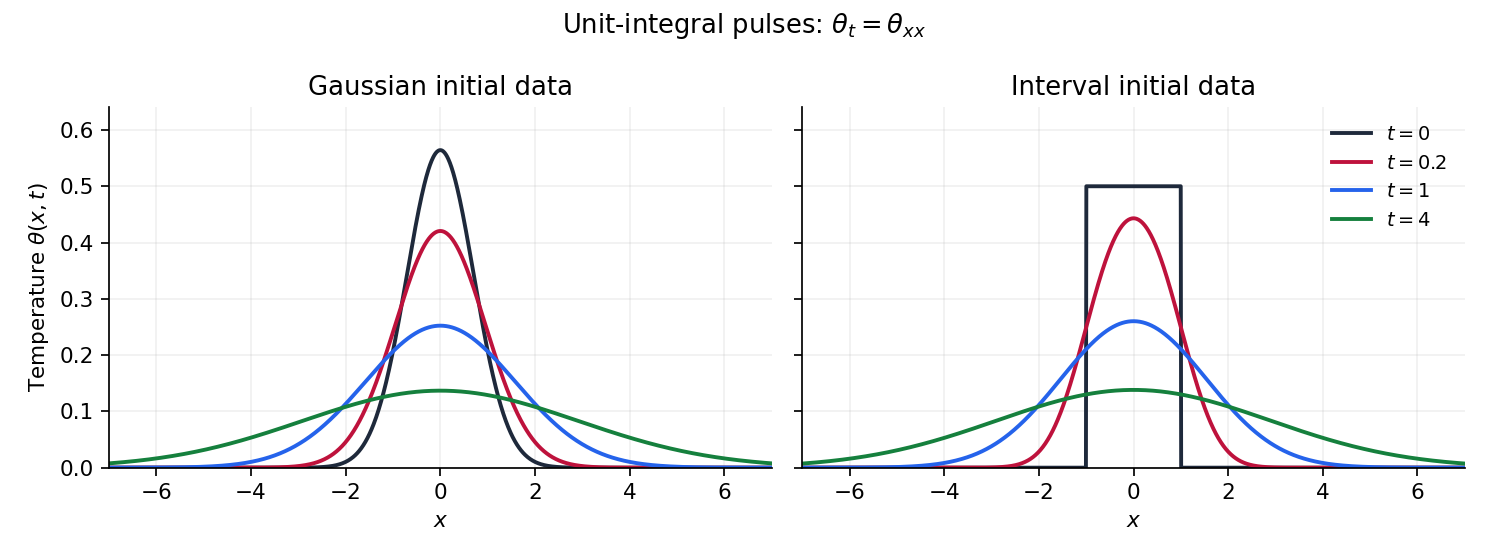
Gaussian and interval initial profiles broaden under the heat equation while conserving their integrals
. Details. 
In Cartesian coordinates a rank- tensor is an array whose components transform under a change of orthonormal axes by one rotation matrix factor per index:An isotropic tensor has unchanged components under every proper rotation. The Levi-Civita symbol obeysfor , proving rotation invariance of the Levi-Civita symbol. Under an orthogonal transformation of determinant its sign reverses; including such transformations requires the pseudotensor distinction. Here isotropy is with respect to proper rotations.
Contract the determinant identity with . Since , one obtainsEvery index on the right is contracted, so the tensor component transformation law leaves no free rotation factor: the determinant is a scalar. Equivalently, gives .
For the matrix inverse, defineThis is the cofactor matrix. To verify the inverse formula rather than just recognize it, contract with and use the determinant identity again:Here the contraction of two Levi-Civita symbols gives . Therefore and, when ,These are the Levi-Civita formulas for a three-dimensional determinant and inverse.
Now differentiate the cubic determinant formula with respect to the individual entry . The three differentiated factors give equal contributions: exchanging two paired indices changes the sign of both epsilon symbols, leaving their product unchanged. ThusSubstituting the inverse expression proves the entrywise derivative of the determinant:The cofactor version remains valid for singular matrices; only the inverse version requires invertibility.
For the time-dependent Jacobian matrix, the stated smooth expansion impliesApplying the chain rule and the entrywise determinant derivative gives Jacobi's formula near :At zero, , so . A Taylor expansion therefore yieldsThe Jacobian determinant measures local volume change, so this establishes volume preservation to first order. An arbitrary family specified only through its first-order expansion need not preserve volume exactly at higher orders.
Translate the generalized coordinates so that the equilibrium is at zero. Its potential gradient vanishes, and its quadratic potential energy is , where is the symmetric Hessian matrix. The Euler-Lagrange equations for small motion areA normal mode has fixed component ratios, , withThe angular frequency is its eigenfrequency. A zero mode instead admits a constant or linear time factor. For modes , symmetry givesHence mass-matrix orthogonality of normal modes isWithin a degenerate eigenspace, a basis can be chosen orthogonal in this positive weighted inner product.
For three masses connected pairwise, the exact energies areA fixed common translation preserves all differences and velocities. A fixed rigid rotation preserves their Euclidean norms. Thus both energies have these symmetries. Here the transformation is fixed in time; a moving reference frame would change the kinetic energy. Every equilateral configuration of side has zero spring extensions, hence zero force and minimum potential, proving that it is an equilibrium.
For the specified displacement coordinates, writeThe exact potential is . For an equilibrium edge vector and small perturbation ,Thus only each first-order extension is needed for the quadratic potential. These extensions, with an immaterial sign choice for the horizontal edge, areConsequently , with remainder . If , then . Expanding the squares givesThe small-oscillation mass and stiffness matrices are and the displayed . Hence
The two common translations give zero-mode vectorsAn infinitesimal counterclockwise rotation sends each equilibrium vertex to , where . Therefore a third zero-mode vector isEach vector makes all three vanish, so lies in the kernel of a linear map and therefore in the kernel of . The rows of are independent: the and entries first force the coefficients of its last two rows to vanish, then the first coefficient vanishes. Thus , and the rank-nullity theorem proves that these are exactly the three zero modes.
For radial motion takeso that to first order. The force on mass is , since . Newton's equation therefore gives . Equivalently . Hence the breathing normal mode hasAll three masses move radially outward together, then inward together, preserving the triangular shape. The remaining two normal modes of an equilateral spring triangle are shear deformations with squared frequency ; together with the breathing mode and three rigid zero modes they account for all six degrees of freedom.
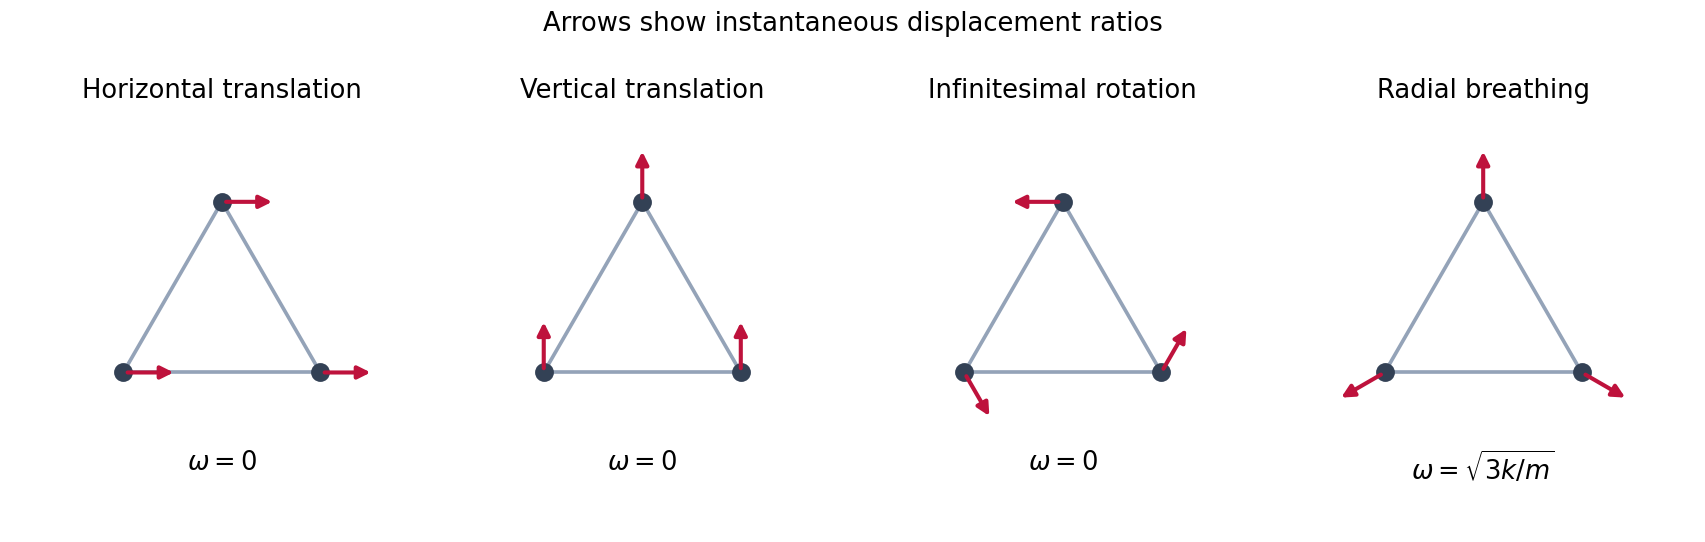
Two translations, an infinitesimal rotation and the radial breathing mode of the equilateral spring triangle
. Details. 
The order of a finite group is its number of elements. Lagrange's theorem states that for a subgroup ,so divides . In particular the order of a group element divides , because it is the order of its generated cyclic subgroup.
For , if some element has order four it generates the whole group, which is therefore the cyclic group . Otherwise every nonidentity element has order two. Choose two distinct ones and put . Cancellation shows , so is the remaining element. Since ,The other products follow: , , and . Thus the second possibility is the Klein four-group. The two groups are not isomorphic because only has an element of order four. This proves the order-four case of the classification of groups of order p squared.
A group homomorphism obeys . It maps identity to identity and inverses to inverses. Its group kernel contains and is closed under , so the subgroup test makes it a subgroup. For and ,Thus ; applying the same argument to gives equality. Hence is a normal subgroup.
Define by . If , then , giving , so this is well-defined. Coset multiplication shows it is a group homomorphism. Its kernel is just the identity coset, since means . It is therefore injective, and the assumed surjectivity of makes it surjective as well. This proves the first isomorphism theorem here:
In the quaternion group, the element commutes with each of , because an element commutes with its square. It then commutes with their negatives too, and with . The set is a subgroup because , and it is central, hence a normal subgroup.
The four quotient cosets are . They square to , and . Reversed products have the same coset: for example , while , so . The same calculation gives and . After signs are identified, these are precisely the products in the Klein four-group. DefineThis preserves all products, is surjective, and has kernel exactly . The first isomorphism theorem therefore givesThis is the quaternion group modulo its centre: the reverse-product relations also show that none of is central, so .
Two elements are conjugate group elements if for some . The conjugacy class of is . Conjugacy is an equivalence relation: it is reflexive using , symmetric by replacing with , and transitive becauseThus the classes partition the group: every element belongs to its own class, and any two classes that intersect are equal. This proves that every element belongs to exactly one class.
If is Abelian, then , so every class is a singleton. In general the elements whose classes are singletons are precisely those commuting with every group element. Thus the center of a group isIt contains . If , then commutes with every , since does and does. The subgroup test therefore proves that is a subgroup. Any two of its elements commute with each other, so it is an abelian subgroup.
For the square centred at the origin with vertices , putThe dihedral group consists of and , . Its eight actions and their matrices areThese exhaust the symmetries: the image of one vertex has four choices and the image of an adjacent vertex has two choices, determining the entire square. For an explicit pair of nonconjugate elements take and . Both have order two, but their determinants are and . A similarity transformation preserves the determinant, so and are not conjugate.
To find the centre, use . A rotation commutes with exactly when , so is even. No reflection commutes with , since while , and . Therefore
A group representation on a vector space is a group homomorphism : and . An invariant subspace obeys for every . A nonzero representation is irreducible if its only invariant subspaces are and . It is a faithful representation if it is injective, equivalently if its group kernel is . Its character is . For inequivalent complex irreducible representations of a finite group, character orthogonality is
Use right-to-left composition of permutations and assign the matrix labels consistently byThe resulting Cayley table, with row multiplying column, isConjugation relabels the entries of a cycle, preserving its length. Thus the conjugacy classes are
Define the permutation representation by , or . Applying it to a basis vector proves . The six assignments above produce exactly the listed matrices. They are distinct, and forces for every , so the representation is faithful.
Every permutation fixes , hence fixes every vector . Therefore is a one-dimensional invariant subspace carrying the trivial representation. Its orthogonal complement issince the inner product with is . Permuting coordinates preserves their sum, so this plane is invariant too. Every real vector has the unique decompositionThus the permutation representation is the direct sum of group representations on the line and the plane.
To find the eigenvectors of , note that . With , its three eigenvalues and eigenspaces areThe only real eigenvalue is one, whose eigenline is , so has no nonzero real eigenvector in . A proper nonzero real invariant subspace of that two-dimensional plane would be a line, giving such an eigenvector. Hence the plane representation is irreducible over .
For the later complex dimension-count theorem one should also establish irreducibility over ; real irreducibility alone would not imply it in general. In the complexified plane, the only candidate -invariant lines are its and eigenlines. But exchanges them:Neither is invariant under the whole group, proving complex irreducibility as well. The required decomposition is thereforewhere is the standard representation of the symmetric group for three letters. Its character is obtained by subtracting one from the number of fixed coordinates: on the three classes it is .
Finally, the sign representation gives a second one-dimensional irreducible, with value on and on the transpositions. These are exactly the two one-dimensional possibilities: if , a one-dimensional representation sends them to commuting nonzero scalars . The relations and imply and . Hence and , the trivial and sign choices. Together with the two-dimensional , these giveThe sum of squares of irreducible representation dimensions leaves room for no other irreducible. Thus there are exactly two one-dimensional and one two-dimensional complex irreducible representations.
Articles by others on the same topic
There are currently no matching articles.