A bilinear form is symmetric when for every pair of vectors . Equivalently, its matrix of a bilinear form in any basis is a symmetric matrix, since . Symmetry makes the relation reciprocal, giving the bilinear orthogonal complement a geometric interpretation.
Over the real numbers, set . The polarization identityrecovers the symmetric bilinear form from its quadratic form: expand and use symmetry to combine the two cross terms. For , take and . Then , , and , so . The same formula works whenever the characteristic is not two.[ref]
https://www.ma.imperial.ac.uk/~anskor/LINEAR.PDF. Skorobogatov, Linear Algebra and Matrices, p. 12: recovering a symmetric form from the diagonal
Three real diagonal matrices show how much variety symmetry allows. The identity matrix gives the positive-definite bilinear form . The matrix gives and is nondegenerate despite the isotropic vector . The matrix gives and is a degenerate bilinear form with radical of a bilinear form . Their level sets make the distinction visible: a circle, two branches of a hyperbola, and two parallel lines for .
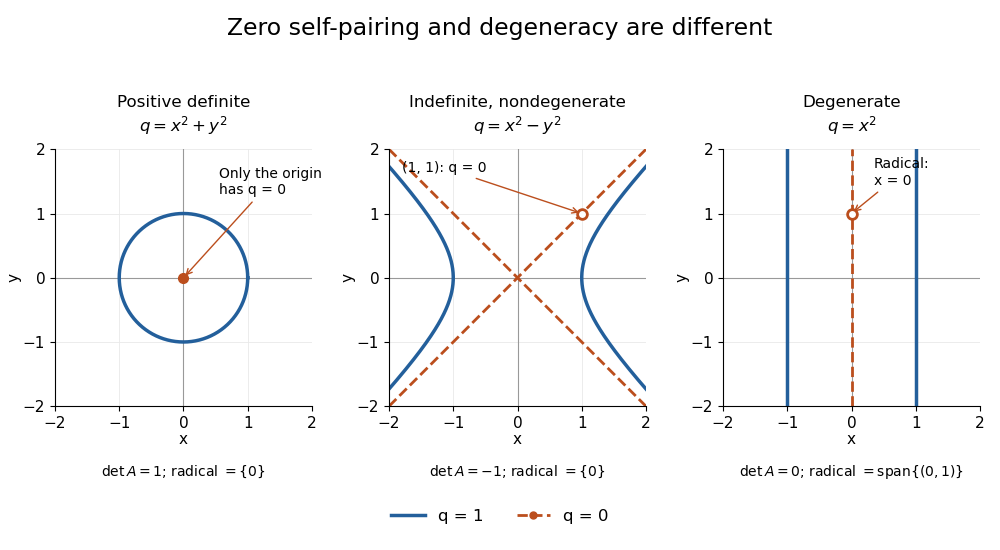
Unit and zero level sets distinguish positive, indefinite nondegenerate, and degenerate symmetric forms
. Details. The inertia of a bilinear form records the numbers of positive, negative, and zero directions after matrix congruence diagonalization. By Sylvester's law of inertia, these counts survive change of basis; the three examples have inertia of a bilinear form , , and . Historically, Sylvester stated this invariance in an 1852 paper on reducing real quadratic forms to sums of positive and negative squares. Ghys and Ranicki reproduce his statement and distinguish it from his subsequent 1853 proof.[ref]
https://arxiv.org/pdf/1512.09258. Étienne Ghys and Andrew Ranicki, Signatures in algebra, topology and dynamics, §1.2: Sylvester's statement and proof
A real symmetric bilinear form is positive-definite when for every nonzero vector. It defines an inner product and the associated norm . Symmetry is part of this definition: positive diagonal values by themselves do not imply symmetry.[ref]
The identity matrix gives and . For this is , giving norm . A weighted example, , gives norm : the first coordinate costs twice as much in length. Such inner products let geometry assign different weights to different directions.
Every positive-definite bilinear form is nondegenerate: a vector in its radical of a bilinear form has , so positivity forces . The converse fails, as shows. Even positivity of the associated quadratic form does not force a general bilinear form to be symmetric: has but and .
The complex Killing form is not positive-definite on the entire complex Cartan subalgebra; its restriction to the Euclidean subspace of a Cartan subalgebra is a real positive-definite form.
The strict positivity of a quadratic form on every nonzero vector. A real symmetric matrix has positive definiteness exactly when its associated quadratic form does, making it a positive-definite matrix. A Hermitian form is positive definite when its value on is real and strictly positive for every nonzero vector.
Think of a positive-definite quadratic form as an energy cost for a displacement: every direction costs something, and zero cost identifies the origin. For example, the real symmetric matrixis a positive-definite matrix because the two squares can vanish together only at . The mixed term couples the coordinates, but cannot overwhelm their positive contributions: and . The graph is a bowl, and its positive level sets are ellipses with axes along the eigenvectors, rather than along the original coordinates.
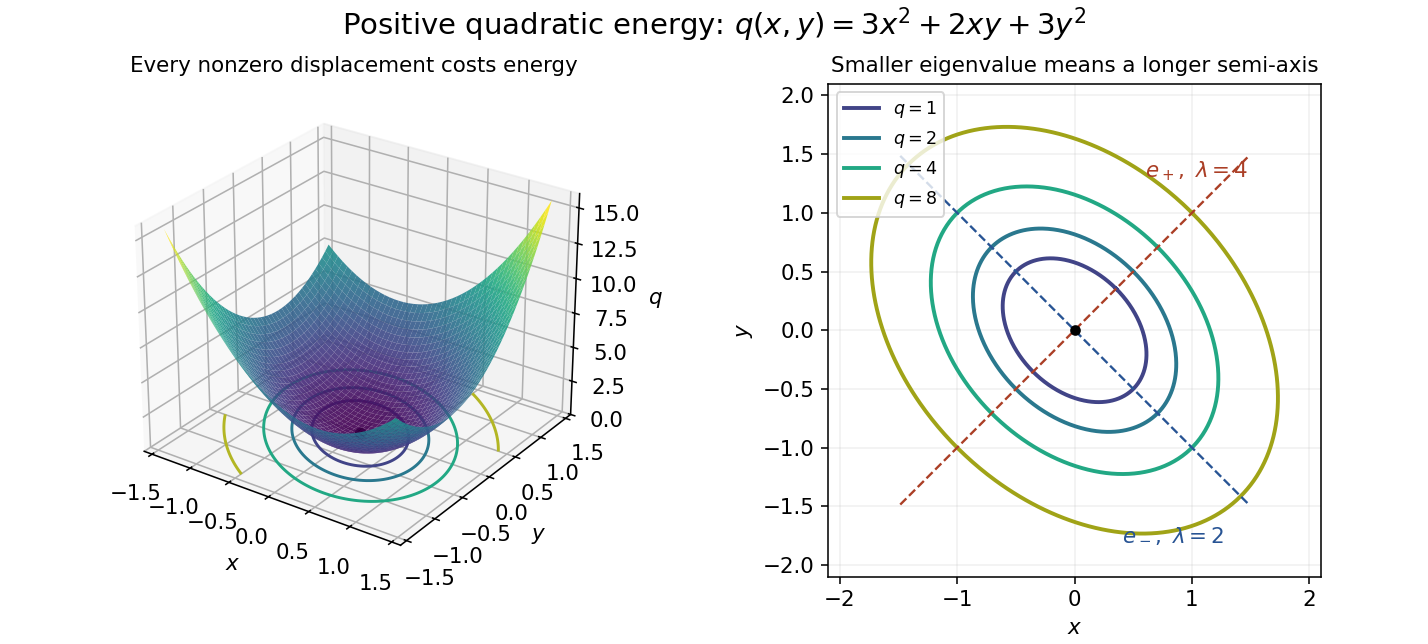
Positive quadratic energy bowl and elliptical level curves
. Details. The real and complex settings require different symmetry assumptions. For a real symmetric matrix use with ; for a complex Hermitian matrix use with , where is the conjugate transpose. The latter expression is real, so strict positivity is meaningful. A complex quadratic form such as has no such positivity: it vanishes at and takes negative real values at . A Hermitian form uses complex conjugation, which changes this example to .
For a real matrix without a symmetry hypothesis, its quadratic form depends only on its symmetric part of a matrix:Positive eigenvalues of alone do not establish positive definiteness of this quadratic form. For example, has both eigenvalues equal to , yet . The relevant test is positivity of the symmetric part of a matrix, not the spectrum of an arbitrary matrix.[ref]
For a real symmetric matrix , completing the square gives, when ,Thus is a positive-definite matrix exactly when and . For necessity, test first, then ; for sufficiency, the displayed two positive squares give the result. These are the first two leading principal minors in Sylvester's criterion. A positive determinant alone is insufficient: has determinant but is a negative-definite matrix.
The eigenvalues provide an equivalent test under the same real-symmetric hypothesis:The spectral theorem for real symmetric matrices supplies coordinates in an orthonormal basis in which . More generally, a complex Hermitian matrix has an orthonormal eigenbasis and , so it is a Hermitian positive-definite matrix exactly when every eigenvalue is positive. This is a short proof outline: test the eigenvectors for necessity, and sum the positive squared absolute values for sufficiency.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. Appendix A.5.2, pp. 646–647: symmetric eigenvalue decomposition and definiteness
For a real positive semidefinite matrix, the condition is instead for all vectors, equivalent here to , , and . If , the same completing the square proves this; if , nonnegativity forces and leaves with . Merely replacing the strict inequalities on the leading principal minors by nonstrict ones fails: has both leading principal minors zero yet gives . An indefinite quadratic form takes both positive and negative values; its real symmetric matrix has eigenvalues of both signs.
Vary the coupling in the opening example. The eigenvectors and form a fixed orthonormal eigenbasis, with eigenvalues and . Writing a vector as givesFor , both directions cost energy and is a positive-definite matrix. At , the quadratic form is : the entire line spanned by has zero energy, and is a singular positive semidefinite matrix. At , the flat line is instead spanned by . For , the quadratic form is an indefinite quadratic form; one direction lowers the energy without bound as its displacement grows. At , for instance, while .
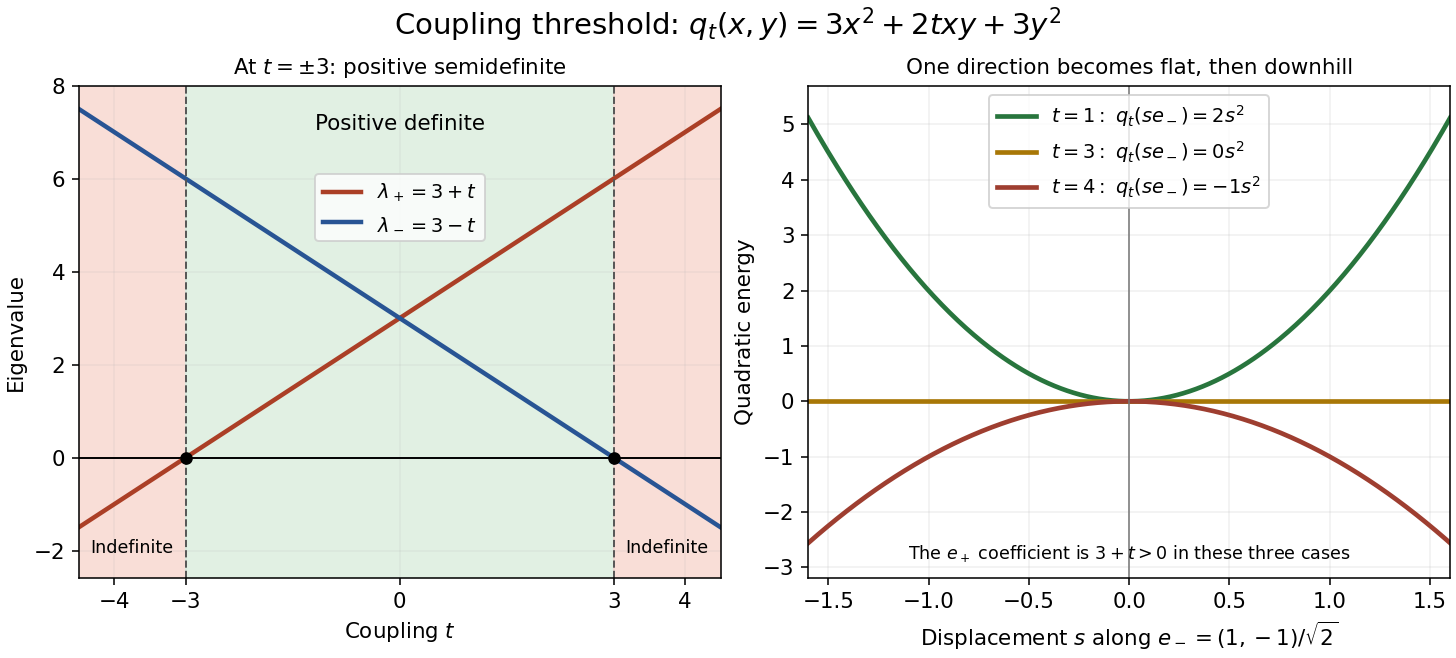
Eigenvalues and directional energies across the positivity threshold
. Details. The geometric transition is precise. For , is an ellipse. At , it consists of the two parallel lines , extending freely in the zero-energy direction. For , it is a hyperbola. The boundary case retains nonnegative energy but loses both the bounded positive level sets and the unique zero-energy vector.
For a real positive-definite matrix in finite dimension, write by the spectral theorem for real symmetric matrices. In the coordinates in an orthonormal basis , the positive level set becomesThis is an ellipsoid, with semi-major and semi-minor axes in two dimensions forming an ellipse; each semi-axis has length and direction given by the corresponding eigenvector. In the opening example, the shorter semi-axis is along , while the longer is along . A stiffer direction, meaning a larger eigenvalue, reaches the same energy at a smaller displacement. The ratio of longest to shortest semi-axis is , the square root of the spectral condition number of a positive-definite matrix.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.2.2, p. 30, equation (2.3): ellipsoids and semi-axis lengths; the book uses the inverse quadratic coefficient matrix
Strict positivity matters because givesHence a fixed positive level set cannot extend arbitrarily far. The Cholesky decomposition gives another view: , so the ellipsoid is the inverse image of a sphere under an invertible linear map. A singular positive semidefinite matrix has a nonzero kernel; adding a kernel vector preserves its quadratic form, so any nonempty positive level set is unbounded. These statements concern finite dimension; the positive definite symmetric operator entry explains why strict positivity alone need not give a uniform lower bound on an infinite-dimensional Hilbert space.
Let be a real positive-definite matrix and minimize the displayed quadratic function over all of . Its gradient is , so its only stationary point solves the linear system . The matrix is an invertible matrix, making this solution exist and be unique. Completing the square around that solution proves the stronger global statement:The quadratic function is strictly convex, and its level sets above the minimum are translated ellipsoids. Positivity therefore turns solving a linear system into locating the bottom of a bowl.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §3.1.4, Example 3.2, p. 71: a quadratic function is strictly convex exactly when its symmetric coefficient matrix is positive definite
For the opening matrix , take and . Then , , and . Every displacement raises the value by ; along the unit eigenvectors and the increases are respectively and for displacement or .
For a singular positive semidefinite matrix, a solution of is still a global minimizer, but adding any kernel vector gives another. If is outside the image of a linear map defined by , some kernel vector has , and is unbounded below. For an indefinite quadratic form, a negative eigenvalue gives a direction along which the quadratic term tends to regardless of . Thus a stationary point alone does not establish a minimum. The same energy-difference identity extends to the quadratic variational principle for a symmetric positive operator, with additional existence hypotheses in infinite dimension.
On real by matrices with , split into traceless symmetric matrices, skew-symmetric matrices and scalar matrices. These summands are orthogonal for the displayed symmetric bilinear form. The form is positive on the first summand, negative on the second and negative on the scalar identity direction. Its inertia of a bilinear form is , its rank is and its signature is . Indeed , and .
For a field of characteristic different from two, is the group of nonsingular symmetric bilinear forms modulo metabolic forms, with orthogonal sum as addition. A metabolic form has a half-dimensional totally isotropic subspace. Such a form is equivalent to a sum of hyperbolic planes, hence represents zero.



