A bilinear form takes two vectors in a vector space over a field and returns a scalar in . Its defining property is separate linearity: holding either input fixed gives a linear functional of the other. For scalars and vectors ,This is a scalar-valued bilinear map; the chosen field is part of the definition.[ref]
Separate linearity does not mean that is a linear map on the vector space with componentwise vector addition and scalar multiplication. Over the real numbers, , whereas a linear map on the pair would give . The simplest example is on the one-dimensional vector space : fixing gives , but doubling both and quadruples their product.
A bilinear form measures how two inputs interact. The dot product measures alignment; a symmetric bilinear form can describe a quadratic form; an alternating bilinear form can measure signed area. A nondegenerate bilinear form turns each vector into a unique linear functional and so connects geometry with the dual space. The same short definition therefore supports lengths, bilinear orthogonal complements, and symplectic vector spaces, depending on the additional properties imposed.
Over the complex numbers, a bilinear form is linear in both inputs without conjugating either scalar. A Hermitian form instead is a sesquilinear form and conjugates when its inputs are exchanged. For complex matrices, the adjoint used with Hermitian forms and matrix C-star algebras is the conjugate transpose, whereas a bilinear form uses the ordinary transpose . For example, has , while the Hermitian form has .[ref]
Bilinear Forms by Keith Conrad. §1: examples and the Hermitian distinction
On square matrices over a field, the trace of a product is a symmetric bilinear form. Pairing with the matrix unit reads off entry , proving nondegeneracy. For real matrices of size at least two it is not positive-definite: a planar rotation block squares to and has self-pairing . On real diagonalizable matrices its self-pairing is the sum of the squares of the real eigenvalues. This matrix pairing differs from the trace pairing of a field extension.
Choose an ordered basis of a finite-dimensional vector space. The matrix of a bilinear form records all pairings of basis vectors, with . Writing and , separate linearity giveswhere the last expression uses the coordinate vectors of . Conversely, every matrix defines a bilinear form by this formula.[ref]
For a concrete bilinear form on , takeThen but : a bilinear form need not be a symmetric bilinear form. For and , first compute , then . Reversing the inputs gives and .
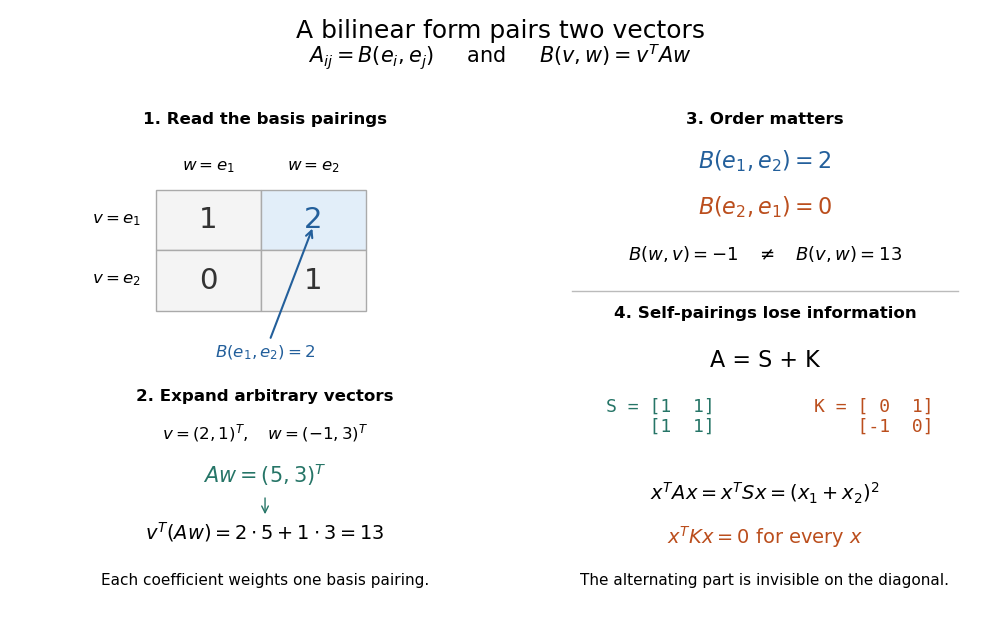
Under change of basis, let the columns of an invertible matrix be the new basis vectors in old coordinates. Thus and , soThis is matrix congruence, rather than the matrix similarity for an endomorphism. Both inputs have changed coordinates, which explains the two factors of . For the displayed and , direct multiplication gives ; its entry is .[ref]
Over a field whose characteristic is not two, a bilinear form has a unique decomposition into a symmetric bilinear form and an alternating bilinear form :Adding and subtracting the equations and both proves uniqueness and gives these formulas. In matrix notation, has matrix and has skew-symmetric matrix .[ref]
The diagonal values alone do not determine a general bilinear form, because for every vector. For the matrix of a bilinear form in the example above,Thus two different bilinear forms, represented by and its symmetric matrix part, have exactly the same quadratic form. To recover a bilinear form from its diagonal, one needs extra information such as the hypothesis that it is a symmetric bilinear form.
A bilinear form is symmetric when for every pair of vectors . Equivalently, its matrix of a bilinear form in any basis is a symmetric matrix, since . Symmetry makes the relation reciprocal, giving the bilinear orthogonal complement a geometric interpretation.
Over the real numbers, set . The polarization identityrecovers the symmetric bilinear form from its quadratic form: expand and use symmetry to combine the two cross terms. For , take and . Then , , and , so . The same formula works whenever the characteristic is not two.[ref]
https://www.ma.imperial.ac.uk/~anskor/LINEAR.PDF. Skorobogatov, Linear Algebra and Matrices, p. 12: recovering a symmetric form from the diagonal
Three real diagonal matrices show how much variety symmetry allows. The identity matrix gives the positive-definite bilinear form . The matrix gives and is nondegenerate despite the isotropic vector . The matrix gives and is a degenerate bilinear form with radical of a bilinear form . Their level sets make the distinction visible: a circle, two branches of a hyperbola, and two parallel lines for .
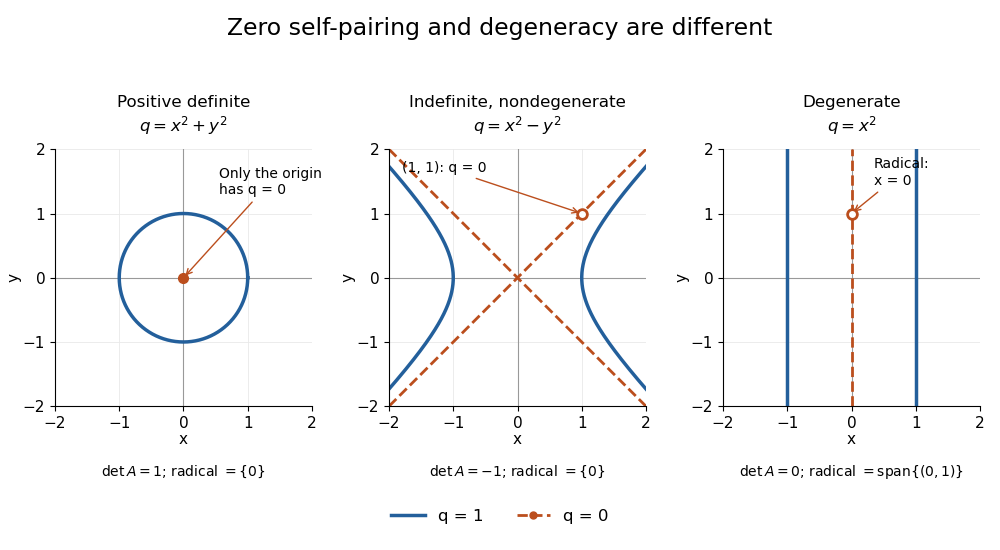
Unit and zero level sets distinguish positive, indefinite nondegenerate, and degenerate symmetric forms
. Details. The inertia of a bilinear form records the numbers of positive, negative, and zero directions after matrix congruence diagonalization. By Sylvester's law of inertia, these counts survive change of basis; the three examples have inertia of a bilinear form , , and . Historically, Sylvester stated this invariance in an 1852 paper on reducing real quadratic forms to sums of positive and negative squares. Ghys and Ranicki reproduce his statement and distinguish it from his subsequent 1853 proof.[ref]
https://arxiv.org/pdf/1512.09258. Étienne Ghys and Andrew Ranicki, Signatures in algebra, topology and dynamics, §1.2: Sylvester's statement and proof
A real symmetric bilinear form is positive-definite when for every nonzero vector. It defines an inner product and the associated norm . Symmetry is part of this definition: positive diagonal values by themselves do not imply symmetry.[ref]
The identity matrix gives and . For this is , giving norm . A weighted example, , gives norm : the first coordinate costs twice as much in length. Such inner products let geometry assign different weights to different directions.
Every positive-definite bilinear form is nondegenerate: a vector in its radical of a bilinear form has , so positivity forces . The converse fails, as shows. Even positivity of the associated quadratic form does not force a general bilinear form to be symmetric: has but and .
The complex Killing form is not positive-definite on the entire complex Cartan subalgebra; its restriction to the Euclidean subspace of a Cartan subalgebra is a real positive-definite form.
The strict positivity of a quadratic form on every nonzero vector. A real symmetric matrix has positive definiteness exactly when its associated quadratic form does, making it a positive-definite matrix. A Hermitian form is positive definite when its value on is real and strictly positive for every nonzero vector.
Think of a positive-definite quadratic form as an energy cost for a displacement: every direction costs something, and zero cost identifies the origin. For example, the real symmetric matrixis a positive-definite matrix because the two squares can vanish together only at . The mixed term couples the coordinates, but cannot overwhelm their positive contributions: and . The graph is a bowl, and its positive level sets are ellipses with axes along the eigenvectors, rather than along the original coordinates.
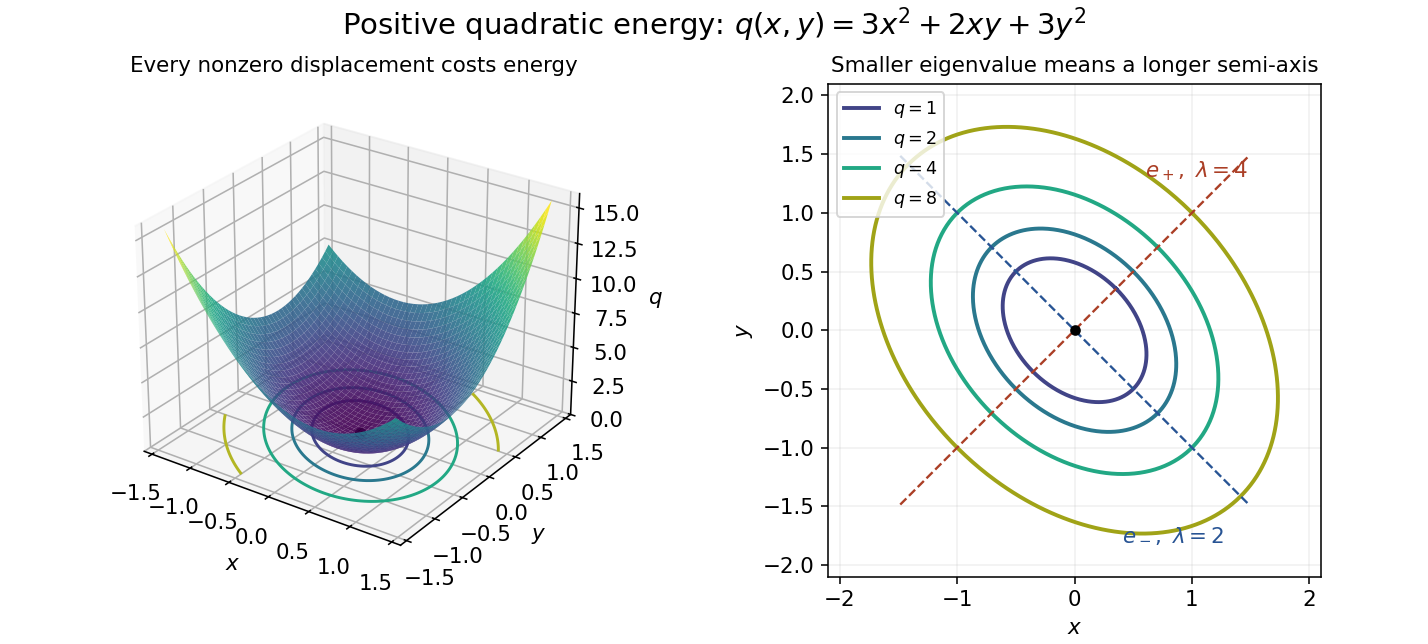
Positive quadratic energy bowl and elliptical level curves
. Details. The real and complex settings require different symmetry assumptions. For a real symmetric matrix use with ; for a complex Hermitian matrix use with , where is the conjugate transpose. The latter expression is real, so strict positivity is meaningful. A complex quadratic form such as has no such positivity: it vanishes at and takes negative real values at . A Hermitian form uses complex conjugation, which changes this example to .
For a real matrix without a symmetry hypothesis, its quadratic form depends only on its symmetric part of a matrix:Positive eigenvalues of alone do not establish positive definiteness of this quadratic form. For example, has both eigenvalues equal to , yet . The relevant test is positivity of the symmetric part of a matrix, not the spectrum of an arbitrary matrix.[ref]
For a real symmetric matrix , completing the square gives, when ,Thus is a positive-definite matrix exactly when and . For necessity, test first, then ; for sufficiency, the displayed two positive squares give the result. These are the first two leading principal minors in Sylvester's criterion. A positive determinant alone is insufficient: has determinant but is a negative-definite matrix.
The eigenvalues provide an equivalent test under the same real-symmetric hypothesis:The spectral theorem for real symmetric matrices supplies coordinates in an orthonormal basis in which . More generally, a complex Hermitian matrix has an orthonormal eigenbasis and , so it is a Hermitian positive-definite matrix exactly when every eigenvalue is positive. This is a short proof outline: test the eigenvectors for necessity, and sum the positive squared absolute values for sufficiency.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. Appendix A.5.2, pp. 646–647: symmetric eigenvalue decomposition and definiteness
For a real positive semidefinite matrix, the condition is instead for all vectors, equivalent here to , , and . If , the same completing the square proves this; if , nonnegativity forces and leaves with . Merely replacing the strict inequalities on the leading principal minors by nonstrict ones fails: has both leading principal minors zero yet gives . An indefinite quadratic form takes both positive and negative values; its real symmetric matrix has eigenvalues of both signs.
Vary the coupling in the opening example. The eigenvectors and form a fixed orthonormal eigenbasis, with eigenvalues and . Writing a vector as givesFor , both directions cost energy and is a positive-definite matrix. At , the quadratic form is : the entire line spanned by has zero energy, and is a singular positive semidefinite matrix. At , the flat line is instead spanned by . For , the quadratic form is an indefinite quadratic form; one direction lowers the energy without bound as its displacement grows. At , for instance, while .
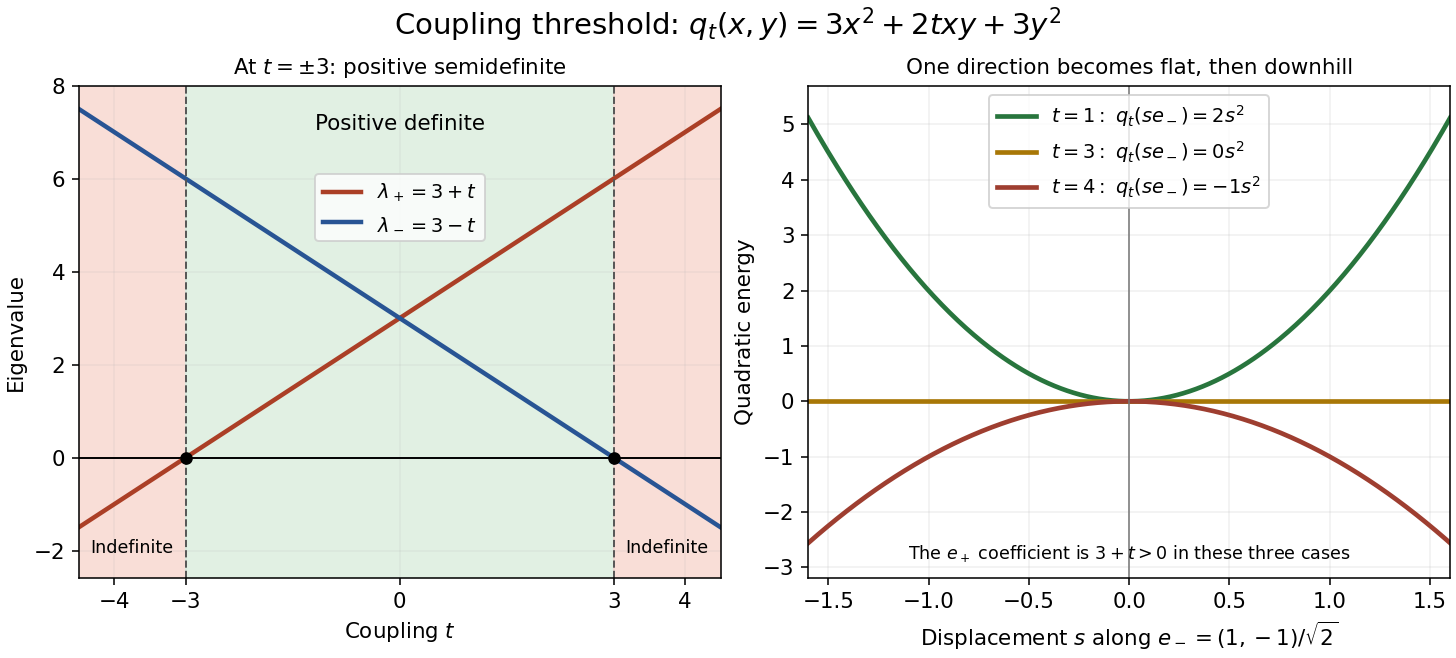
Eigenvalues and directional energies across the positivity threshold
. Details. The geometric transition is precise. For , is an ellipse. At , it consists of the two parallel lines , extending freely in the zero-energy direction. For , it is a hyperbola. The boundary case retains nonnegative energy but loses both the bounded positive level sets and the unique zero-energy vector.
For a real positive-definite matrix in finite dimension, write by the spectral theorem for real symmetric matrices. In the coordinates in an orthonormal basis , the positive level set becomesThis is an ellipsoid, with semi-major and semi-minor axes in two dimensions forming an ellipse; each semi-axis has length and direction given by the corresponding eigenvector. In the opening example, the shorter semi-axis is along , while the longer is along . A stiffer direction, meaning a larger eigenvalue, reaches the same energy at a smaller displacement. The ratio of longest to shortest semi-axis is , the square root of the spectral condition number of a positive-definite matrix.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §2.2.2, p. 30, equation (2.3): ellipsoids and semi-axis lengths; the book uses the inverse quadratic coefficient matrix
Strict positivity matters because givesHence a fixed positive level set cannot extend arbitrarily far. The Cholesky decomposition gives another view: , so the ellipsoid is the inverse image of a sphere under an invertible linear map. A singular positive semidefinite matrix has a nonzero kernel; adding a kernel vector preserves its quadratic form, so any nonempty positive level set is unbounded. These statements concern finite dimension; the positive definite symmetric operator entry explains why strict positivity alone need not give a uniform lower bound on an infinite-dimensional Hilbert space.
Let be a real positive-definite matrix and minimize the displayed quadratic function over all of . Its gradient is , so its only stationary point solves the linear system . The matrix is an invertible matrix, making this solution exist and be unique. Completing the square around that solution proves the stronger global statement:The quadratic function is strictly convex, and its level sets above the minimum are translated ellipsoids. Positivity therefore turns solving a linear system into locating the bottom of a bowl.[ref]
Convex Optimization by Stephen Boyd and Lieven Vandenberghe. §3.1.4, Example 3.2, p. 71: a quadratic function is strictly convex exactly when its symmetric coefficient matrix is positive definite
For the opening matrix , take and . Then , , and . Every displacement raises the value by ; along the unit eigenvectors and the increases are respectively and for displacement or .
For a singular positive semidefinite matrix, a solution of is still a global minimizer, but adding any kernel vector gives another. If is outside the image of a linear map defined by , some kernel vector has , and is unbounded below. For an indefinite quadratic form, a negative eigenvalue gives a direction along which the quadratic term tends to regardless of . Thus a stationary point alone does not establish a minimum. The same energy-difference identity extends to the quadratic variational principle for a symmetric positive operator, with additional existence hypotheses in infinite dimension.
On real by matrices with , split into traceless symmetric matrices, skew-symmetric matrices and scalar matrices. These summands are orthogonal for the displayed symmetric bilinear form. The form is positive on the first summand, negative on the second and negative on the scalar identity direction. Its inertia of a bilinear form is , its rank is and its signature is . Indeed , and .
For a field of characteristic different from two, is the group of nonsingular symmetric bilinear forms modulo metabolic forms, with orthogonal sum as addition. A metabolic form has a half-dimensional totally isotropic subspace. Such a form is equivalent to a sum of hyperbolic planes, hence represents zero.
A bilinear form is nondegenerate when its left radical and right radical are both zero: every nonzero vector can be detected by some pairing, whichever input slot it occupies. On a finite-dimensional vector space, either condition implies the other, and the following tests are equivalent:Here is the matrix of a bilinear form, and is the dual space. The linear map has matrix in the chosen basis and its dual basis, so its kernel is the right radical. The map has matrix . An invertible matrix has zero kernel on both sides, proving the finite-dimensional equivalence. In infinite dimensions, zero left radical and right radical imply these maps are injective, but do not generally make them surjective.[ref]
For the real symmetric bilinear form , the determinant is . Its isotropic vector has zero self-pairing but pairs to with , so it is detected. The alternating bilinear form with matrix has determinant and detects every nonzero vector even though all self-pairings vanish. Neither zero self-pairings nor the absence of positive definiteness implies degeneracy.
Nondegeneracy is useful because it turns a linear functional into a unique vector. For , the linear functional is ; solving for that representing vector amounts to solving an invertible system of linear equations. The analogous identification underlies bilinear orthogonal complements and the dual isomorphisms induced by a nondegenerate pairing.
A bilinear form with zero left and right radicals induces injective linear maps and . Finite dimensions force , so both maps are isomorphisms. For any other bilinear form , composing its maps to the dual spaces with these inverse isomorphisms gives unique endomorphisms with . In bases with invertible pairing matrix and coefficient matrix , and .
A symplectic vector space is a vector space equipped with a nondegenerate bilinear form that is an alternating bilinear form: for every vector . This implies . When the characteristic is two, that latter equation alone does not imply the alternating condition. A symplectic vector space of finite dimension has even dimension: splitting off a hyperbolic pair leaves a smaller nondegenerate bilinear form, and repeating gives a decomposition into two-dimensional planes.
For a finite-dimensional symplectic vector space, the symplectic adjoint of a linear map is the unique linear map satisfying the displayed identity. Existence and uniqueness follow because the nondegenerate bilinear form identifies the vector space with its dual space. If has matrix in a basis, then . Thus and , and membership in the symplectic Lie algebra is equivalent to . This operation is linear over the ground field; it does not involve complex conjugation. It preserves diagonalizability and the property of being a nilpotent linear map, since it is conjugate to matrix transpose.
A linear map is symplectic when it pulls back the target symplectic form to the source form. Nondegenerate bilinear form makes such a map injective. In equal finite dimensions it is an isomorphism. The automorphisms form the symplectic group and preserve the symplectic orientation on the ambient space and on every symplectic subspace.
A subspace of a symplectic vector space is symplectic if the restricted symplectic form is nondegenerate. It has a symplectic orthogonal complement and the ambient space is the direct sum of those two subspaces.
Let be a symplectic orthogonal complement splitting into two symplectic subspaces of dimension two. In symplectic bases, the graph of a function pulls back the symplectic form to . It is a symplectic subspace exactly when . Its symplectic orientation agrees with the orientation transported from exactly when . When , the transverse oriented pair has negative intersection sign, whereas two distinct complex lines in a compatible complex two-space have positive intersection sign.
If preserves a nondegenerate bilinear form that is alternating and satisfies on a finite-dimensional vector space over a field of characteristic different from two, thenThe two eigenspaces are orthogonal for , since . Each restricted form is nondegenerate: a vector annihilating its own eigenspace also annihilates the other and hence all of . Both dimensions are even, say and . Consequently as an integer obtained from the eigenspace dimensions. Over the real numbers this gives the congruence .
The symplectic orthogonal complement of a subspace is . The nondegenerate bilinear form gives . An isotropic subspace of a symplectic vector space satisfies ; a Lagrangian subspace satisfies equality.
A subspace of a symplectic vector space is isotropic when . It has at most half the dimension of ; equality makes it a Lagrangian subspace. This use of isotropic concerns an alternating bilinear form, rather than an isotropic quadratic form.
A symplectic basis organizes a nondegenerate alternating bilinear form into independent pairs. Let be a finite-dimensional vector space over a field , with a nondegenerate bilinear form satisfying for every vector . Its dimension is even, say , and a symplectic basis is an ordered basis such thatHere is the Kronecker delta. Each is a hyperbolic pair; different pairs have zero mutual pairing. These conventions apply in every characteristic. In characteristic two, , but the condition is still essential: a symmetric bilinear form need not be an alternating bilinear form. The existence theorem and the characteristic caveat are given in Bilinear Forms by Keith Conrad (Keith Conrad, Bilinear Forms, §1, Theorem 1.6; §5, Theorems 5.1 and 5.4 and Definition 5.3).
The benefit is a common coordinate language for every symplectic vector space of the same finite dimension over the same field. The span of all , and separately of all , is a Lagrangian subspace; each paired span is a symplectic subspace. In Hamiltonian mechanics, the corresponding pairing of position and momentum coordinates describes phase space and canonical transformations. On a symplectic manifold, a symplectic basis describes one tangent space; Darboux coordinates additionally describe a whole local neighborhood.[ref]
Symplectic Geometry. §1.1, pp. 82–83: paired bases and Lagrangian spans; §1.5, pp. 90–91: Darboux coordinates
Write vectors in a symplectic basis as and . Their coordinate vectors and the matrix of a bilinear form areHere is the identity matrix, and denotes transpose. The ordering matters: interleaving the basis as instead gives a block diagonal matrix with blocks . Some conventions reverse every , giving instead. Always check the displayed pairing convention.[ref]
Symplectic Geometry. §1.1, p. 83: e-then-f basis and its block matrix; the coordinate formula follows by bilinearity
Over the real numbers, each summand is the signed area of a parallelogram in the coordinate plane. For and , the two signed areas are and , so although the vectors are linearly independent. The cancellation concerns the symplectic form; it does not assert that their dot product vanishes. Over a general field, the same determinant formula is algebraic, without a signed geometric interpretation.
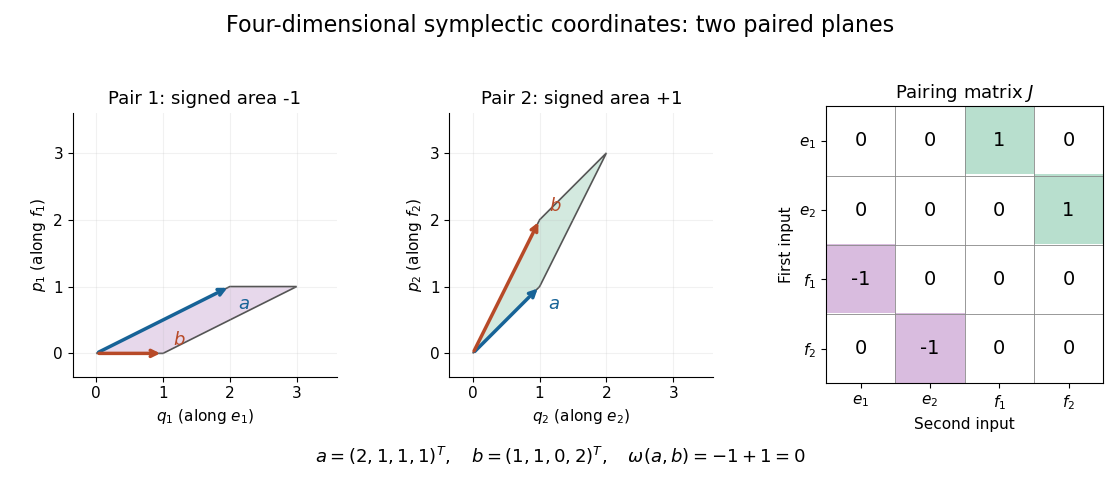
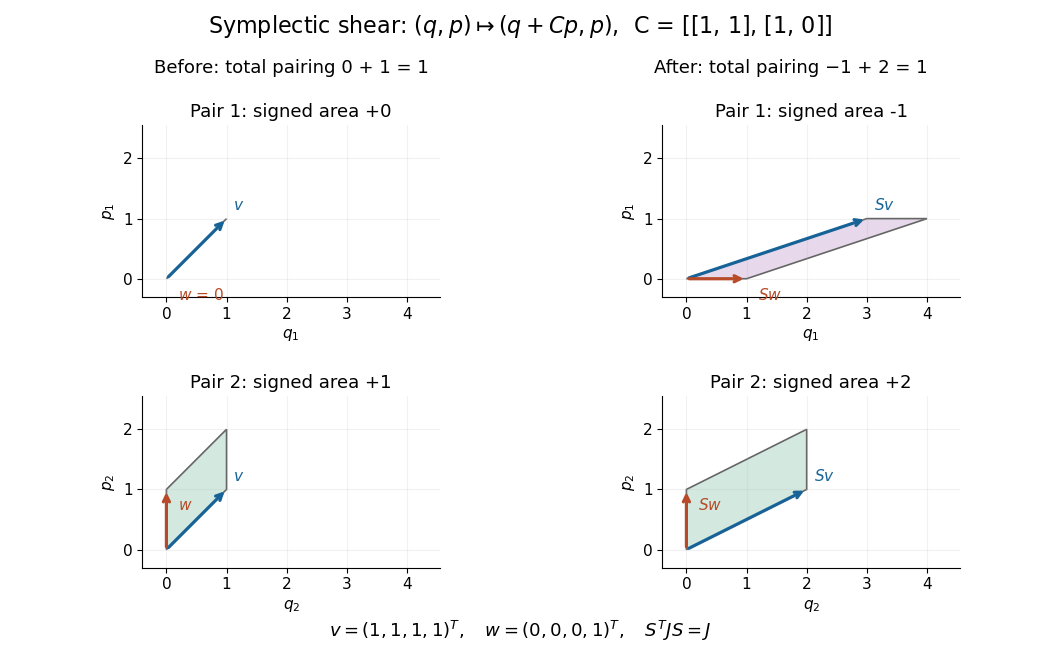
On , use the standard basis and the alternating bilinear form with matrix above for . A second symplectic basis isFor instance, , while and the cross-pairings vanish. The change of basis matrix, whose columns are these new basis vectors in , isThe symmetric matrix makes , so is a symplectic matrix. Explicitly, multiplying the blocks gives a lower-right block ; the other blocks agree with . For a fixed vector, change of basis means , henceTheir symplectic form gives in , and in . The separate coordinate-plane contributions change, but their sum does not.
The same matrix also represents an active symplectic linear map: keeping one basis fixed, it sends to . The following diagram shows this active interpretation over the real numbers. Its preserved total pairing is precisely the test used for linear canonical transformations.
Construct a symplectic basis two vectors at a time. Choose ; the nondegenerate bilinear form supplies with , and set . For any vector , remove its paired components byThen . Thus, for , the symplectic orthogonal complement gives a direct sum ; its restricted bilinear form remains nondegenerate. Repeat there until no vectors remain, then put all before all . This proves even dimension and existence together. Only the nonzero pairing is divided out, so the construction also works in characteristic two. The pair-splitting argument is described in Bilinear Forms by Keith Conrad (Keith Conrad, Bilinear Forms, §5, proof of Theorem 5.1 and Theorem 5.4).
If is a nondegenerate bilinear form on a finite-dimensional vector space and is any bilinear form, there is a unique linear map such thatThe right radical of is .
A real bilinear form on a normed vector space is coercive when there is one constant such thatThe lower bound uniformly controls every direction in the chosen norm. Unlike the upper bound defining a bounded bilinear form, it forces positive diagonal values at every nonzero vector. No symmetry is assumed. For complex Hilbert spaces, the usual analogue uses a sesquilinear form and ; it is not the same assertion for a complex bilinear form.
A concrete bounded and coercive example on , with the Euclidean norm, isIts quadratic form isThe best lower constant is , attained at . Nevertheless, and , so coercivity does not imply a symmetric bilinear form. The symmetric part of a matrix determines , while the skew-symmetric matrix part changes mixed pairings without changing . This is the symmetric and alternating parts of a bilinear form decomposition.[ref]
For the upper constant, direct multiplication gives . Its eigenvalues are , so the optimal upper constant, the spectral norm, is . The two constants answer different questions: how large a mixed pairing can be, and how small a self-pairing can be relative to squared norm.
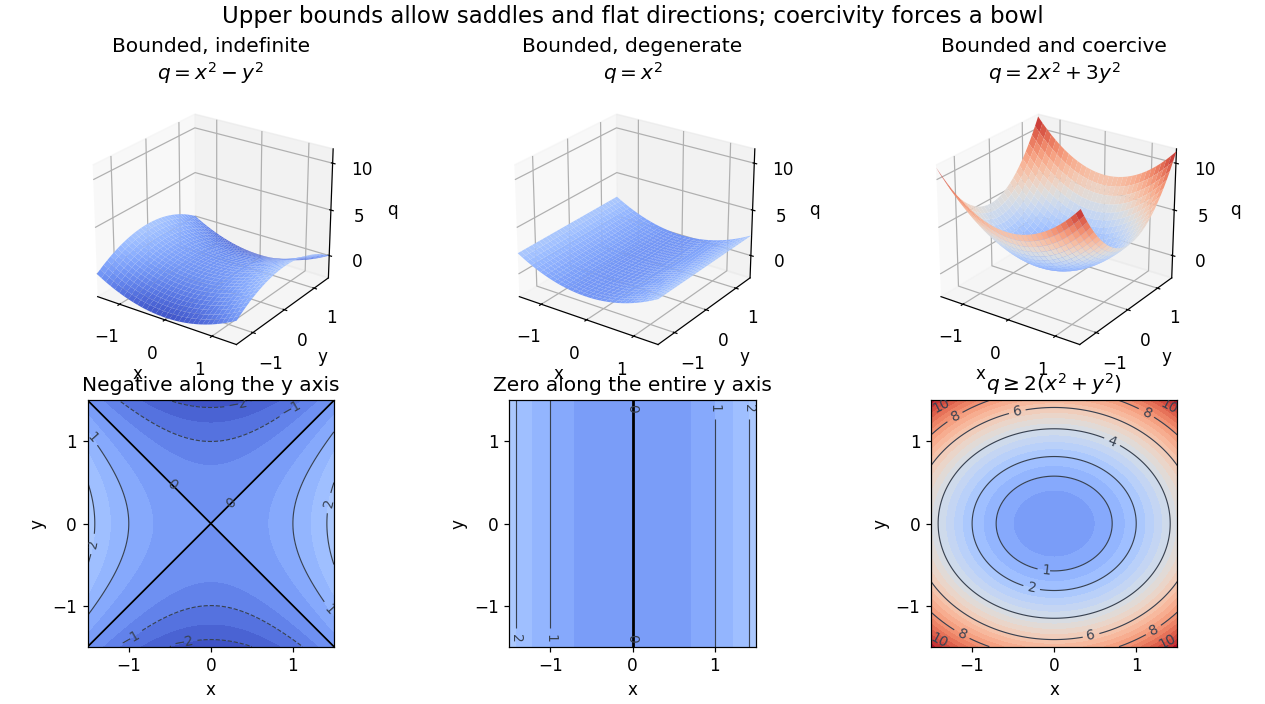
Bounded saddle and flat-direction quadratic forms contrasted with a uniformly coercive bowl
. Details. The plotted quadratic forms show the mechanism: descends in one direction, leaves one direction uncontrolled, and controls both. These are self-pairings; their level sets cannot reveal the skew-symmetric matrix part. Calling a quadratic energy here refers to this diagnostic quantity, not to a claim that a nonsymmetric equation comes from minimizing an energy functional.
On a real finite-dimensional vector space with any norm, strict positivity for every nonzero does imply coercivity. Indeed the quadratic form is continuous, and its positive minimum on the compact unit sphere supplies . If is also a symmetric bilinear form, this is positive definiteness. For general , it is the symmetric and alternating parts of a bilinear form decomposition that isolates the positive part. Switching between equivalent norms preserves coercivity, but usually changes its constant.
The infinite-dimensional vector space distinction is explicit on the real l2 sequence space:The Cauchy-Schwarz inequality gives boundedness with , and for every nonzero vector. But with , so no positive works. On the span of , the best lower constant is : each finite restriction is coercive, but the control disappears as grows. Strict positivity is therefore weaker than a uniform lower bound.
The practical payoff is a stability estimate for a weak formulation. Assume is a real Hilbert space, is both a bounded bilinear form and a coercive bilinear form, and the load is a bounded linear functional. The Lax-Milgram theorem gives a unique satisfying for all , including nonsymmetric .[ref]
Introduction to Finite Element Methods by Christian Clason. §2.2, Theorem 2.7, pp. 20–21, equation (2.9): hypotheses, unique solvability and load bound
The dual norm measures load size. Testing with gives the short energy estimateFor the bound holds directly; otherwise divide by . Subtracting the equations for two loads and using the same argument gives . Thus a positive lower constant limits the response to load errors. The upper bound and completeness of the Hilbert space enter the existence theorem; the estimate itself uses the lower bound and the load's dual norm.For the displayed matrix , take . Then for every means , not , with this ordering of the bilinear form. Since ,For , the exact response is and . For , it is , with norm . The actual maximal amplification is the operator norm : the coercivity estimate is valid but need not be sharp for a nonsymmetric bilinear form.
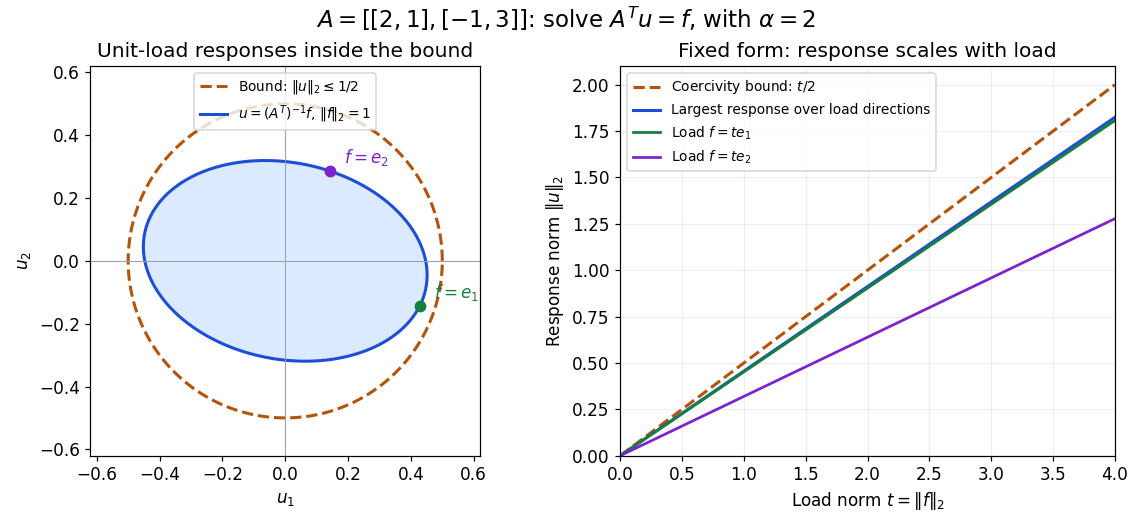
Solutions for unit loads lie inside the coercivity bound, and response grows at most linearly with load norm
. Details. Consider on real functions with , where . The pointwise estimate in the Endpoint Poincaré inequality gives with . If , then . Thus the form is a coercive bilinear form even though the potential can change sign. For on , , yielding the explicit constant .
A bilinear form is degenerate if some nonzero vector pairs to zero with every vector on at least one side. For a symmetric bilinear form or an alternating bilinear form, this says its radical of a bilinear form contains a nonzero vector. On a finite-dimensional vector space, it is equivalent to a singular matrix of a bilinear form, or .
For , . The nonzero vector is invisible to every pairing, and changing never changes . The quadratic form therefore has two parallel lines as its unit level set. This is a lost direction, a stronger condition than being an isotropic vector: with , but .
For a symmetric bilinear form or an alternating bilinear form, the radical is the linear subspaceThese vectors are invisible to all pairings, and the bilinear form is nondegenerate exactly when this linear subspace is . In coordinates, for both kinds of bilinear form, since or . Thus has radical of a bilinear form .
Passing to the quotient vector space removes precisely the invisible directions. The rule is well-defined because adding a vector in the radical of a bilinear form to either input changes no pairing, and the resulting bilinear form is nondegenerate. For , this quotient vector space retains just the direction and its form is ordinary multiplication.[ref]
https://www.math.ucla.edu/~rse/oldbook/Kniga.pdf. Elman, Karpenko and Merkurjev, The Algebraic and Geometric Theory of Quadratic Forms, §1: radical and nondegenerate quotient
For a general bilinear form, distinguish the left radical of a bilinear form from the right radical of a bilinear form; they can be different linear subspaces even though their dimensions agree in finite dimensions.
The left radical is . If is the matrix of a bilinear form, this condition is , so its coordinate vectors form . For , the bilinear form has left radical .
The right radical is . If is the matrix of a bilinear form, this condition is . For from the left radical example, the right radical is . The left radical and right radical differ here because the bilinear form is neither symmetric nor alternating. For a symmetric bilinear form or an alternating bilinear form, reversing a zero pairing preserves zero and the two linear subspaces coincide.
A bilinear form on a real normed vector space is bounded when one constant satisfiesThis is an upper bound on the magnitude of every pairing. It says nothing about the sign of and does not require a symmetric bilinear form. The chosen norm is part of the hypothesis. Boundedness is equivalent to joint continuity, as shown by the boundedness criterion for a bilinear form.[ref]
For example, on with the Euclidean norm, the bilinear formsboth satisfy the upper bound with , by the Cauchy-Schwarz inequality. Yet their quadratic forms are and : the former takes negative values and the latter vanishes at the nonzero vector . Thus neither is a coercive bilinear form. The latter is also a degenerate bilinear form, whereas is nondegenerate. Boundedness controls size, not positivity or loss of directions.
Every bilinear form on a real or complex finite-dimensional vector space equipped with any norm is bounded. In coordinates, write using its matrix of a bilinear form. The Cauchy-Schwarz inequality gives , with the spectral norm; finite-dimensional equivalence of norms transfers this to the chosen norm. The conclusion concerns each fixed norm and fixed bilinear form: it does not supply a single constant for an arbitrary family of matrices or changing dimensions.
On an infinite-dimensional vector space, the upper bound is an additional condition. Equip the finitely supported sequences with the norm inherited from the l2 sequence space and setEach pairing is a finite sum, so this is a well-defined bilinear form. For the basis vector , however, and ; no finite works. It is even a coercive bilinear form with , since . Consequently coercivity alone does not imply boundedness on a normed vector space. This example uses , which is not a Hilbert space; it does not define this pairing on all of the l2 sequence space.
A bounded bilinear form defines a bounded linear operator by , where is the continuous dual space. Its operator norm is the smallest admissible :This converts an upper bound for pairings into an upper bound for a linear map taking an unknown vector to a linear functional.
Let be a bounded real measurable coefficient on an open set. Nonnegativity of clearly makes its gradient form nonnegative. Conversely, if on a set of positive measure, choose an interior Lebesgue point where . For a nonconstant compactly supported smooth function , set . Change variables and use the Lebesgue differentiation theorem to obtain , a contradiction. Thus the linear operator represented by is monotone exactly when almost everywhere.
For a finite real scalar matrix and unit vectors in a real Hilbert space, , with a universal constant. One valid bound is . Expand using odd tensor powers with coefficient magnitudes summing to , then apply the Gaussian sign identity . Taking converts the expectation back to the original inner product. Complex scalars admit a universal bound twice this real bound by separating real and imaginary parts.
Every bounded linear operator into a Hilbert space is an absolutely summing operator, with . For simple functions on a common disjoint partition, apply the Grothendieck inequality to the vectors and norming vectors of the images. The scalar sign or phase supremum is the weak 1-norm of the family. Approximation by simple functions proves the general result.
If the closed span of the Rademacher functions were a complemented subspace of , compose a projection with the inverse of its l2 sequence space parametrization. The Grothendieck theorem for L1 to Hilbert operators would make this map an absolutely summing operator. Its composition with the parametrization would make the identity on the infinite-dimensional l2 sequence space absolutely summing, contradicting its coordinate-vector test.
A bilinear form on a normed vector space is continuous exactly when it is bounded. For the nontrivial direction, continuity at gives such that whenever and ; scaling nonzero into these balls gives .
A bilinear form is alternating if for every vector . Expanding gives , hence . If the characteristic is not two, the converse follows from by dividing by two. In characteristic two, the relation is just symmetry and does not force zero self-pairings: on has .[ref]
https://webspace.maths.qmul.ac.uk/p.j.cameron/notes/linalg.pdf. Peter J. Cameron, Notes on Linear Algebra, §§9.1–9.2: alternating forms in arbitrary characteristic
The matrixgives an alternating bilinear form over every field. Over the real numbers, its value is the signed area of the parallelogram with sides : , and swapping the sides gives . Every self-pairing is zero, yet , so this bilinear form is nondegenerate. Directly, pairing with gives , and pairing it with gives ; both vanish only when .
In characteristic different from two, a skew-symmetric matrix of odd integer size has zero determinant, since . Thus an alternating bilinear form on a finite odd-dimensional vector space is a degenerate bilinear form. The stronger statement that the rank of an alternating bilinear form is even holds in all characteristics: splitting off a two-dimensional block with matrix repeatedly proves it. A nondegenerate alternating bilinear form defines a symplectic vector space, the linear setting for signed area rather than squared length.
For a bilinear form on a finite-dimensional vector space, the displayed right bilinear orthogonal complement is a subspace. Nondegeneracy identifies the ambient space with its dual and gives . If the form is symmetric or alternating, orthogonality is reciprocal and . For a general nonsymmetric form, left and right complements must be distinguished. A restricted symmetric or alternating form has radical of a bilinear form ; quotienting by that radical of a bilinear form gives a nondegenerate induced form.
For a bilinear form on a finite-dimensional vector space , let send to . Under the bidual evaluation map, is the annihilator of a vector subspace , so . The rank-nullity theorem on now gives the displayed equality. In particular the sum of dimensions is at least . If , the dimension formula for a sum of subspaces forces . The exact formula records the extra dimensions contributed by the left radical , and does not assume an inner product.
A linear bijection between spaces carrying compatible bilinear forms, Hermitian forms or quadratic forms is an isometry of a space with a form when it preserves the specified form. Preserving the polar form alone need not preserve a quadratic form in characteristic two. Subspaces may have degenerate restricted forms even when the ambient form is nonsingular.
A vector is anisotropic for a quadratic form if , and for a Hermitian form if . The complementary zero-value condition is isotropy. For a symmetric bilinear form in odd characteristic of a field, this agrees with the associated quadratic form. A nondegenerate alternating bilinear form has all self-pairings zero, so nondegeneracy must not be confused with the existence of anisotropic vectors.
An isometry of a space with a form between subspaces of a finite-dimensional nonsingular classical space extends to an ambient isometry. This includes alternating bilinear forms in all characteristics, symmetric bilinear forms in characteristic different from two, Hermitian forms with nontrivial involution, and quadratic forms with nonsingular polar form. No nonsingularity of the restricted subspace is required. Bare nonalternating symmetric bilinear forms in characteristic two require additional hypotheses and must not be confused with quadratic spaces.
The inertia of a real symmetric bilinear form is the triple giving the numbers of positive, negative, and zero squares in a diagonalization. Sylvester's law of inertia makes it independent of the chosen basis.
For a real symmetric bilinear form, let and be the dimensions of its positive and negative diagonal subspaces. This pair gives the first two components of the inertia of a bilinear form and is independent of basis by the Sylvester's law of inertia. For a nondegenerate form their sum is the full dimension; otherwise the nullity is an additional invariant. Another convention calls the difference the signature of a quadratic form. The pair convention describes the positive and negative harmonic spaces of the real de Rham intersection form in dimension four.
Articles by others on the same topic

A bilinear form is a mathematical function that is bilinear in nature, meaning it is linear in each of its arguments when the other is held fixed.



Analogous to a linear form, a bilinear form is a Bilinear map where the image is the underlying field of the vector space, e.g. .
Some definitions require both of the input spaces to be the same, e.g. , but it doesn't make much different in general.
The most important example of a bilinear form is the dot product. It is only defined if both the input spaces are the same.