Original solutions to both sections and all six questions of the Approximation Theory and Finite Element Methods paper sat on 10 June 2010. Source: released Mathematics papers,
Part C 2007 11.pdf. Question 1 gives the sharp bound for the printed functional; question 4 distinguishes the printed normal condition from the conormal condition needed for the requested symmetric variational construction. Statements are not reproduced.Direct evaluation gives and . Hence the linear functional vanishes on every polynomial of degree at most two and is nonzero on every genuine cubic polynomial.
The Peano kernel theorem with order three gives , whereThe first term comes from differentiating at . On the integration interval this simplifies toIn particular . Its L1 norm is , so the sharp bound isThe printed constant is false for the printed functional. The cubic has but , and it attains the corrected bound. This is an exact Peano kernel norm calculation, not an error from numerical quadrature.
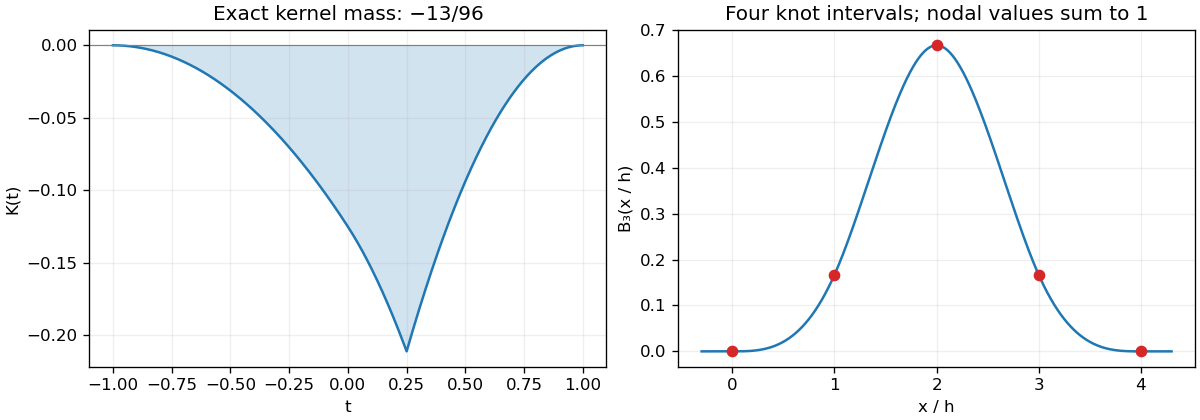
The negative Peano kernel fixes the sharp error constant, while the normalized compact cubic B-spline spans four knot intervals
. Details. A cubic spline that vanishes for and is twice continuously differentiable can be written using truncated power functions as . Vanishing for imposes the four moment equations for . Their Vandermonde matrix has rank , so a nonzero coefficient vector first exists at .
A normalized compact cubic cardinal B-spline isIt has nodal values at , so their sum is one. The alternating binomial coefficients meet the four moment equations, and the factor fixes the requested normalization.
For interpolation on , centre the translates as , with . Their restrictions form a basis for the cubic spline space on these knots. Write . The interpolation equations areThe recurrence determines all remaining coefficients after choosing , giving exactly two free parameters. The two natural cubic spline conditions becomebecause .
For uniqueness, take the difference of two candidates. It vanishes at every knot and has . Integrating by parts twice on each cubic piece gives : terms involving vanish at the knots, and those involving cancel at internal knots and vanish at the endpoints. Thus ; the remaining affine function vanishes at both endpoints and is zero. The square linear system for the coefficients is therefore nonsingular, giving existence as well as uniqueness of the natural cubic spline interpolant.
Let . If minimizes the squared L2 norm error, then for any the real quadratic has its minimum at . Its derivative there is zero, giving .
Conversely, if is orthogonal to , then for every , and the Pythagorean theorem for inner product spaces givesThis proves the equivalence and identifies as an orthogonal projection. It characterizes a minimizer whenever one exists; a general nonclosed vector subspace need not admit a projection for every .
The orthogonal projection is . Subtract it from and use the orthonormal basis relations to obtainThis is the requested Bessel inequality.
For the infinite tail, use completeness of the orthonormal polynomial family in the usual weighted L2 space. The relevant density facts are that continuous functions are dense for the finite measure , and the Weierstrass approximation theorem makes polynomials uniformly dense in continuous functions on the compact interval. Since , uniform approximation also gives weighted L2 norm approximation. Parseval's identity therefore givesHere finiteness of the weight integral is also necessary for the constant polynomial to belong to the stated Hilbert space. Without completeness of the polynomial family, an additional squared component orthogonal to every polynomial would remain; Bessel inequality alone does not justify equality.
The moments are . The Gram-Schmidt process first gives the constant . Removing the constant component of gives , with squared norm , hence .
For the quadratic, imposing orthogonality of to one and gives and . Thus , whose squared norm is . Taking positive leading coefficients, the first three orthonormal polynomials are
For , is orthogonal to every polynomial in , so . The Cauchy-Schwarz inequality givesUsing the tail identity from part (b) and shifting the index,For the stated power law and , the decreasing-function integral test givesConsequentlyThe assumption is sufficient; this summation estimate itself only needs .
Put and . If the best uniform approximation had error below , the values of would strictly alternate in sign at all reference points. The intermediate value theorem would give at least distinct roots of a polynomial of degree at most , a contradiction. If the lower bound is immediate.
At least one reference point attains the global error maximum of , so . Optimality of gives the upper bound, and thereforeThis is the unequal-height version of the alternating-reference error bound.
Here the exchange point lies between adjacent reference points and has the same, positive error sign as the point it replaces. Hence the new set remains spatially ordered, and the old error at its points alternates in sign. Its magnitudes are everywhere except at , where .
Set . Apply the order- divided difference to and ; both vanish because their degrees are at most . In the new alternation equations, all products have the same sign. Thus the single-point exchange in polynomial minimax approximation givesThe Remez algorithm repeatedly solves for the reference polynomial and common signed height, locates a larger error extreme, and performs an order-preserving exchange. The reference height bounds the optimum from below and the global error maximum bounds it from above. Their gap provides an optimality stopping certificate. A general implementation also needs the endpoint exchange rule when the new extreme lies outside the reference set.
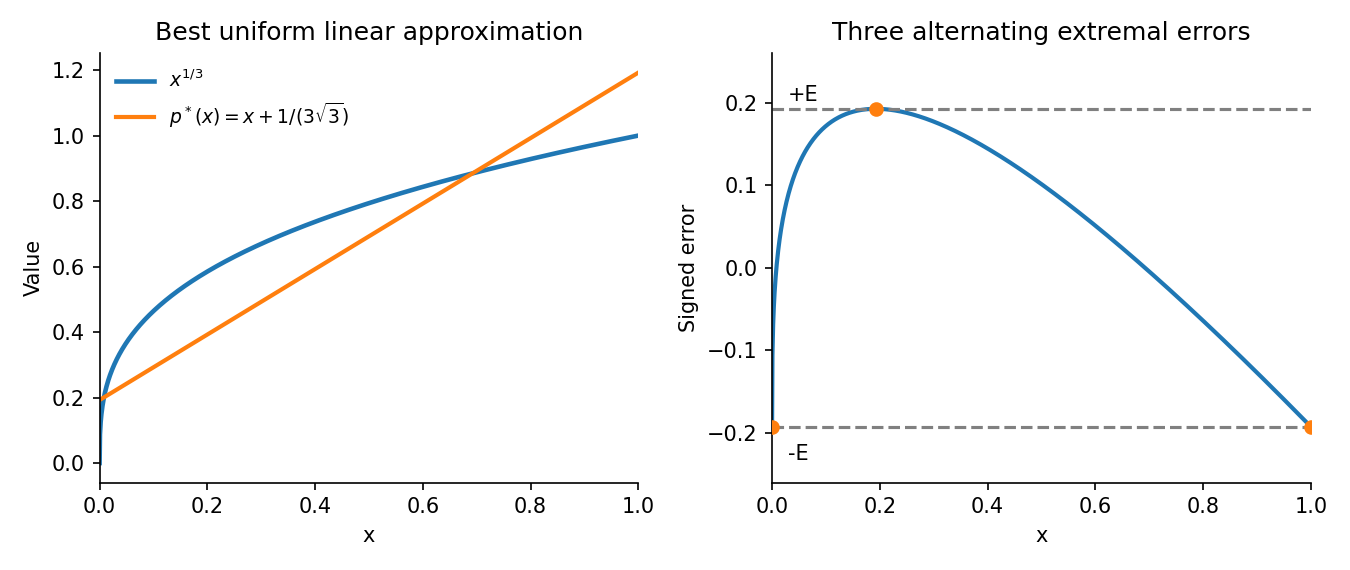
For a line , the error is strictly convex. Its two endpoint maxima must agree, giving . Its unique interior minimum is at . Equating its magnitude to the endpoint error givesThe errors at are respectively . The equioscillation theorem therefore certifies this best uniform approximation directly.
For degree above one, subtracting a general polynomial does not preserve convexity of the error. The required alternating extreme points include additional unknown interior points, and their derivative and equal-height equations form a coupled nonlinear problem. The simple endpoint-and-single-minimum calculation therefore does not extend as a direct higher-degree recipe.
The first-order Sobolev space is , with derivatives understood as weak derivatives and norm squared .
The printed normal boundary condition must be distinguished from a conormal condition. Take symmetric positive definite, as required for the symmetric matrix requested later. Integration by parts givesThe natural boundary term contains the conormal derivative , not the ordinary normal derivative . On a smooth boundary, writing for its unit tangent, the literal condition leaves the term , where . Its weak form therefore retains a boundary pairing:Here the tangential derivative of the Sobolev trace can be interpreted in and paired against on a smooth boundary. This form is generally nonsymmetric; the requested usual symmetric energy construction does not follow from the literal boundary condition.
For an explicit failure of the claimed mean-zero compatibility, take the unit disk, and . It has on the circle, butThus replacing the printed normal condition by a zero conormal flux is not harmless.
For the intended zero-conormal derivative problem, the requested variational and finite element conclusions are as follows. Seek withPutting gives . On a connected domain this condition permits a solution unique modulo constants; the Poincare-Wirtinger inequality gives coercivity after fixing the mean.
The energy is . A minimizer satisfies . Conversely, a weak solution satisfiesso it is a minimizer. Testing by gives the minimum valueThis value is independent of the arbitrary additive constant when . If the compatibility fails, constant shifts make unbounded below.
Write . The Galerkin method givesSymmetry of gives . For , . Equality forces constant by positive definiteness and connectedness. Since the basis sums to one, the coefficient vector represents that constant, givingThus the stiffness matrix is symmetric positive semidefinite and singular; the displayed compatibility condition is necessary and sufficient for the finite system. Positive definiteness of controls every gradient direction, preventing additional zero-energy directions and supplying ellipticity. A degenerate coefficient can introduce further kernel modes, while an indefinite one destroys the minimizing-energy argument.
Take the affine trial space and the test space . Multiplication by and integration by parts incorporate the right Neumann boundary condition as a load:For the continuous piecewise-quadratic trial space, impose the left value exactly and use the same equation for every piecewise-quadratic test function vanishing at . With a basis of that test space and , the finite element equations areThe Endpoint Poincaré inequality, reflected about the interval midpoint, makes the derivative norm a norm on . Galerkin orthogonality then gives the exact best-approximation identity: for every admissible ,Therefore minimizes the derivative error over all admissible piecewise-quadratic functions.
To prove the requested error bound, assume . Then and . We need an elementary Poincare-Wirtinger inequality on each element of length : if has mean zero, its continuous representative has a zero somewhere, and the fundamental theorem of calculus and Cauchy-Schwarz inequality give .
Choose an affine function whose slope is the average of on and whose average equals the average of . Then and both have mean zero. Applying the just-proved bound twice yieldsDefine a quadratic interpolant on by integrating from the true left-endpoint value. The equal-average condition ensures that it reaches the true right-endpoint value, so these pieces join to an admissible continuous piecewise-quadratic function . Sum the squared estimates and use the best-approximation property:Only the maximum element length is used; equal spacing is unnecessary.
For the Aubin–Nitsche duality argument, let and solve , , . Explicitly , so . Integration by parts and Galerkin orthogonality givewhere is its nodal piecewise-linear interpolant, which belongs to the quadratic test space. On each element is the average of , so the same mean-zero inequality gives . Canceling when nonzero proves the additional order:
The bilinear square finite element contains the terms . In anticlockwise corner order beginning at , its shape functions areThe mass matrix has entries . Each product separates into one-dimensional factors, with and . Diagonal, adjacent-corner and opposite-corner entries are respectively , , . ThusNumber global grid nodes by , with , and . For an interior node, four elements contribute to its diagonal, two to each axial neighbour and one to each diagonal neighbour. Its global row therefore has the nine-point stencilIn the stated ordering the axial entries occur at columns and ; the four diagonal ones occur at . No boundary degrees of freedom have been removed.
For general valid quadrilaterals, use an isoparametric finite element. Map the unit square to an element by and define physical shape functions . Require a one-to-one nondegenerate map and compatible common edges. On a shared edge the map and the trace of each shape function are linear between the same endpoints; the neighbouring traces therefore agree. The assembled functions are continuous and lie in , giving a conforming finite element space. On a non-parallelogram the pulled-back functions are generally not bilinear polynomials in the physical coordinates themselves.
Define the Lagrange cardinal polynomialsDistinct nodes make every denominator nonzero. At these polynomials satisfy , so the Lagrange interpolation polynomial isIt has degree at most and takes the prescribed data values. If two such polynomials existed, their difference would have distinct roots but degree at most , forcing that difference to be zero. This also proves uniqueness.
With , the Lagrange interpolation polynomial can be written, away from its nodes,Apply the same formula to the constant data . Uniqueness of polynomial interpolation gives , and henceDivide the two identities to obtain the barycentric interpolation formulaAt , use the continuous limiting value . Multiplying every weight by the same nonzero constant cancels between numerator and denominator, so only relative weights are needed in computation.
For uniformly spaced nodes,There are negative factors, coming from . Thus the weights fixed by part (b) satisfy this formula exactly. The printed sign agrees for even ; for odd it differs by the common factor . Rescaling all weights by gives the printed convention without changing the barycentric interpolation formula.
For even , the required magnitude isStirling's formula givesThus central weights are exponentially larger in magnitude than endpoint weights. Their alternating signs can cause severe cancellation in polynomial interpolation at equispaced nodes; they reflect the unfavorable high-degree interpolation geometry associated with Runge's phenomenon. A barycentric evaluation formula improves the implementation but does not remove the intrinsic sensitivity or guarantee convergence for every smooth function. The comparison with the bounded relative weights at Chebyshev-Lobatto nodes is decisive.
Use the Chebyshev polynomial identities , , and . Induction shows that has degree with leading coefficient for . The trigonometric definition also givesThereforeThe leading coefficient is , and the degree is . The endpoints are roots through ; the other points are roots through . They are distinct, so this monic polynomial is exactly .
Differentiating the product at gives . For an interior node, differentiate the trigonometric form using :At , this is . At either endpoint, taking the limit makes the two terms equal, doubling the value: for .
After removing the common factor , the barycentric interpolation formula therefore usesThese Chebyshev-Lobatto node weights differ in magnitude by only a factor of two.
Let be the distinct roots in at which changes sign, and put . Both and change sign at each such point, while roots of even multiplicity do not change sign. Consequently has one constant sign on except at its zeros, and is not identically zero. Its integral cannot vanish.
If , however, orthogonality of the monic orthogonal polynomial to every polynomial of lower degree gives , a contradiction. Hence . Since , there must be exactly such roots, each of multiplicity one. They exhaust the degree, leaving no complex, exterior, or endpoint roots. Thus all roots are simple and lie strictly in , which proves the requested weaker inclusion in . This is the sign-change proof of the zeros of orthogonal polynomials theorem.
The monic orthogonal polynomials form a basis of , ordered by degree. Since is monic of degree ,For , symmetry of multiplication by gives , because . Only and remain. Taking inner products with yields .
Similarly,since has degree at most . Rearranging proves the three-term recurrence for monic orthogonal polynomials:
The relevant integrals areInsert these into the three-term recurrence for monic orthogonal polynomials:ThusTheir mutual orthogonality can also be checked directly by integrating on .
The best approximation in the norm is the orthogonal projection onto . ThereforeUsing ,It follows thatThe error is orthogonal to every linear polynomial, so the Pythagorean identity proves optimality and uniqueness. At , this gives ; at , it gives . Both are exact because the target itself then belongs to .
Put . For ,whereas the constrained rational interpolant expands asMatching the constant term gives , and matching the coefficient of gives . Thus , , andThis is an endpoint-constrained rational approximation to a power: it matches value and derivative at and also enforces for .
There is a terminology qualification. A standard degree- Padé approximant about matches through , but the displayed constrained expression has quadratic coefficient rather than . The unconstrained Padé approximant is insteadThe source's requested formula is obtained by the two stated endpoint matching conditions within its restricted family, rather than by full Padé matching. At both reduce to . At , the requested expression is one for with a removable value at zero; finite in the original restricted form do not represent that constant function. The endpoint is understood by this limit.
By definition, a best uniform approximation minimizes over . Write . The equioscillation theorem says that, if , optimality is equivalent to the existence of ordered points with signed errorsThe absolute-value bars on the left of the printed formula must be omitted for this alternating-sign statement. A nonnegative absolute value cannot equal a negative .
For sufficiency, suppose a polynomial had strictly smaller error. At the alternating points, must have the same sign as , since otherwise the new error would have magnitude at least . The difference polynomial therefore changes sign in all successive gaps and has at least distinct roots, impossible for a nonzero element of .
For necessity, suppose that no alternating extremal points exist. On the compact extremal set , group the signs of the error into consecutive blocks. The positive and negative extremal sets are disjoint compact sets, so sign changes are separated by positive distances; the number of blocks is finite. The absence of an alternating selection means there are at most blocks. Place a root in each gap between successive blocks and choose the overall sign of their product to agree with the error on . Then and is nonzero throughout .
By compactness and continuity, on a neighborhood of the signs still agree and is bounded below. A sufficiently small positive reduces the error there when is replaced by . On the compact complement of this neighborhood the old error is below by a fixed positive margin, and choosing smaller preserves that margin. This gives a strictly better approximation, a contradiction. If , the target already lies in and optimality is immediate.
For , the chord is . Concavity gives , with maximum at and maximum value . Shift the chord up by half that amount. The errors at are respectively , so
Use the standard meaning of a cubic spline: a function that is cubic on each unit interval. If it vanishes on both exterior intervals, continuity of the function and its first two derivatives gives zero endpoint jets at zero and at .
Such a spline can be represented through its third-derivative jumps asFor , this must be the zero polynomial. Expanding in powers of yields the four moment conditionsIf , the columns of this Vandermonde system are linearly independent, so every . No nonzero spline has such short support.
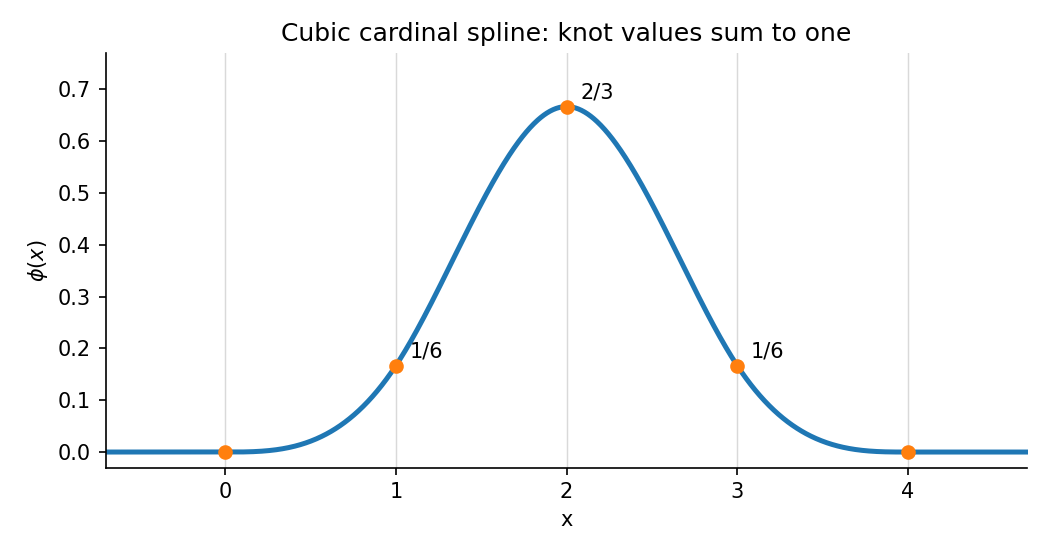
For , a nonzero null vector is , since the fourth finite difference annihilates every cubic. Thus the Cardinal cubic B-spline isIts knot values at are , whose sum is one. It is nonzero and supported on , proving the minimal value . Equivalently, on it is , on it is , and the other half follows by symmetry .
Work in the usual bounded Lipschitz, polygonally triangulated setting in which Sobolev traces and conforming meshes are defined. Choose an lift of the smooth boundary data. Multiplying the Poisson equation by and integrating by parts gives the weak formulationThe test function has zero trace, so the boundary flux term vanishes. This formulation only needs first weak derivatives.
Let be the conforming finite element space of continuous functions affine on each triangle, and its zero-boundary subspace. Choose a nodal interpolation of the boundary lift and seek satisfying the same identity for every . General smooth boundary data need not be exactly representable by boundary piecewise linear functions; this is the usual discrete boundary approximation.
With nodal shape functions , interior coefficients satisfyHere and index interior and boundary vertices. Finite element assembly sums the triangle contributions.
Take a translated lower triangle with local vertices . Its local functions are , , . Their gradients are constant and the area is , giving the stiffness matrixTranslations preserve this matrix, while rotations or a different local vertex order permute its entries. The coupling across the hypotenuse is zero.
Each interior grid vertex belongs to six triangles. Summation gives diagonal value 4 and coupling to each of its four horizontal and vertical neighbors. Both positive-diagonal edge couplings vanish. Thus, before prescribed boundary values are removed, an interior equation has the five-point stencilThere is no factor in the assembled variational matrix; that factor belongs to a differently normalized finite-difference equation.
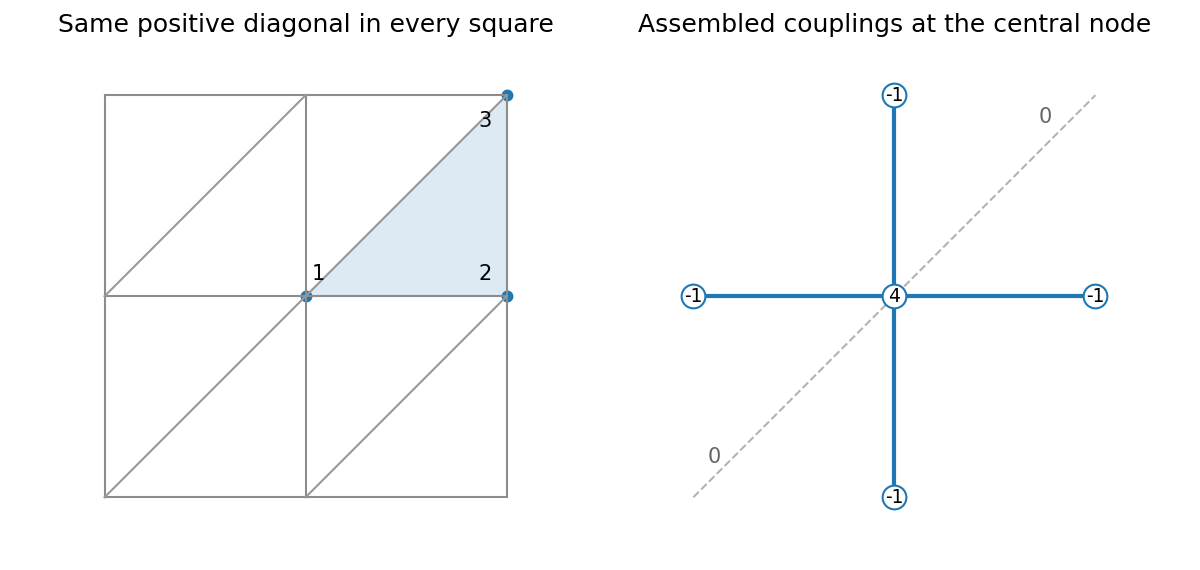
If and , lexicographic ordering makes the Dirichlet-reduced matrix block tridiagonal with diagonal blocks and neighboring blocks . A row with all four neighboring nodes unknown has five nonzeros: 4 once and four times. Rows adjacent to the boundary have fewer unknown-neighbor entries; their exact count is . Removed boundary contributions appear on the right, rather than as new nonzeros.
The Sobolev space consists of functions with a weak first derivative in , with normIn one dimension these functions have absolutely continuous representatives and well-defined endpoint Sobolev traces. PutThis is a closed subspace, hence a Hilbert space. Both trial and test functions belong to ; one does not impose a derivative boundary condition in this space.
Integrate the differential equation against :The printed condition uses the ordinary derivative, , so the weak form isSeek with for all . The coefficient in the endpoint term must be retained: replacing the ordinary derivative with the conormal flux would change the boundary problem.
Let . The Poincaré inequality on can be stated as . Also . Consequentlyproving coercivity. By Cauchy-Schwarz inequality and the trace bound,Thus continuity holds with . The load is continuous if , and the Lax-Milgram theorem gives a unique weak solution.
Choose a finite-dimensional conforming subspace , such as continuous piecewise linear functions vanishing at , and solve for every . Subtracting the weak equations gives Galerkin orthogonality .
Céa's lemma states, for a continuous coercive bilinear form with constants on a Hilbert space,To prove it, put and use orthogonality to write for any . Coercivity and continuity give . If the claim is immediate; otherwise cancel its norm and take the infimum. Any approximation theorem making the infimum tend to zero under mesh refinement therefore gives strong convergence in .
Finally, is symmetric and positive definite on . It is an inner product, so is an energy norm on all of : homogeneity and definiteness are immediate, and Cauchy-Schwarz inequality for this inner product gives the triangle inequality. No smaller space is required. In this norm the continuity and coercivity constants are one. More precisely, Galerkin orthogonality givessoThe finite element solution is the exact best energy-norm approximation.
Take linearly independent basis functions and write . The weak formulation of the heat equation, tested against , isThus the semidiscrete finite element heat equation isThe vector contains the basis coefficients. A natural initial vector is the projection of the initial data: , where , and . Other consistent initial approximations can be specified, but exact representation of an arbitrary in the trial space is not implicit.
For a nonzero coefficient vector , the function is nonzero by basis independence. Hence , proving that the mass matrix is symmetric positive definite. Also : if the derivative vanished, would be a constant, and its zero endpoint traces would make it zero. Therefore is symmetric negative definite, not merely semidefinite, for these homogeneous Dirichlet conditions.
The squared spatial norm is . Differentiating and using the semidiscrete system gives the energy identityUsing the trapezoidal rule in time gives the Crank-Nicolson methodThe left matrix is positive definite for every , so every step exists uniquely. To prove stability, set and . The update says . Multiplying by givesConsequentlyThe same inequality applied to the difference of two discrete solutions proves nonamplification of initial perturbations. This is unconditional stability in the mass-matrix norm, exactly the spatial norm of the finite element functions.
Put . The trigonometric identitygives the Chebyshev polynomial recurrence . Starting from and , successive substitution yieldsThe recurrence also proves by induction that is a polynomial of degree , with leading coefficient for .
For , set . It is monic by part (a), and its supremum norm on is . At the successive extreme points it alternates between and .
Suppose a monic degree- polynomial had . At each , the difference would have the sign of . These signs alternate, so the intermediate value theorem forces a root in each of the successive gaps. But the leading monic terms cancel, making , a contradiction. ThereforeThis is the monic monic Chebyshev extremal polynomial. The positive-degree restriction matters: at the printed scaling gives the constant two, while the only monic constant is one, so that version is false. The customary theorem uses .
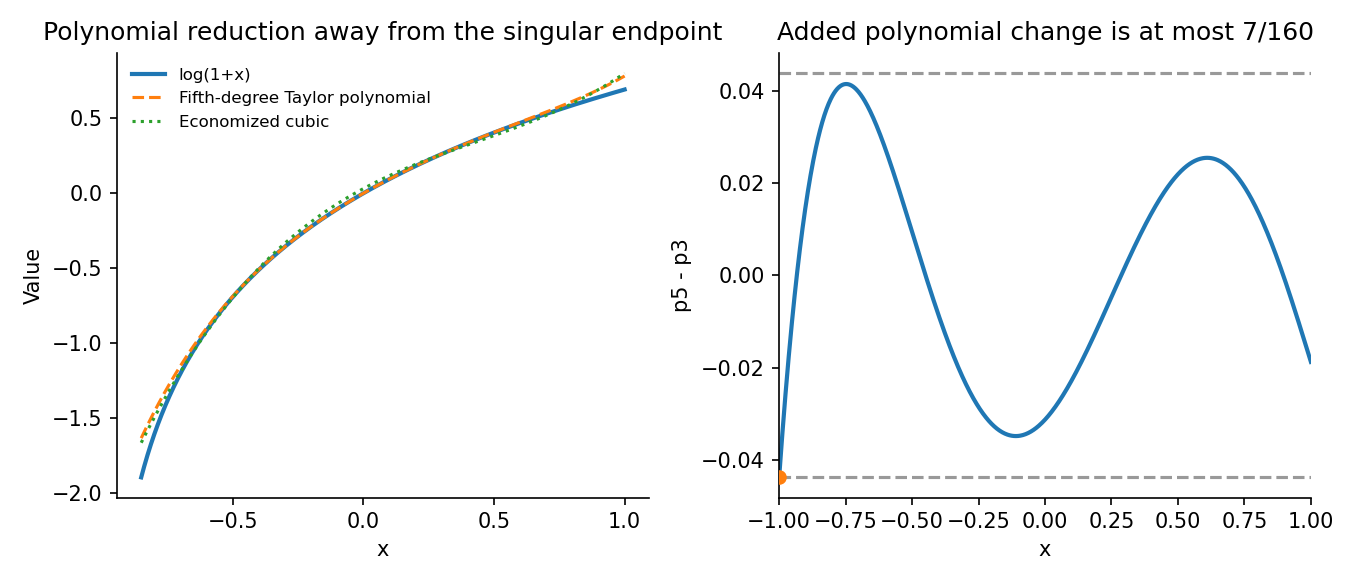
Expand the fifth-degree Taylor polynomial in Chebyshev polynomials, using the identities for powers obtained from part (a):Delete the last two Chebyshev terms and convert back to powers. The economized cubic isSince ,Equality holds at , where both deleted terms have negative sign. Thus the economization changes the polynomial by at most , exactly in supremum norm on .
For the target itself, wherever . The logarithm is singular at , so its total uniform error on all of is infinite; the finite estimate concerns the additional polynomial change, or the increase on any smaller interval where the original error is bounded.
Use the standard convention that the orthogonal polynomials are nonzero. Their exact degrees then follow from the stated assumptions by induction: is a nonzero constant, and if span , a nonzero orthogonal to all of them cannot lie in .
Let be the distinct sign-changing roots of in , and put . Then has constant sign between and across all its roots, and is not identically zero. Because in the interior, is nonzero. If , orthogonality to would make this integral zero. Thus .
A degree- polynomial cannot have more than roots counted with multiplicity, so all roots are real, simple, and strictly inside . This is the standard zeros of orthogonal polynomials argument, with the positive weight ensuring strict noncancellation.
The displayed recurrence requires monic normalization, which is not explicitly stated in the preamble. Arbitrary independent rescaling of orthogonal polynomials preserves orthogonality but changes the recurrence coefficients. Choose their monic representatives for this and the following calculations.
Expand in the orthogonal polynomial basis:The leading coefficient of is one. For , , because the second factor has degree below . Thus only remain. Inner products giveThe last equality uses . Rearranging yields exactly the three-term recurrence for monic orthogonal polynomials
For , orthogonality to requiresSolving gives , . HenceThese are the nodes for the two-node Gaussian quadrature with quadratic weight.
Exactness on constants and linear functions givesWith the nodes just computed, the solution isTo prove cubic exactness rather than merely moment matching, divide a polynomial of degree at most three by the monic :The weighted integral of vanishes by orthogonality, and its two nodal values vanish because the nodes are roots of . The remaining is integrated exactly by the two equations above. This proves Gaussian quadrature exactness through degree three.
For a real-valued linear error functional annihilating , the Peano kernel iswhere is the argument on which the functional acts. Under the standard boundedness and extension hypotheses, the Peano kernel theorem statesFor example, a bounded functional on continuous functions, represented by a finite signed measure and extended to the truncated powers, has this representation. Quadrature error functionals have precisely this structure.
The source's bare linearity assumption on is not by itself a complete theorem hypothesis. Truncated powers need not belong to that domain, and interchange of the functional with an integral needs justification. For instance annihilates but would require a Dirac point mass rather than an ordinary integrable kernel. The statement above supplies the usual functional class needed for the requested theorem and applies directly to part (c).
If has one sign, the weighted mean-value theorem applied to the continuous derivative givesfor some . One may prove this by bounding the weighted integral between the minimum and maximum derivative values times the total weight, then using the intermediate value theorem. If the total weight is zero, the fixed-sign kernel is zero almost everywhere and the conclusion is immediate.
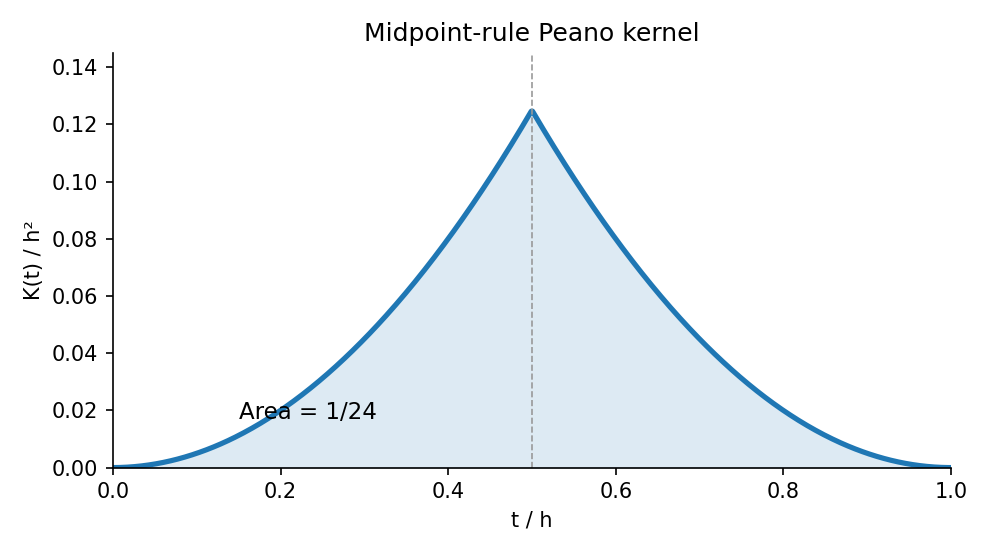
The midpoint error annihilates affine functions, so here . Apply the functional to :ThusIt is nonnegative, and symmetry gives . ThereforeFor a quadratic with constant nonzero second derivative equality holds, so this midpoint quadrature rule error constant is sharp.


The equioscillation theorem says that a best degree-at-most- polynomial approximation to a continuous real function on has ordered extreme-error points with alternating signs and equal absolute error. Conversely such alternation proves optimality. If the error is zero, the target is already a polynomial of the required degree.
For the single-point exchange in polynomial minimax approximation, start with ordered reference points and solve the linear systemfor the polynomial coefficients and . Locate a point of largest absolute error on the interval. If its magnitude is no larger than within the desired tolerance, alternation certifies the approximation.
Otherwise insert that point and delete one old reference point so that the ordered signs still alternate. If the new point lies between two reference points, delete the neighboring point with the same error sign. If it lies outside the reference range, either replace the adjacent same-sign endpoint or, for opposite sign, insert it and drop the far endpoint. Solve again and repeat. This is the one-point Remez algorithm; a global extreme-error search is required for its stopping certificate, rather than merely checking the old reference points.
A piecewise cubic supported on has the truncated-power representation with indices . Vanishing for imposesafter expanding its cubic exterior polynomial; powers of cancel. For , the Vandermonde matrix columns are independent, forcing every coefficient to be zero. For , coefficients proportional to satisfy these conditions because a fourth finite difference annihilates cubics.
Normalize to get the Cardinal cubic B-splineAt its five support knots its values are , so their sum is one. Thus four intervals are necessary and sufficient.
For , the five translates active in the interior of are indexed . Write . Nodal interpolation givesAt the left endpoint the first derivatives of the three active functions are , and their second derivatives are . The two remaining equations areTogether these five equations form the requested system; insert if numerical coefficients are desired. The first, fourth and fifth determine the first three coefficients, and the other two then determine , so the system is nonsingular.
The source only assumes , which need not have either endpoint derivative. The Hermite conditions require those derivatives to exist, or to be supplied as separate interpolation data. The nodal conditions alone remain meaningful for every continuous .
The Sobolev space consists of square-integrable functions whose weak first derivative is square-integrable, with norm . Its one-dimensional representatives have well-defined endpoint traces.
Multiplying by and integrating by parts givesThe two Robin conditions give and , so defineA weak solution is satisfying for every . The boundary conditions are natural; no endpoint derivative is imposed in the trial space.
Since on this interval,This proves coercivity on the full space. Trace continuity and Cauchy-Schwarz give continuity of the form, so the Lax-Milgram theorem also ensures a unique weak solution.
Let be the space spanned by all hats, including the endpoint hats. The solution in a conforming finite element space satisfies for all . The continuous form remains coercive and continuous on this subspace, so the discrete solution is unique.
Articles were limited to the first 100 out of 186 total.
Articles by others on the same topic
There are currently no matching articles.