The conditional expectation is the average of a random variable that can be predicted using specified information. It is itself a random variable: the average appropriate to one observed group may differ from that appropriate to another group. The sigma-algebra records which events can be distinguished with the available information.
For a real integrable random variable on a probability space and a sub-sigma-algebra , the conditional expectation is the almost surely unique integrable random variable that is measurable with respect to and satisfiesIts average therefore agrees with that of on every distinguishable event. The integral characterization handles discrete observations, continuous observations, and information that is not given by a single numerical value.[ref]
If the information tells us which member of a finite measurable partition contains the outcome, then on every member of positive probability,Here is an indicator function. Zero-probability members do not determine a unique value, which is why uniqueness is only almost surely. For square-integrable , this same conditional mean is the best predictor among -measurable random variables under mean squared error; the conditional variance describes its remaining error. A conditional mean is generally not the same as the actual observed value of .[ref]
If almost surely and for integrable , conditional expectations converge almost surely and in . Conditional Fatou lemma applied to and bounds the conditional liminf and limsup by the same limit. For convergence, the contraction estimate and dominated convergence theorem finish the proof. This also permits taking an unbounded measurable factor out of a conditional expectation by clipping it, provided the original product is integrable.
Let a probability space have countable measurable partitions of positive-measure cells, each partition refining its predecessor. An exceeding point has a first level where its cell average of exceeds . The cells at those first crossings are disjoint: intersecting cells at different levels are nested, and an earlier exceeding cell prevents any of its descendants from being a first crossing. They cover exactly the maximal superlevel set. Summing their strict average inequalities gives the displayed weak type (1,1) estimate with constant one. The same proof works on a general measure space when every relevant cell has positive finite measure.
Assume in addition that the probability space is a metric space, continuous integrable functions are dense in , and the diameters of its partition cells tend to zero at each point. For a continuous , the oscillation average tends to zero because every point in is within its diameter of . For , the upper limit of the oscillation of is bounded by the partition maximal function of plus . The first-crossing maximal inequality for refining partitions and Chebyshev's inequality bound the measure where this exceeds by . Approximation proves the displayed almost everywhere assertion. Refinement supplies the maximal estimate; shrinking diameter supplies the approximation argument. Without shrinking diameter, a constant partition generally converges only to its cell averages.
Let be a martingale with and let on a finite horizon. Its restriction to has Radon-Nikodym derivative . If is Q-integrable and , then for every ,Also is P-integrable because . The defining uniqueness of conditional expectation gives the displayed formula. In particular, if is a P-martingale and is Q-integrable, conditioning first at an intermediate time proves is a Q-martingale.
Let belong to L2 space, and suppose and almost surely, for two possibly nonnested sigma-algebras. Then almost surely. No independence or inclusion between the sigma-algebras is required.
The identities supply -measurable and -measurable versions of and . The measurable-factor rule for conditional expectation and Cauchy-Schwarz inequality giveExpanding the square shows , and hence the required almost sure equality. Equivalently, each conditional expectation is an orthogonal projection in L2 space, and the two projection identities force equality in the equality case for conditional second moments.
Equality after applying a function need not identify its original input. For instance, on four equally likely outcomes let take and set . Their squares are the same nonconstant random variable, even though and differ everywhere. Injectivity of the function would rule out this loss of information.
For nonnegative random variables , the corresponding nonnegative conditional expectations increase almost surely to , allowing the extended value . When is an integrable random variable, all conditional expectations can be taken in their ordinary finite sense.
To prove this integrable case, choose versions simultaneously ordered outside a single null set, and put . This limit is -measurable. For every , the ordinary monotone convergence theorem twice givesIn particular , and this is exactly the defining property of conditional expectation. For a general nonnegative , define its extended conditional expectation by increasing bounded truncations; the same nonnegative integral argument proves the statement.
Let be an integrable random variable, let be a finite -measurable random variable, and suppose is an integrable random variable. Then a known factor can be taken outside the conditional expectation:For a bounded , first verify the defining integral identity when is the indicator function of a measurable set in , extend by linearity to simple functions, and then use bounded approximation and the dominated convergence theorem. For nonnegative , truncating and using the conditional monotone convergence theorem proves the identity with extended nonnegative conditional expectations. In particular,For general under the stated integrability assumptions, the conditional Jensen inequality bounds by that integrable random variable. Apply the bounded-factor result to truncations of , then use the dominated convergence theorem on the products and the L1 contraction of conditional expectation. This proves the identity without assuming itself is an integrable random variable.
The product-integrability condition is essential to the ordinary finite conditional expectation statement. An unbounded factor cannot be moved through an expected value simply because its partner is an integrable random variable.[ref]
Let be the probability of first success on attempt , conditional on reaching that attempt. Then the chain rule for probabilities gives ; no assumption of independent attempts is needed when these are the specified conditional probabilities. The chance of success by attempt is . Divide the truncated first moment by that probability to obtain the displayed conditional expectation, provided its denominator is positive. This is different from counting all unsuccessful cases as though they succeeded on the last permitted attempt.
For a real integrable random variable , a conditional expectation with the same probability distribution as must equal almost surely. No second moment is needed. For any real , the nonnegative random variable has expected value zero, by conditioning and equality of the two absolute moments. Thus implies , implies , and implies , outside a null set. Using a countable family of rational separates any unequal real values and proves the claim. Equality of the probabilities of and also gives equality of their zero sets and hence equality of the two sign functions for every fixed .
For an integrable function on , average on each dyadic interval of length . The resulting step function converges to almost everywhere and in the L1 norm. If has the uniform distribution on , then , where rounds down to a dyadic endpoint. Refinement makes these conditional expectations a uniformly integrable martingale. The uniformly integrable martingale convergence theorem gives almost-sure and convergence in L1 to a limit .
Since , the generated limiting sigma-algebra contains up to null sets. For every event in any finite-stage sigma-algebra, convergence in the L1 norm gives . The pi-lambda theorem extends this equality to the limiting sigma-algebra, identifying . The uniform distribution of translates the two convergence conclusions into the assertions for . Choosing a Borel representative of and assigning arbitrary values at the endpoint one makes all random variables well defined without changing either conclusion.
If a finite group acts by measure-preserving maps on a probability space, let be its invariant sigma-algebra. For an integrable random variable , the displayed group average is -measurable. For , changing variables under each group element gives . The average therefore satisfies the defining integral identity for conditional expectation. For permutations of exchangeable coordinates, averaging a product attached to distinct indices yields the sum over all ordered distinct -tuples divided by the falling factorial .
For arrays of values in , let average a product of entries over all ordered index tuples from coordinates, and let average it over the tuples with distinct indices. Decompose the first average as , where and the repeated-index average lies in . This gives . For uniformly sampled indices, a union bound over the pairs bounds the collision probability by . This deterministic estimate is the bridge between empirical-product limits and the De Finetti theorem.
For nonnegative integrable , the finite measure restricted to a sub-sigma-algebra is absolutely continuous with respect to the restricted base measure. Its Radon-Nikodym derivative is -measurable and has the required integral identities. Positive and negative parts extend the construction to real integrable functions; real and imaginary parts extend it to complex functions. The result is unique almost everywhere.
If is a real square-integrable random variable and , then and the displayed identity follows by expansion. Thus equality of the second moments forces as an almost sure equality. This is the equality case of the conditional Jensen inequality for the strictly convex function .
Disintegrate over a factor map and take the norm using the conditional probability on each fiber. Its square integrates to the global squared norm. The uniform conditional L2 norm takes the essential supremum of these fiber norms.
For invertible probability systems linked by a factor map, invariance and uniqueness of disintegration identify the pushforward of each conditional measure with the conditional measure on the transformed fiber. The displayed norm identity follows for all integer times on a common full-measure set. It transports uniform conditional error bounds along whole orbits.
The essential supremum over the base of the conditional L2 norm. It may be infinite for a globally square-integrable function. For probability fibers, ; the uniform norm controls all fibers outside a null set rather than only their average.
For an integrable random variable , a sub-sigma-algebra , and a convex function with suitable integrability, almost surely. One proof writes as a supremum of supporting affine functions and applies monotonicity and linearity of conditional expectation to each. This proves the convex-loss form of the Rao-Blackwell theorem.
For an integrable random variable , the conditional expectation satisfies almost surely. Taking expected values gives the L1 contraction of conditional expectation. Applying it to shows that convergence in L1 is preserved by conditional expectation with respect to any fixed sigma-algebra.
For independent and identically distributed random variables that are integrable random variables, with , symmetry gives . The decreasing sigma-algebras generated by these future sums permit application of the reverse martingale convergence theorem.
The law of total expectation makes averaging in stages reliable, provided the outer stage uses the actual probabilities of the groups. For an integrable random variable and a sub-sigma-algebra ,Replacing each outcome by its group's conditional mean preserves the overall expected value. In the definition of conditional expectation, take the event to obtain this identity.[ref]
For a complete finite example, choose a group with probability and with probability . Within group , is or with equal conditional probabilities; within group , it is or with equal conditional probabilities. Thus the joint probability distribution puts probabilities on . The conditional means are two and eight. Consequently,Direct averaging of the four values gives the same . Taking the unweighted average of the two group means instead gives five, which describes a different choice of group probabilities. This is why the outer weighting matters.
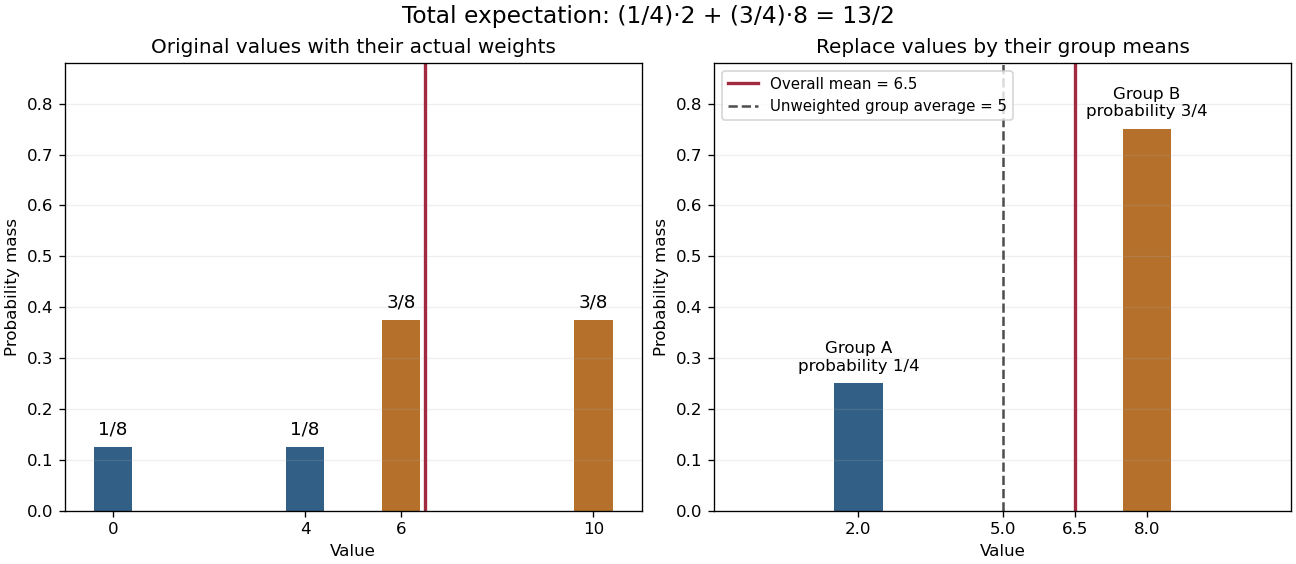
The formula is useful when conditioning on a first choice makes the remaining experiment simple. It can replace a large outcome enumeration by smaller calculations within groups. In a mixture distribution, it combines component means using mixture weights; in a random sum of independent claims, it separates the number of summands from their individual expected values under the stated independence assumptions. The same averaging step appears in the law of total variance.
A bound implies . It does not by itself imply . For , Jensen's inequality goes in the opposite direction. The missing contribution is the variance: .
For integrable random variable and nested sub-sigma-algebras , the tower property saysThe finer-information conditional mean can be averaged within each coarser group, recovering the coarser-information conditional mean. Conversely, conditioning an already -measurable conditional mean on leaves it unchanged. Both orders therefore recover when the information is nested.[ref]
For the finite example in law of total expectation, exact knowledge of gives the finer mean itself. Averaging within the groups recovers two and eight. Forgetting the group then gives . The nesting condition is essential; iterated conditional expectation over nonnested sigma-algebras describes why arbitrary successive conditioning cannot simply be replaced by conditioning on an intersection.
If sub-sigma-algebras and are independent, every event in is independent of itself and consequently has probability zero or one. Thusalmost surely for every integrable random variable .
In general,Equality does hold when either sigma-algebra contains the other or when they are independent.
For nonnegative random variables and a sigma-algebra ,almost surely. It follows from the ordinary Fatou lemma after testing both sides on every event in .
Articles by others on the same topic


Conditional expectation is a fundamental concept in probability theory and statistics that refers to the expected value of a random variable given that certain conditions or information are known. It captures the idea of updating our expectations based on additional information. Formally, if \( X \) is a random variable and \( Y \) is another random variable (or an event), the conditional expectation of \( X \) given \( Y \) is denoted as \( \mathbb{E}[X | Y] \).