For a twice continuously differentiable vector field in Cartesian coordinates, the curl and divergence arePut . Using the Levi-Civita symbol, the Kronecker delta contraction and the product rule,The last term vanishes because the divergence of a curl is zero: the symmetric mixed derivatives contract against an antisymmetric symbol. Thus the curl of a cross product identity becomes
For orthogonal coordinates with position vector , the scale factors of orthogonal coordinates and local unit vectors areOrthogonality gives , and right-handedness fixes . In cylindrical coordinates, , soThe radial vector points away from the axis; the azimuthal vector is tangent in the direction of increasing ; is the Cartesian positive direction. The azimuthal basis is undefined on the coordinate axis itself.
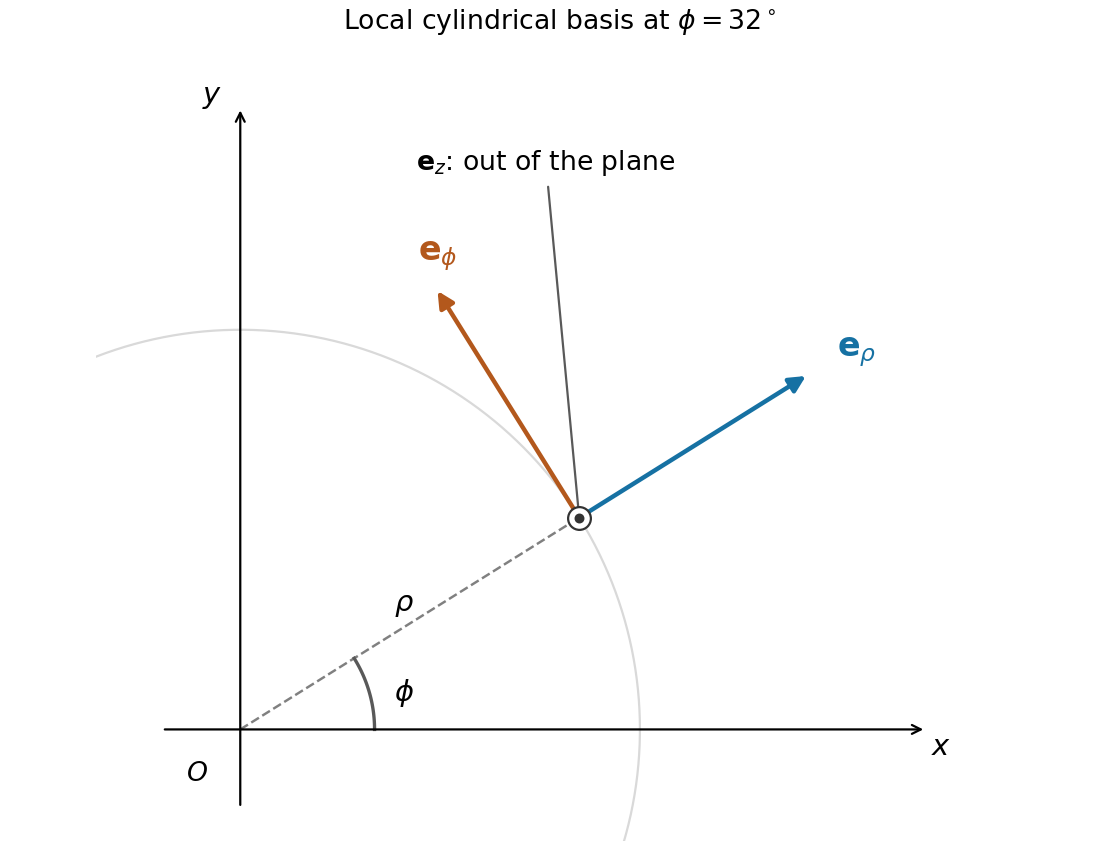
Cylindrical unit vectors relative to Cartesian axes, viewed from positive z
. Details. For the axial velocity profile, the cylindrical coordinates formula givesThe associated cross product isThis field has only a radial component depending on , so its curl is zero. Also . The identity above therefore yieldsIn fact both directional derivatives vanish: the first differentiates only in the azimuthal direction, and the second differentiates only in the direction. All physical vector fields extend smoothly through , despite the coordinate-basis singularity.
The substitution separates the uniform equilibrium from the decaying perturbation. Direct differentiation givesConsequently the reaction-diffusion equation reduces to the heat equation . Its data become
When the three constants coincide, the Dirichlet boundary conditions for are homogeneous. Separation of variables gives and , selecting the normal modes for . ThusTwo integrations by parts give , while the constant term uses . Therefore the Fourier sine series isFor , its first coefficient is nonzero. Multiplying by and retaining the slowest-decaying mode givesThe remainder estimate holds uniformly in for sufficiently large positive time. If , the fundamental vanishes and the next possible mode has decay rate , explaining the exclusion.
There is an initial endpoint compatibility issue unless : the given polynomial profile vanishes at the endpoints, whereas the boundary values equal . The series realizes the initial data in L2 space and pointwise in the open interval, imposing the prescribed boundary values for . For nonzero it cannot also be continuous at both initial endpoint corners.
Trying in the Cauchy-Euler equation givesso the homogeneous solution isContinuity with zero value at the singular endpoint excludes the second branch. Use the left and right adapted solutions , , whose Wronskian isThe Dirichlet Green kernel for an Euler operator with exponents one and minus four is thereforeIt vanishes at both endpoints, is continuous at , and has first-derivative jumpThus with ordinary source measure . For bounded forcing the Green function representation isThe apparent singular prefactor in the first term is canceled by the integral's decay at zero. The only regular homogeneous solution vanishing at is zero, so this solution is unique in the stated regular class.
For the piecewise source, split the integrals at . If , the needed integrals are and . If , only remains. Simplification yieldsAt the interface both expressions have value and derivative , so no unintended Dirac delta source appears. Their second derivatives have the allowed jump associated with the discontinuous forcing.
With the stated Fourier transform convention, the inverse Fourier transform and the deterministic autocorrelation of a square-integrable function areAssume initially sufficient decay and smoothness, for example a Schwartz function, to justify interchanging integrations and Fourier inversion. With , the cross-correlation identity isEvaluating directly and by its inverse transform at zero proves the Parseval identity:Approximation extends the identity to L2 space, as the Plancherel theorem.
For the compact cosine profile, the Fourier transform of a truncated cosine follows from :At the apparent singularities are removable, with value . The direct squared norm is . Hence Parseval identity and evenness givePutting makes the left side times the requested integral. ThereforeAt the integrand's continuous extension is , so no principal-value prescription is required.
A square matrix is invertible precisely when its determinant is nonzero. Equivalent conditions are full rank, a trivial kernel, and zero not being an eigenvalue.
For a lower triangular matrix, the first row has only the possibly nonzero entry . A Laplace expansion along that row gives , where the remaining principal submatrix is again lower triangular. Induction from the one-by-one case yieldsThis proof includes singular triangular matrices; it makes no division by diagonal entries.
For the diagonal example, put . Its determinant is , and invertibility requires . Write the complex number as with . A nonzero purely imaginary determinant requires . ThusEquivalently ; the angle is understood modulo .
For skew-Hermitian matrices, reversing products under the conjugate transpose gives . ConsequentlyThe latter condition is vanishing of the anticommutator. A universal choice for the last request isIndeed , so the commutator of two skew-Hermitian matrices is skew-Hermitian.
Over the chosen scalar field, an -by- matrix is diagonalizable if and only if it has linearly independent eigenvectors. Repeated eigenvalues are allowed provided all eigenspaces together supply a basis.
For the given matrix, the characteristic polynomial is . One may chooseTaking these as columns gives the change of basisThis is not a rotation matrix. The PDF's terminology cannot hold literally: is real and nonsymmetric, whereas a real matrix orthogonally similar to a real diagonal matrix is symmetric. Also , so scaling these eigenvectors cannot make an orthonormal rotation basis. A general invertible similarity is the valid construction.
Let . Inserting between successive factors gives , and henceTo write , match its action on the two eigenspaces:Solving gives the matrix powers for a diagonalizable matrix with two eigenvaluesThe cases recover , respectively. Equivalently the spectral projections of a diagonalizable matrix are and , and the power multiplies them by and .
The Cauchy-Riemann equations are and . A holomorphic function is smooth, so equality of mixed partial derivatives givesThus its real and imaginary parts are harmonic functions.
An entire function is holomorphic at every finite point of the complex plane. The globally convergent power series for the exponential implies that and are entire. Their difference therefore givesat every complex , proving that the hyperbolic sine is entire. For powers, the base case has derivative one everywhere. If is entire with derivative , the product rule gives everywhere. Induction proves that every positive integer power is entire.
A function has a pole of order at when it is holomorphic in a punctured neighbourhood and extends holomorphically to with . An isolated essential singularity is neither a removable singularity nor a pole; equivalently its Laurent series has infinitely many nonzero negative-power terms. In particularhas an essential singularity at zero.
For , the Laurent series about infinity isTo classify the point correctly, use . Then , and is holomorphic with value one at zero. ThereforeThe pole at infinity is compatible with an essential singularity at the finite point zero. Negative powers of are regular powers of the local coordinate near infinity, so they do not make that point essential.
Write a second-order linear ordinary differential equation in monic form . At a finite point , an ordinary point has analytic . A singular point is a regular singular point if and extend analytically there. A singular point failing this condition is an irregular singular point. The point at infinity is classified by the reciprocal coordinate .
For the Laguerre differential equation, and . Thus and are analytic at zero, while itself is singular: zero is regular singular. Put . Since and , the transformed equation isHere is not analytic at zero, so infinity is an irregular singular point, for every real .
For the Frobenius solution, the lowest power has coefficient . Hence the indicial equation is , and equating the remaining powers givesWith the repeated root , the Frobenius series for the Laguerre differential equation obeysIf the series does not terminate, its consecutive term ratio is asymptotic to , so the ratio test gives infinite radius of convergence. It is an entire function, even though the differential equation has a singular coefficient at zero. The repeated indicial root yields only one analytic Frobenius branch; an independent solution generally has a logarithmic term there.
For , the factor stops the recurrence at degree . With its coefficients are , giving the Laguerre polynomialsThe same termination argument includes , as required for despite the earlier reference to positive integers.
For endpoint-preserving variations of a functional, the Euler-Lagrange equation isAlong an extremal, the chain rule gives . Thus when has no explicit dependence, the Beltrami identity isFor a positive speed profile, the elapsed-time integrand in Fermat principle is . Its first integral givesIntegrating each monotone-height branch yieldsReal branches require . Turning points are joined in the original graph , even though the inverse derivative is singular there.
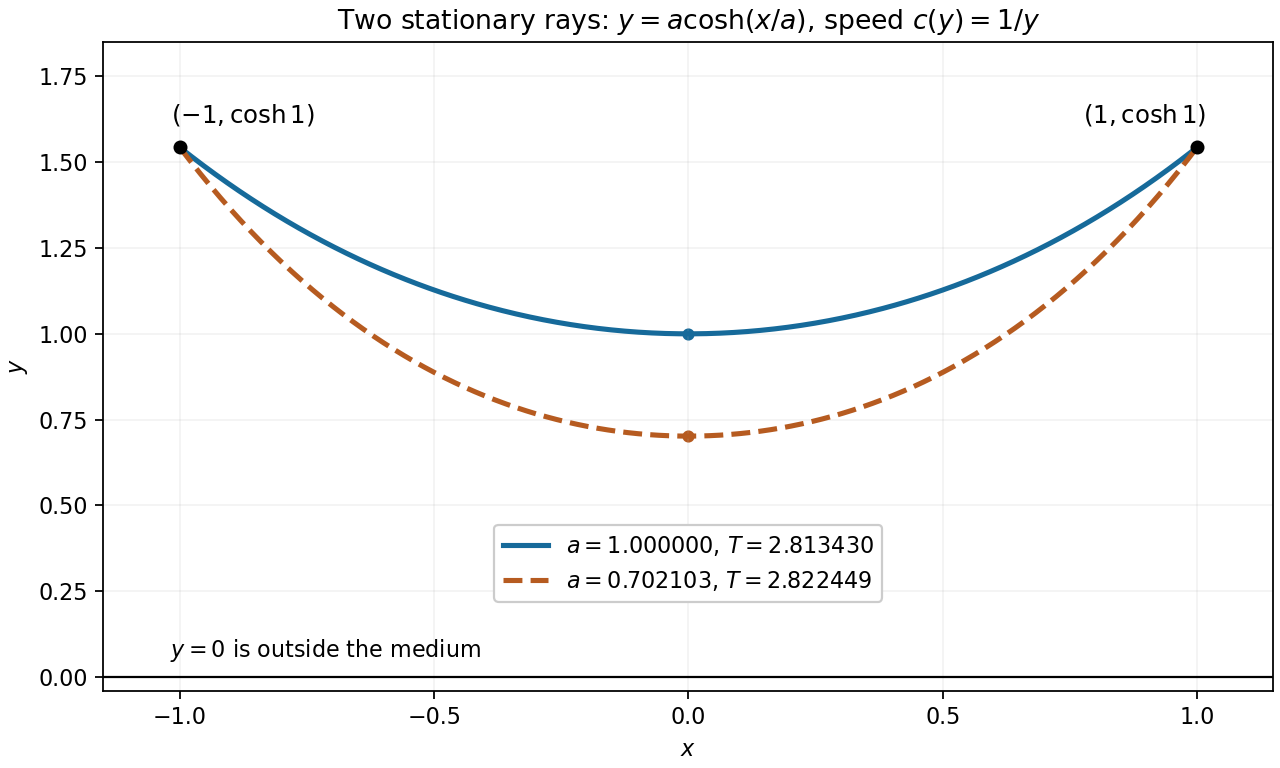
For the inverse-height speed profile, this becomes , with . Integration gives , so the light rays are catenariesEqual endpoint heights at opposite values force , since the real hyperbolic cosine is even and strictly increases with the absolute value of its argument. The remaining endpoint condition is . One exact solution is , givingHere and account for the squared hyperbolic cosine in the time integral.
The stated endpoints also allow a second stationary ray. Set . The function decreases and then increases: its derivative has the sign of , whose derivative is . Its unique minimum occurs where , at . Since the known root lies below this minimum's location, there is exactly one further root, . Thus the two stationary catenary rays in an inverse-height speed profile also includeNo extra condition in the question selects uniquely between these rays. The minimum height is a minimum along the chosen ray, not a global travel-time assertion. Indeed, competitors descending vertically to height , crossing horizontally, and rising again have time . As this tends to , below both stationary times. Their corners can be smoothed, so Fermat principle here must be understood as stationarity rather than unrestricted global minimization.
Use a Lagrange multiplier for the norm constraint. For real variations with , integration by parts givesThus stationarity is equivalent to the Sturm-Liouville problemMultiplying by and integrating shows , so the constrained stationary values are the eigenvalues, and the normalized stationary functions are their eigenfunctions. Conversely the eigenvalue equation makes the constrained first variation vanish. The self-adjoint operator has weight one.
For , zero and negative eigenvalues yield no nonzero solution with both Dirichlet boundary conditions. Positive eigenvalues have solutions after the left condition, and the right condition gives , . Hence the lowest eigenpair iswhere the amplitude follows from .
The Rayleigh-Ritz variational principle bounds the full lowest eigenvalue by . Its derivative contribution is one. For the linear potential, reflection about givesThus the sine trial bound for a linear potential on an interval isFor the bound is strict, since is not a constant multiple of . Also by the Poincaré inequality and the nonnegative potential. Equality in the upper bound holds at .
For two real eigenfunctions, multiply the equation for by and the equation for by , then subtract. The terms cancel. The resulting Lagrange identity for a Sturm-Liouville operator isIntegrating first over and then taking the endpoint limits givesThe needed assumptions are that the improper integral exists and that the displayed boundary expression tends to zero at both endpoints. Bounded and their first derivatives are sufficient because , but are stronger than necessary. Merely knowing that does not control arbitrarily growing eigenfunctions. With the vanishing boundary form and distinct eigenvalues, division by proves orthogonality of Sturm-Liouville eigenfunctions:For complex eigenfunctions in a real self-adjoint differential operator problem, use instead, giving the corresponding weighted inner product.
Multiplying the particular equation by puts it in Sturm-Liouville form:ConsequentlyIts polynomial eigenfunctions are the Laguerre polynomials. Products of these polynomials, with or without one derivative, grow only algebraically at infinity. The exponential in therefore makes the boundary form vanish there; its factor makes it vanish at zero. Their orthogonality is thus
For , substitution of gives . For , substitution of gives and . Choosing , which fixes the otherwise arbitrary nonzero multiplicative constants, yieldsTheir product is . Using the Gamma function identity , also obtainable by repeated integration by parts, verifies the required orthogonality directly:
The Dirichlet uniqueness for the Poisson equation follows from a positive integral. Suppose satisfy the same data, and put . Then is a harmonic function in and vanishes on . Green's first identity, applied with both arguments , givesThus , and is constant on the connected body. Its zero boundary value makes that constant zero. This proves at most one temperature field; it does not require an independent existence construction. As usual, the argument assumes a bounded body and sufficient regularity for Green's first identity, or the corresponding finite-energy weak formulation.
For the composite body, let and be the differences in and . They are harmonic functions, have a common interface value , and obeyThe unit normal vector points out of ; the outward normal of on its inner boundary is . Keeping that sign in Green's first identity givesThe outer boundary term in is zero. Weight these equations by the positive coefficients that match the flux condition:Both Dirichlet energies must vanish. Hence both differences are constants; the outer data set the constant in to zero, and interface continuity sets the constant in to zero. This establishes uniqueness for a harmonic transmission problem. Physically and play the roles of the inner and outer thermal conductivities; continuity of temperature and normal heat flux is what cancels the interface contribution.
Write . A rotationally symmetric fundamental solution of the Laplace equation is harmonic for . The Laplace equation in polar coordinates reduces to , so . Integrate over a disk of radius around the source. The divergence theorem givesTaking therefore givesChanging the reference length inside the logarithm merely adds a constant. Notice the sign convention: the potential equation in this question is , whereas this Green function satisfies . Thus the point-source potential used below is .
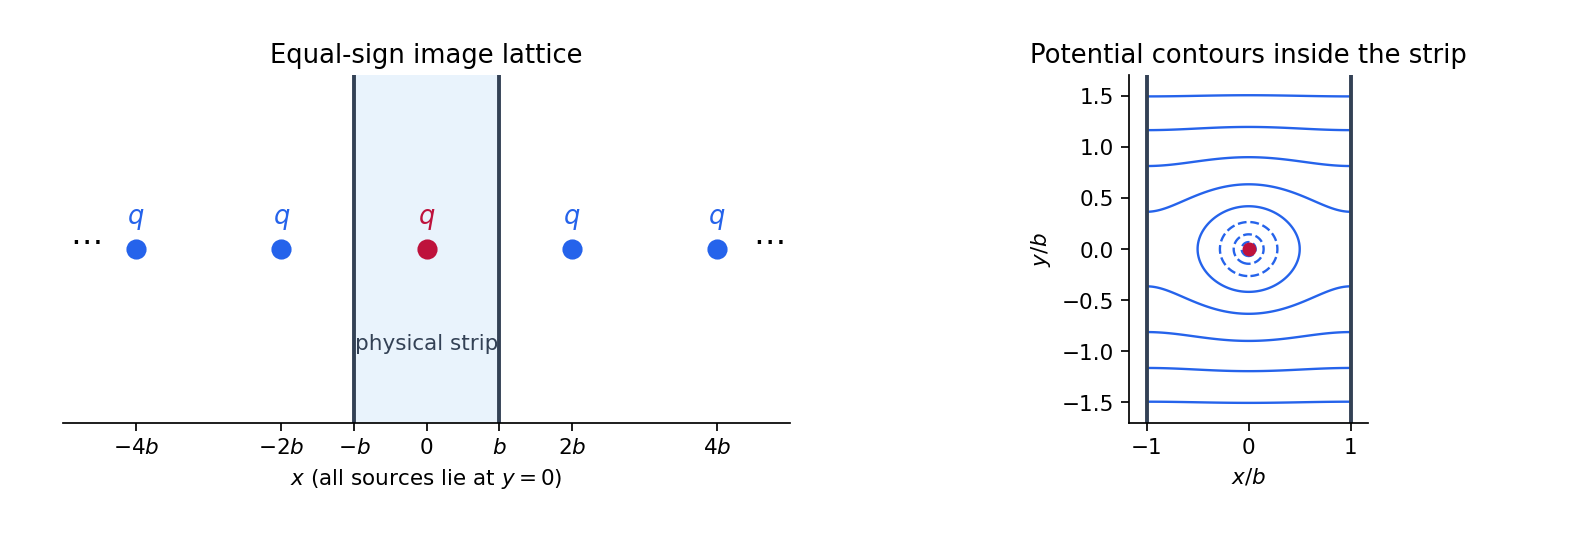
For the two insulating walls, successive Euclidean reflections in and generate sources of strength at for every integer . Only lies inside the physical strip. This is the Neumann image lattice for a point source in a strip. SetThe raw sum of logarithmic potentials diverges by additive constants. A well-defined potential is obtained by pairing opposite images and subtracting their constant reference terms:Each paired summand is on compact subsets away from the source. The series therefore has local uniform convergence, as do the required derivative series. It givesIn the corresponding -derivative, the images pair as and at , and as and at . Their opposite horizontal separations make the derivatives cancel. Thus both homogeneous Neumann boundary conditions hold. The constructed solution is even in ; without a condition at infinity the side conditions alone would allow further homogeneous harmonic functions.
For fixed , uniform convergence on permits integration term by term. The th term has integralHere is the ordinary real inverse trigonometric function, taking values in . Summing from to makes a telescoping series:The source flux splits equally between the upper and lower parts of the strip. The next two parts give the single-wall constructions that underlie the image lattice.


For the grounded wall, use an image charge at . Define the Euclidean distances and . The method of images givesThe real source has the required Dirac delta function coefficient, and the image is outside the domain. On , , so exactly. This verifies the Dirichlet boundary condition rather than only its derivative.
For the insulating wall, the image instead has the same strength . With the distances defined above,It has the required source in the physical domain. Its normal derivative isAt the terms are and , so they cancel. The Neumann boundary condition leaves the additive constant free.
For a positively oriented simple closed contour , with no pole on and with holomorphic inside except at finitely many poles, the residue theorem statesFor a more general closed contour, each residue is multiplied by its winding number about the pole.
The powers must be defined using the same branch of the complex logarithm as the numerator. A branch suitable for both requested calculations isThe branch cut is a ray just below the positive real axis, and . Since , the displayed choice of is possible. It includes the required upper half-plane and the sector used below. The origin remains an excluded branch point.
In , all zeros of areEach is a simple pole, since . Its residue isThe strict inequality matters if a root lies on the negative real axis, which is outside the specified region.
To evaluate the two improper integrals, write them as for the logarithmic numerator and for numerator one, and set , . Use a counterclockwise annular sector with and . It encloses precisely . The outward positive-axis segment contributes in the limit. On the inward segment , the logarithm is and , so that segment contributes .
The small arc is , and the large arc is ; both vanish. These estimates follow from the arc lengths and . The real integrals also converge absolutely at both endpoints for . The residue theorem now givesAfter division by , the real and imaginary parts areSince , . Hence the logarithmic beta integral from a sector contour yieldsFor the sector angle exceeds . This is why choosing the principal complex logarithm on the whole sector would be invalid; the displaced cut above handles that range as well as .
First prove the convolution theorem with the stated negative-exponential Fourier transform. Assuming absolute integrability sufficient for Fubini's theorem, change variables :
For the differential equation, integration by parts givesThe boundary terms vanish by the assumed decay of . As with the convolution step, the transforms can first be justified for integrable functions and derivatives; the resulting kernel gives the desired decaying response. ThusThe convolution theorem and Fourier inversion theorem imply .
For the inverse transform of , useThe poles are at . For , close the inverse-transform contour above; the residues of there are and . The inverse-transform factor makes the answer times their sum. For , close below, enclosing no poles. The large arcs vanish: the complete rational factor is and the exponential is bounded on the appropriate semicircle. Therefore the causal Green function of an overdamped oscillator isIt is continuous, with and , so . The response can also be written .
For the bilateral exponential forcing, split the real integral at zero:ConsequentlyFor negative time the lower half-plane contains only . The residue of there is . Clockwise closure makes the inverse transform times that residue. For positive time the three upper residues, at respectively, areMultiplication of their sum by gives the bilateral exponential forcing of an overdamped oscillator:Both expressions have . This verifies the matching that prevents an extra Dirac delta function at zero. Direct substitution gives the forcing on either side, and all terms decay at their corresponding infinities. A causal Green function does not imply zero response before when the forcing has already been acting at negative times. The assumptions avoid repeated poles; their limiting cases would contain polynomial times exponential terms.
Let be the orthogonal matrix taking old components to new ones, so . With repeated indices summed, the tensor component transformation law isAn isotropic tensor has the same components after every proper rotation. Since , the Kronecker delta is invariant. Applying this identity to each factor shows that and every linear combination are invariant as well.
To show that an isotropic second-rank tensor must be scalar, start with any matrix , without assuming symmetry. Invariance under quarter-turns about axes 1 and 2 implies invariance under their squares, the half-turnsThe first forces to vanish. The second also forces to vanish. The matrix is therefore diagonal. A quarter-turn about axis 1 interchanges its 22 and 33 entries; one about axis 2 interchanges its 11 and 33 entries. All three must agree, giving .
A rotation preserves the ball , and the volume element. Changing integration variables by that rotation shows that and are isotropic tensors. Write . Taking its tensor contraction givesso . Every permutation of the indices of leaves its integrand unchanged. Its complete symmetry therefore makes all three isotropic coefficients equal, say :Double contraction gives . Thus the isotropic fourth moment of a ball and its radial contraction are
Put , so that . Contract with the prescribed unit vector twice:This has the spectrum of a scalar matrix plus a rank-one projector. In the direction , the outer product acts as the identity; on the plane perpendicular to , it acts as zero. ThereforeAny nonzero multiple of is a parallel eigenvector, and any nonzero vector in the perpendicular plane is a transverse eigenvector. The transverse eigenvalue has multiplicity two; an orthonormal basis of that plane completes a set of principal axes.
The Lagrangian is , and the Euler-Lagrange equations areAt a rest equilibrium , for all three coordinates. The Taylor expansion therefore starts asThe symmetric Hessian matrix is the matrix of the quadratic potential energy. If a quadratic coefficient vanishes along a direction, higher-order terms can be the first nonconstant terms there; equilibrium by itself does not imply strict stability.
Write . Terms involving the variation of are cubic in small displacements and velocities, so the quadratic small oscillation Lagrangian isA normal mode has fixed displacement ratios, . Its angular frequency is an eigenfrequency, or normal frequency, and satisfies the generalized eigenvalue problem for small oscillationsHere is positive definite for independent physical coordinates and positive masses. A stable quadratic minimum makes ; a negative value would describe exponential instability rather than oscillation.
For the suspended bar, let and denote the actual incremental spring constants of the upper and each lower spring. The physical displacement of the bar is , while the lower spring extensions change by and . ConsequentlyThe linear gravitational and elastic terms cancel at the loaded equilibrium. Expanding the remaining squares gives the small-oscillation mass and stiffness matricesThusSource convention: the printed matrix is obtained by setting and . Although the PDF prose calls spring constants, that matrix treats them as elastic parameters whose ratios to the stated lengths are the incremental stiffnesses. If they are read literally as Hooke-law spring constants, the divisions by should instead be omitted. The numerical case has , so this discrepancy does not affect its results.
With the numerical parameters, andUse the exchange symmetry of the lower masses to find the vertical modes of a horizontally constrained suspended bar. The antisymmetric vector obeys , giving . In the symmetric sector put and . The two independent equations areTheir determinant gives , so . Taking , the full set isIn the lowest normal mode, all three masses move in phase, with the lower masses moving about times as far as the bar. In the antisymmetric normal mode, the bar stays still and the lower masses move equally in opposite directions; their changing forces on the bar cancel. In the highest normal mode, the lower masses move together against the bar, with magnitude about of its displacement. Any small motion is a superposition of these three modes.
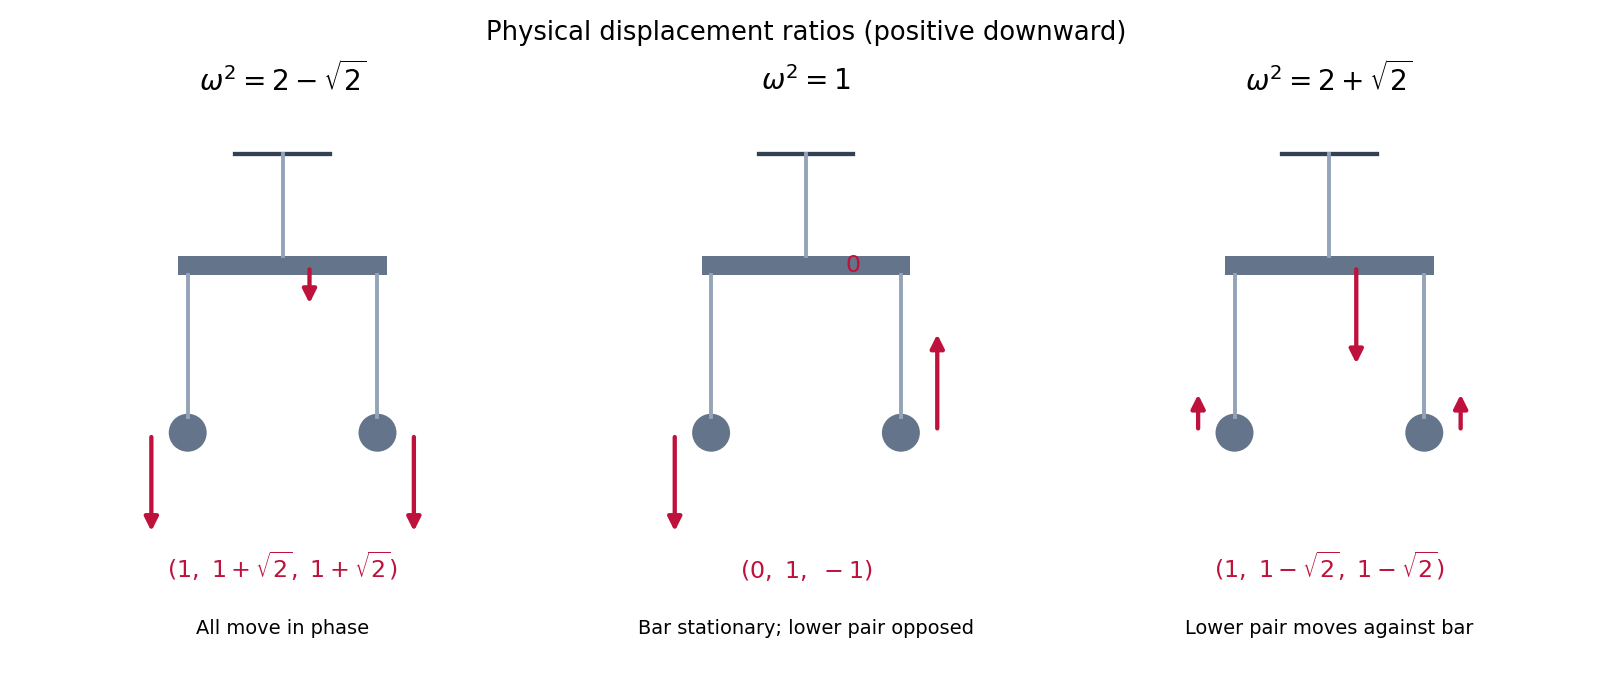
Relative vertical displacements in the three normal modes, with the bar constrained to remain horizontal
. Details. 
The group order of a finite group is its number of elements, . The order of a group element is the least positive integer with . Such an exists in a finite group because two powers must coincide, and cancellation then gives a positive power equal to the identity element.
For the direct product of groups, the componentwise operation is closed because each factor is closed. Associativity holds in each coordinate:The identity element is , and the inverse element of is . Thus all group axioms hold. For finite factors, the multiplication principle gives
For , write , , , , with . Its Cayley table, with the row element multiplying the column element, isThis is the Klein four-group: every nonidentity element has order two.
In the cyclic group , the set is closed because , and both elements have inverses in the set. It is therefore a proper subgroup of order two. By Lagrange's theorem, a proper subgroup has order one or two. An order-two subgroup must be generated by an element of order two. Neither nor has order two, whereas does. HenceThe PDF's claim needs “nontrivial”: is the only nontrivial proper subgroup, but is also a proper subgroup under the usual definition.
A group isomorphism preserves element orders: if and only if , using the homomorphism property and injectivity. Since has elements of order four and the Klein four-group does not,
The intersection contains the identity element. If , then belongs to both and , so it belongs to their intersection. The subgroup test proves that is a subgroup of , with the inherited operation. Explicitly, closure and inverses come from this test, and associativity is inherited from .
Label the vertices of the equilateral triangle counterclockwise. For the dihedral group of order six, let be the counterclockwise rotation by , and let be reflection in the line through vertex 1 and the opposite side's midpoint. ChooseThen rotates by . The three Euclidean reflections fix vertices respectively. Products act on a vertex from right to left. The relations and givewhere exponents of are reduced modulo three and those of modulo two. This constructs the entire Cayley table:For example whereas , so the group is nonabelian.
A subgroup of order two is generated by its unique nonidentity element, which must have order two. The rotations have order three, and each reflection has order two. Thus there are exactlyNone is a normal subgroup. Conjugation by sends the reflection to , cycling the three reflections. For example . Each of the other two subgroups fails the same conjugation test.
Finally, take two distinct such subgroups. For instance their union is , but lies outside it. Thus it is not closed under the inherited group operation and is not a group. The distinctness is necessary: the union of a subgroup with itself is that subgroup.
For the matrices, put , and . Since , and , direct matrix multiplication givesThese verify the listed matrices and the defining relations, with . To check every product explicitly through a single calculation, write elements in the unique form , with and . The relations giveThe displayed matrices obey , so their product has exactly the same form:All exponents are reduced modulo two or three respectively. Thus this verifies all 36 products, and is a two-dimensional complex group representation. It is given to be an irreducible representation.
For a one-dimensional complex group representation , let and , which are nonzero complex numbers. The relations requireSince scalar multiplication commutes and , the last relation gives , hence . Then . The choice is the trivial representation; the unique nontrivial choice is the sign representation:Its group kernel isA faithful representation is injective and has trivial kernel. Here the kernel has three elements, so is not faithful.
Both one-dimensional representations are irreducible representations, and they are inequivalent to each other and to the given two-dimensional one. The sum of squares of irreducible representation dimensions givesThese exhaust all complex irreducible representations. Their number equals the number of conjugacy classes, so there are three conjugacy classes. Explicitly they areThe last two sets consist of the 3-cycles and transpositions respectively.
Articles by others on the same topic
There are currently no matching articles.